
Are Hamburg Grid Contracts Altering The Investment Case For NKT (CPSE:NKT)?
- NKT received three high-voltage AC onshore cable contracts from Hamburger Energienetze for Hamburg's 110 kV grid, covering more than 50 kilometres of XLPE cables and full-scope delivery from design to commissioning.
- The award concentrates production in NKT facilities in Cologne and Velke Mezirici, highlighting the value of local content and turnkey execution capability for Germany's grid expansion.
- This contract award for the full-scope Hamburg grid upgrade may influence how investors view NKT's overall investment narrative.
Scan beyond NKT and this Hamburg grid upgrade to find other power grid infrastructure stocks with momentum using our curated 43 power grid technology and infrastructure stocks.
NKT Investment Narrative Recap
NKT appeals to investors who focus on long term power grid build out and see value in a cable manufacturer with integrated installation and service capabilities. The short term focus is still on converting a large high voltage backlog into revenue and cash, while avoiding excessive reliance on low margin variation orders that weigh on profitability.
The Hamburg contracts fit neatly into that story but do not appear transformational on their own. They support the grid expansion theme and highlight turnkey strength. The larger uncertainty remains whether heavy capex and working capital demands shift toward more consistent free cash flow or continue to strain the balance sheet.
The Hamburg award aligns most directly with the existing high voltage narrative, where NKT already reports a €10.1b backlog and €3.5b in customer commitments. Investors looking for evidence that this book translates into higher quality earnings may view a locally produced, turnkey German grid project as additional confirmation of operational depth in the Solutions segment.
However, the main operational debate still centers on execution risk from the roughly €2b capex plan and the history of volatile cash generation. This contract reinforces that NKT plays a role in European grid expansion, but it does not resolve concerns about project timing, permitting delays or the possibility that heavy investment keeps free cash flow under pressure.
NKT's current consensus narrative assumes revenue reaches €5.3b and earnings hit €465.2m by 2029. This outlook is based on 13.7% yearly top line growth and an earnings increase of about €197m from €268.0m today.
Uncover why NKT's fair value indicates an 11% potential upside to its current price before the market prices out the discount.
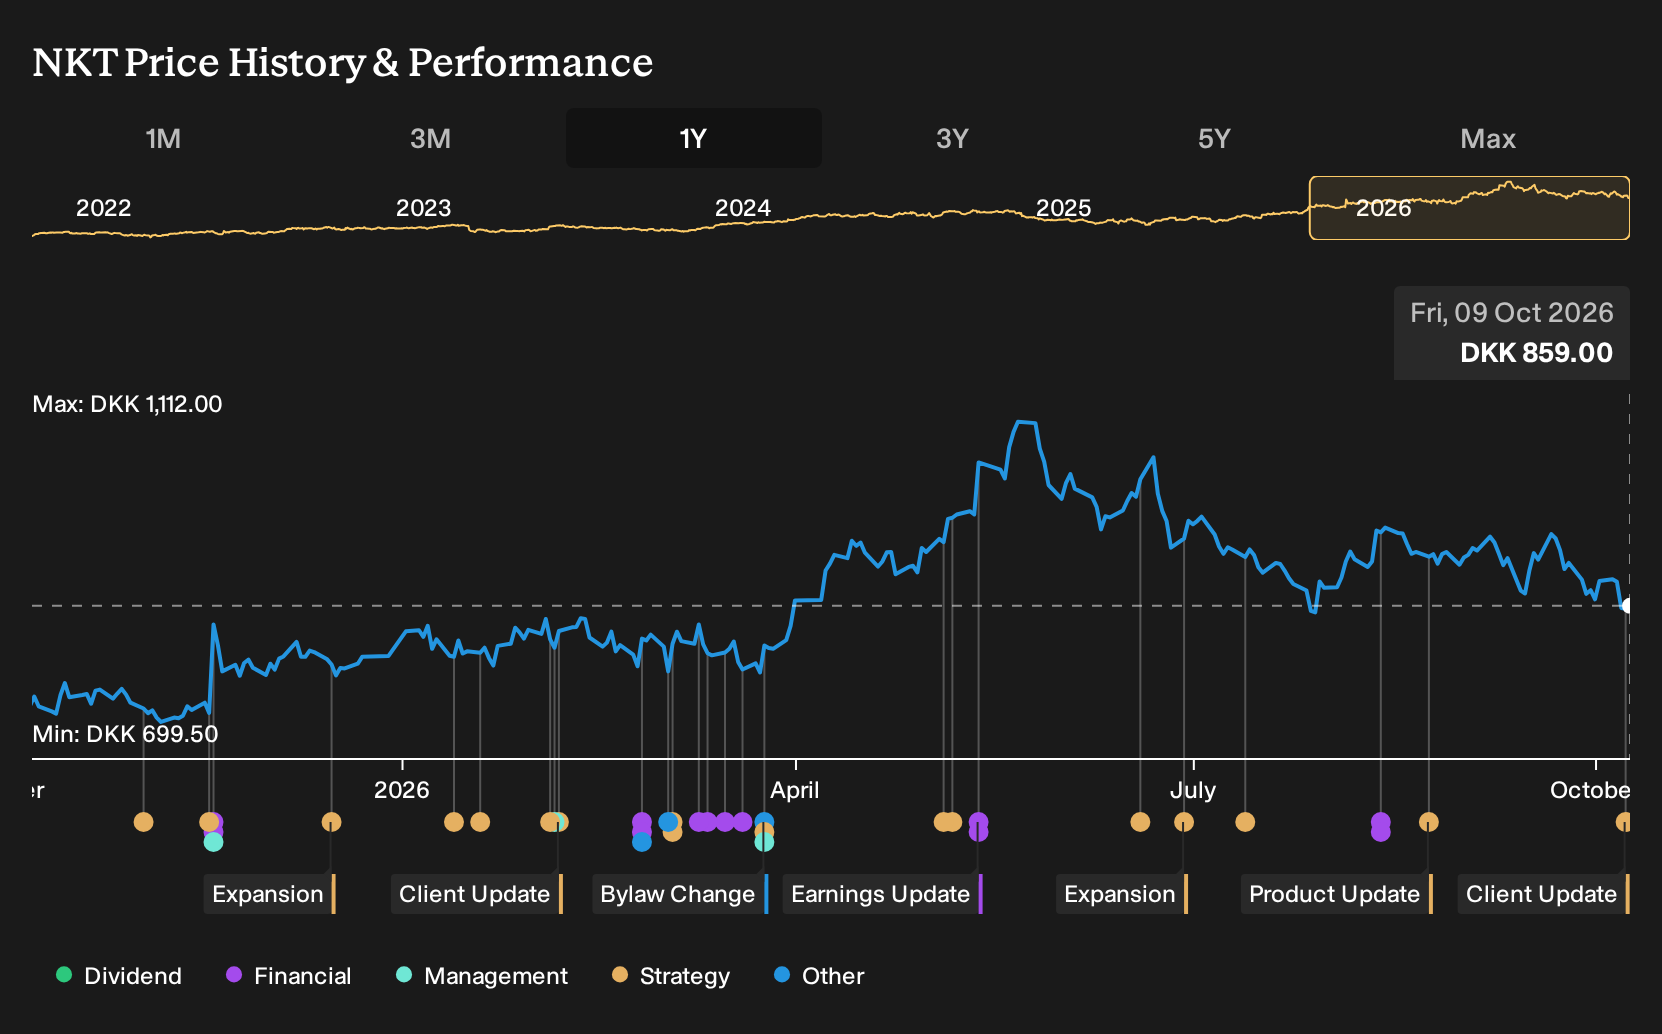
Exploring Other Perspectives
You might see these Hamburg contracts as proof that NKT can keep high voltage work flowing. However, the lowest analysts lean hard into customer concentration risk. They were assuming revenue of about €5.0b and earnings near €454.8m by 2029. Those views were set before this news, so opinions may evolve.
Explore 3 other NKT fair value estimates, including one that suggests it could be worth just DKK 952.88.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your NKT research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NKT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NKT's overall financial health at a glance.
Looking for more investment ideas beyond NKT?
Once you have a view on NKT, it often helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can surface these quickly so you spend more time assessing the story and less time trawling through tickers.
- If you want income to do more of the heavy lifting in your returns, focus on companies screened as 223 dividend fortresses that might align with a yield oriented approach.
- If capital preservation is your priority, concentrate on businesses in the 223 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If you prefer to hunt earlier in the cycle, use the 618 high quality undiscovered gems to see lesser known stocks that still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com