
Should Motion Capture Lab Opening Require Action From Innodata (INOD) Investors?
- Innodata has opened a New Jersey R&D lab built around high precision infrared motion capture cameras, supplying sub millimeter 3D training and evaluation data for humanoids, industrial robots, and other physical AI platforms.
- The facility gives Innodata a proprietary source of high quality robotics datasets and independent performance validation services, deepening its physical AI offering across the full data lifecycle.
- This development provides additional context for Innodata's investment narrative, particularly in relation to physical AI data infrastructure.
Scan how Innodata’s physical AI push compares with other potential breakouts in robotics and AI infrastructure by reviewing the hand picked 92 AI infrastructure stocks today.
Innodata Investment Narrative Recap
To own Innodata, you need to believe the company can keep turning surging AI and robotics data demand into durable, higher margin work across its Digital Data Solutions, Synodex, Agility, and now physical AI offerings. The key near term swing factor is whether new programs offset any lumpiness from a handful of large technology customers.
The New Jersey motion capture lab looks additive to that story but probably does not change the biggest immediate risk. A rich P/E multiple and heavy reliance on a few hyperscale and Big Tech clients leave the business exposed if AI program rollouts slow or customers internalize more training and evaluation work.
The recent focus on Innodata’s AI Cyber Training Suite ties closely to the robotics lab. Together, they broaden the firm’s role in model evaluation, trust, and safety, areas that regulators and large customers are watching closely. That matters if you think future AI spend tilts toward verification and monitoring rather than just raw training runs.
For catalysts, the appeal is that a deeper portfolio of safety and observability offerings may support pricing and help win longer contracts, especially with federal and enterprise buyers. Execution risk stays high, because the bar set by the current valuation means any disappointment in new AI or physical AI program wins could hit the stock hard.
Innodata's current analyst narrative points to forecast revenue of $642.6 million and consensus earnings of $77.6 million by 2029. This assumes revenue grows at 26.5% a year and earnings rise by about $31.1 million from $46.5 million today.
Uncover why Innodata's fair value indicates a 98% potential upside to its current price that could narrow quickly.
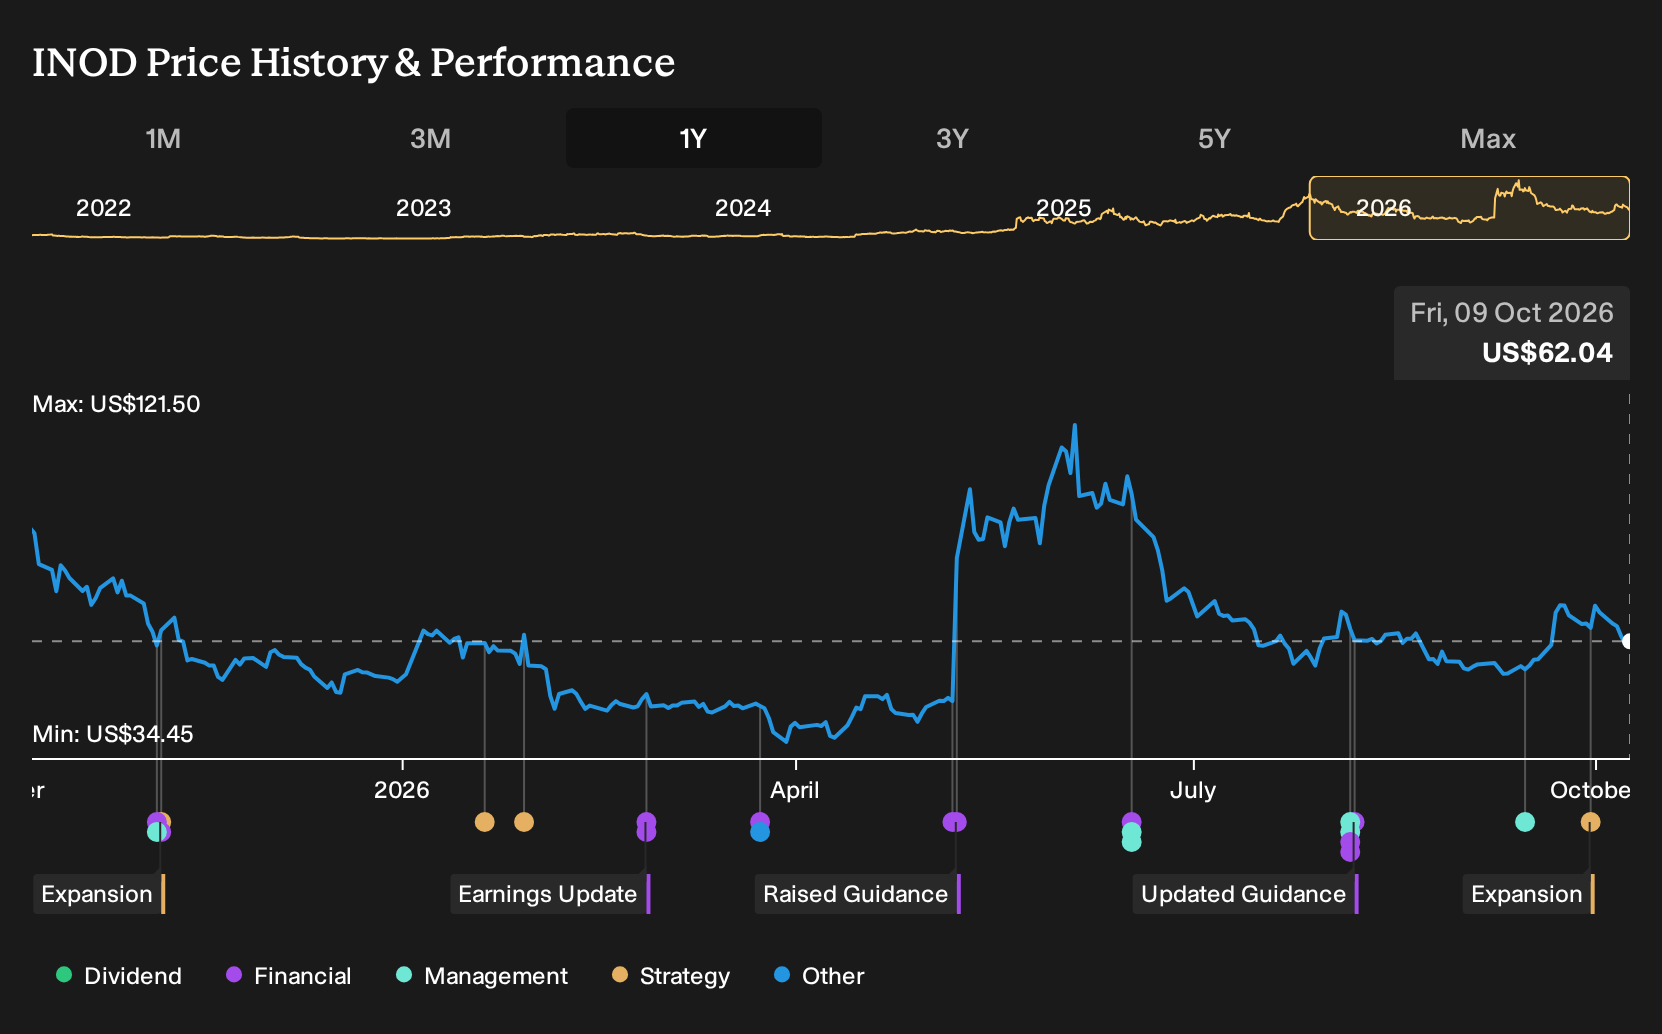
Exploring Other Perspectives
One alternate, more optimistic angle on Innodata leans hard into the physical AI catalyst itself. The most bullish analysts were already modeling revenue of about $725.5 million and earnings of $114.3 million by 2029, compared with consensus at $642.6 million and $77.6 million. You can treat this new robotics lab as a fresh test of which narrative wins out and explore both viewpoints before deciding where you sit.
Explore 5 other Innodata fair value estimates, including one that suggests up to 126% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Innodata research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Innodata. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Innodata's overall financial health at a glance.
Looking for more investment ideas beyond Innodata?
If Innodata's physical AI story has your attention, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you keep your watchlist grounded in clear data rather than headlines.
- For investors hunting quality at a discount, compare Innodata's setup against a curated group of 29 high quality undervalued stocks that pair fundamentals with more modest pricing.
- If capital preservation sits high on your priority list, stress test your ideas against a 31 resilient stocks with low risk scores that focus on stability and cleaner risk profiles.
- When you want sturdier balance sheets alongside solid business quality, broaden your research with a list of solid balance sheet and fundamentals (25 results) to see how Innodata stacks up on financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com