
Is Nabtesco (TSE:6268) Undervalued As Its Buyback Ends And Guidance Sharpens?
Nabtesco (TSE:6268) just wrapped up a share repurchase program and updated its earnings outlook, providing fresh information on capital allocation and expected profitability for the current fiscal period.
Recent trading reflects that backdrop. The share price is now ¥4,859, with a 1-month share price return of 8.05% and a year-to-date share price gain of 26.87%. The 1-year total shareholder return of 31.69% and 3-year total shareholder return of 88.54% point to strong longer term momentum despite a 90-day share price decline of 10.48%.
Scan for other industrials where management is putting cash behind their conviction by buying back equity and guiding on earnings using the hand picked list of solid balance sheet and fundamentals (23 results).
Nabtesco has already rewarded holders with strong multi year returns and a sharp recent move, yet current guidance and the completed buyback still leave one big issue on the table. How much upside is already in the price?
Most Popular Narrative: 9% Undervalued
Nabtesco's most followed valuation narrative puts fair value at ¥5,318, which sits above the latest ¥4,859 close and frames the recent buyback and guidance in a more constructive light.
The company's recent divestiture of its low-margin Hydraulic Equipment business allows Nabtesco to focus on higher-growth, higher-margin core segments such as precision reduction gears and motion control systems. This directly supports improvements in long-term operating profit margins and earnings quality. Nabtesco is actively reallocating capital and R&D resources toward smart motion control and advanced automation technologies, which is described as positioning it to benefit from increasing automation and digitization trends in manufacturing and logistics and to support sustainable future revenue growth.
See why 2 investors see Nabtesco as 9% undervalued.
Result: Fair Value of ¥5,318 (UNDERVALUED)
Still, this story can break if restructuring drags on longer than expected or if exposure to cyclical marine and railroad demand leads to sharper swings in earnings.
Find out about the key risks to this Nabtesco narrative.
Another View: What Nabtesco’s P/E Is Telling You
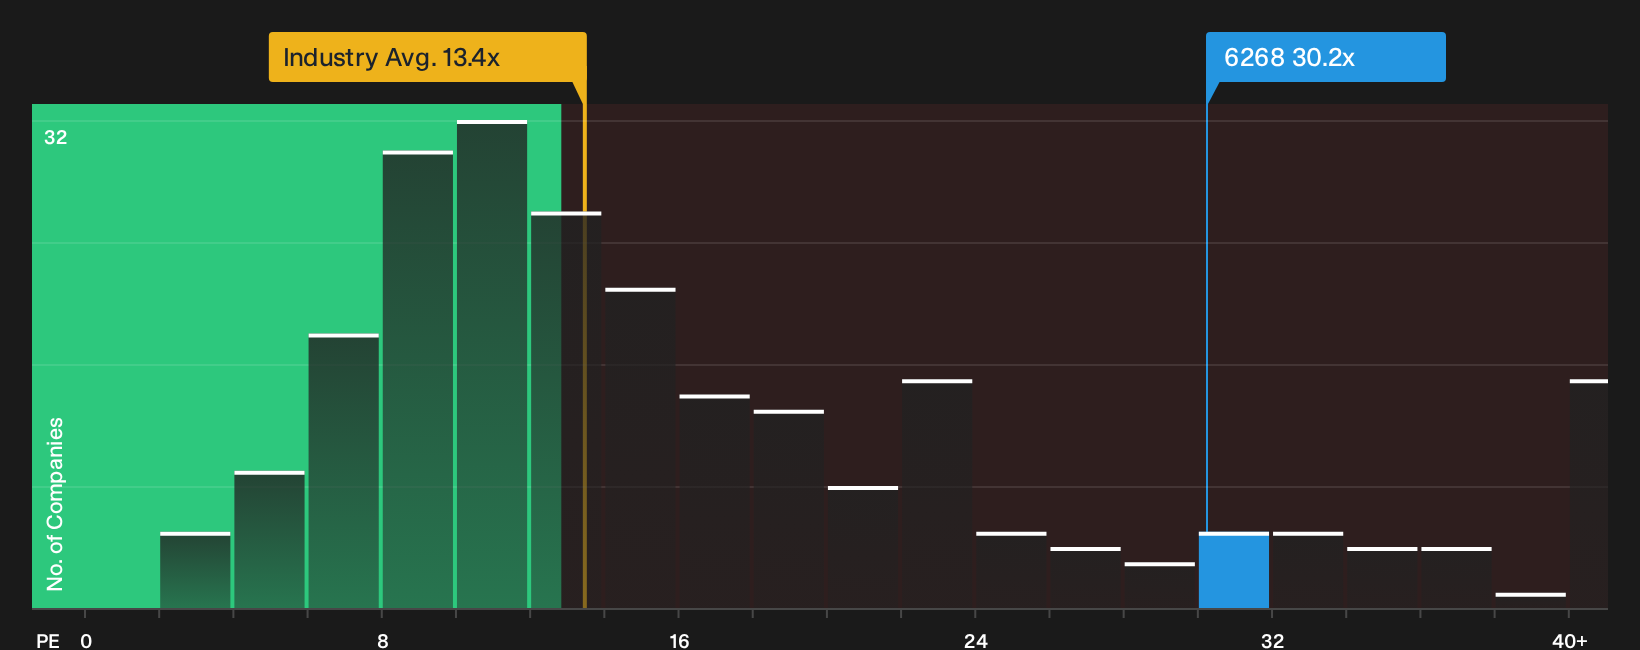
The share buyback and analyst fair values paint Nabtesco as attractive, yet the current P/E of 30.2x is far above both the Machinery industry on 13.4x and its own fair ratio of 19.9x. That gap points to valuation risk. Is the premium really worth paying?
Our preferred multiple check goes into this pricing gap in more detail, including how it compares against peers and that 19.9x fair ratio, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern feels familiar, that is exactly why Nabtesco deserves a closer look on your own terms. Start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nabtesco?
Do not stop with Nabtesco alone. Use the Simply Wall Street screener to quickly surface other opportunities that fit the kind of portfolio you actually want to build.
- Hunt for quality at a reasonable price with a targeted set of 13 high quality undervalued stocks that pair solid fundamentals with more appealing entry points.
- Build a steadier income stream by reviewing a focused group of 28 dividend fortresses that combine higher yields with more robust financial profiles.
- Dial back portfolio risk by scanning a curated pool of 23 resilient stocks with low risk scores that score better on balance sheet strength and overall resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com