
Open Up Group (TSE:2154) Reshuffles Leadership, Is The Valuation Gap A Bargain?
Open Up Group (TSE:2154) is reshaping its leadership after shareholders and directors approved revised appointments, moving Yutaka Nishida to Chairman and Representative Director and elevating Asako Hayata to President and Representative Director, COO.
Recent trading has been relatively steady, with the share price at ¥1,989 and a 30-day share price return of 2.74% alongside a 9.23% year to date share price gain. The 1-year total shareholder return of 23.00% points to momentum that has been building rather than fading as Open Up Group moves through this leadership transition.
Compare Open Up Group's leadership reshuffle with other companies that may be gearing up for their own next phase of growth by scanning our curated list of 74 high quality undiscovered gems.
Open Up Group now trades at a sizeable discount to both analyst targets and an estimated fair value. Is that a simple valuation gap, or a market warning about execution under the refreshed leadership team?
Preferred P/E of 14.3x: Is it justified?
Valuation for Open Up Group hinges on a P/E of 14.3x, which sits below some peers yet slightly above the broader Japanese professional services sector.
P/E compares the current share price with earnings per share. For a people intensive operation such as engineer dispatch and outsourcing, that lens helps you see how much investors are paying for each unit of profit today.
The stock is described as good value versus both the peer average P/E of 20.6x and an estimated fair P/E of 17x. That combination points to a market that is putting a lower price tag on each yen of Open Up Group's earnings than both similar businesses and the level our regression based fair ratio implies the market could move toward.
Compared to the JP Professional Services industry average multiple of 13.3x, the shares trade at a small premium. Against the peer group at 20.6x and the inferred fair P/E of 17x, the discount is far sharper, which signals investors are pricing in more caution around execution or growth durability than those benchmarks suggest.
Explore the SWS fair ratio for Open Up Group.
Result: Price-to-earnings of 14.3x (UNDERVALUED).
Still, Open Up Group relies heavily on engineer dispatch and construction markets. As a result, any slowdown in client demand or staffing costs compressing margins could quickly challenge that valuation gap.
Find out about the key risks to this Open Up Group narrative.
Another view on Open Up Group's value
The discounted cash flow work presents a more detailed perspective. At ¥1,989, Open Up Group is described as trading 46% below an estimated future cash flow value of ¥3,682.53, which labels the stock as undervalued. This raises a key question: is this a genuine mispricing or a sign that the market doubts those cash flow assumptions?
Look into how the SWS DCF model arrives at its fair value.
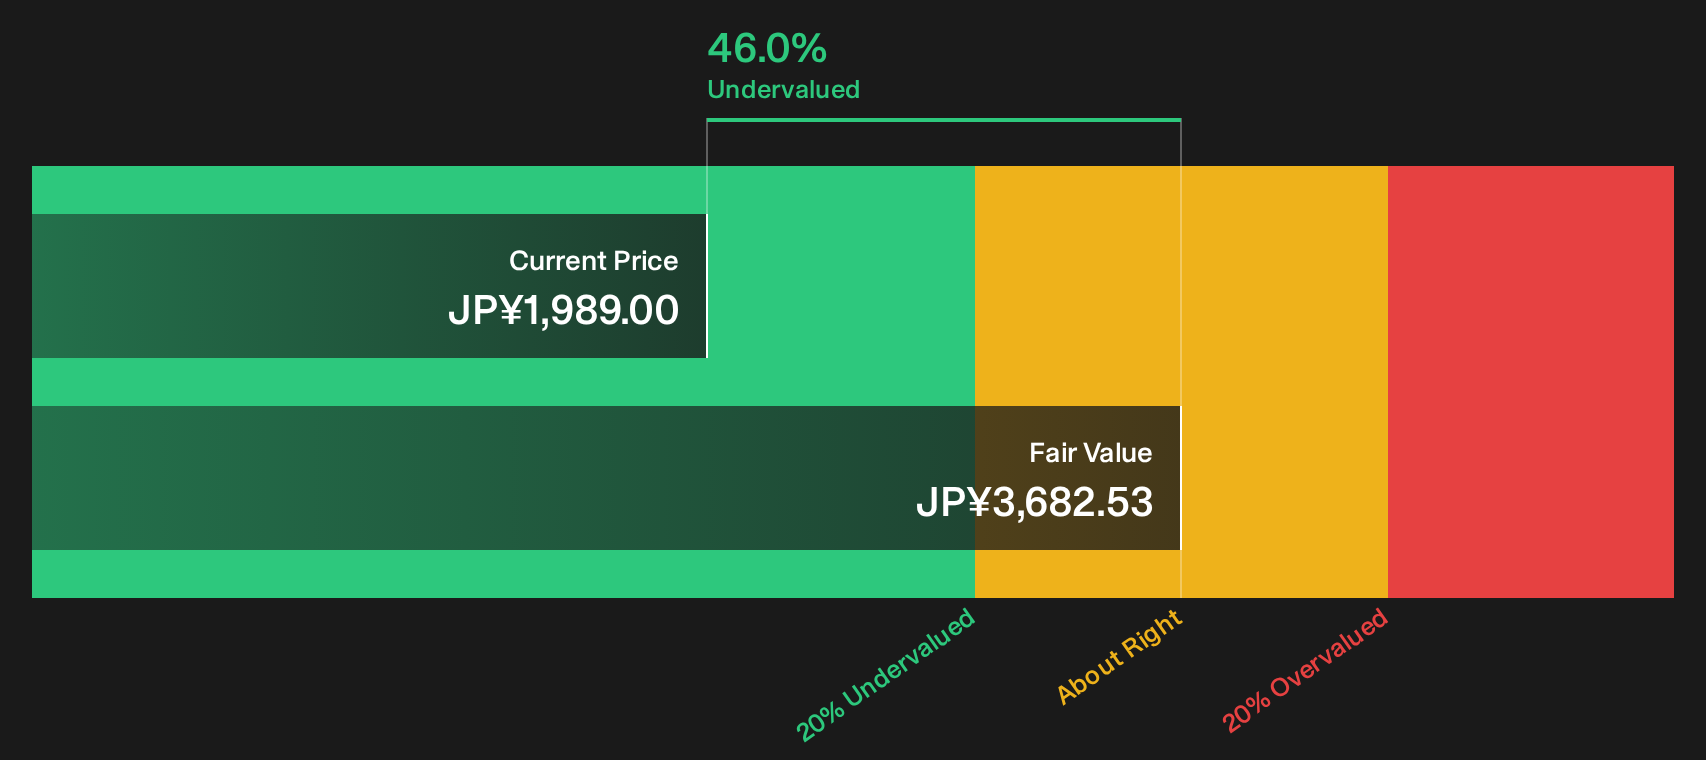
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Open Up Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Open Up Group's valuation and leadership shift invite your own judgment. Move quickly, review the full picture, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Open Up Group?
Do not stop with Open Up Group. Broaden your watchlist with fresh opportunities surfaced by Simply Wall Street screeners that focus on quality, value and resilience.
- Target potential mispricings by scanning companies that currently screen as attractively valued using our 13 high quality undervalued stocks.
- Prioritise resilience under pressure and filter for businesses that carry stronger financial footing with the list of solid balance sheet and fundamentals (23 results).
- Zero in on stability focused opportunities that show lower overall risk profiles with the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com