
Ivanhoe Mines (TSX:IVN) Reaffirms 2026 Guidance As Valuation Debate Builds
Ivanhoe Mines (TSX:IVN) just put fresh operating data on the table, reporting third quarter copper output of 76,401 tonnes and reaffirming its 2026 production guidance while indicating performance near the lower end of the range.
That operational update lands after a choppy year for Ivanhoe Mines, with the share price down 27.68% year to date and 9.38% over the past month, yet showing a 12.84% 90 day share price return and a 5 year total shareholder return of 17.41%. This points to long term holders still being ahead despite recent pressure.
Scan beyond Ivanhoe Mines and line up other copper focused producers by fundamentals with the curated 16 top copper producer stocks that could be setting up for their next move.
Ivanhoe Mines has real assets and growing operations, yet the share price has been sliding this year. Is that recent drop enough to make the current valuation look fair, rich, or still compelling on the numbers?
Most Popular Narrative: 26% Undervalued
On the most followed view, Ivanhoe Mines screens as undervalued, with a fair value estimate of CA$15.62 against a last close of CA$11.60, which puts the focus squarely on whether its growth pipeline and risk profile justify that gap.
Completion and ramp-up of the Kamoa-Kakula smelter (targeted for September) and the associated drop in logistics costs are expected to meaningfully reduce unit costs, directly boosting future operating margins and cash flow.
Ongoing capacity expansions at Kamoa-Kakula (Phases 1-3) and de-bottlenecking at Kipushi, alongside operational recovery from the recent seismic event, are projected to drive substantial increases in copper and zinc output, supporting strong top-line revenue growth in the next 12 to 24 months as production returns to full scale.
See why 28 investors see Ivanhoe Mines as 26% undervalued.
Result: Fair Value of CA$15.62 (UNDERVALUED)
Still, the bullish Ivanhoe Mines narrative relies heavily on smooth project execution, while seismic disruption risks and high capital spending could quickly challenge those upbeat assumptions.
Find out about the key risks to this Ivanhoe Mines narrative.
Another View: Ivanhoe Mines Looks Expensive On Earnings
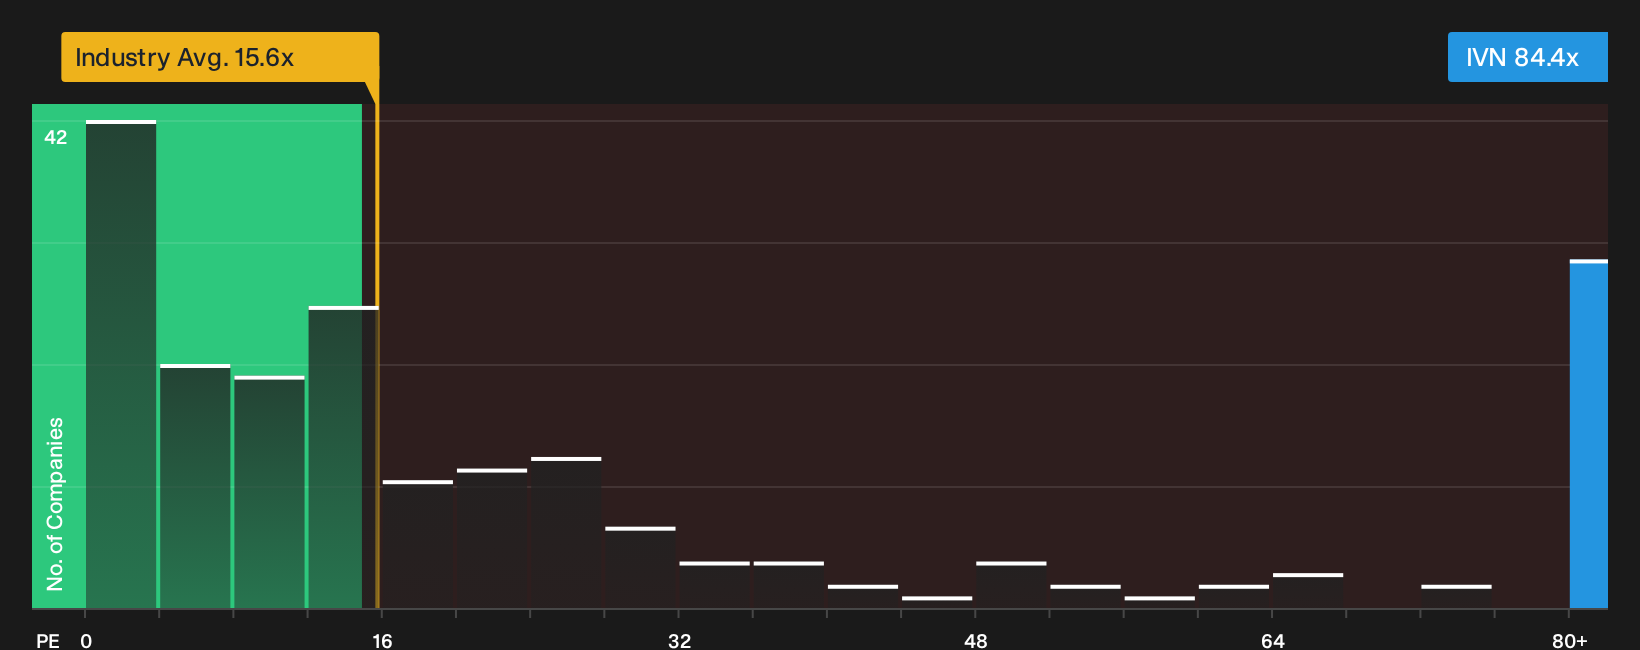
That fair value of CA$15.62 paints Ivanhoe Mines as undervalued, yet the earnings multiple tells a tougher story. The stock trades on a P/E of 84.4x, compared with 15.6x for the Canadian Metals and Mining industry, 17.5x for peers, and a fair ratio of 28x that the market could move toward over time. If sentiment shifts toward that lower level, today’s pricing could carry more valuation risk than the headline discount suggests. Which signal do you trust more?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ivanhoe Mines can feel messy, so use that tension as a prompt to review the data yourself and decide quickly where you stand. To weigh both sides in one place, start with the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Ivanhoe Mines?
If Ivanhoe Mines has your attention, do not stop there. Broaden your watchlist with other ideas that might fit your goals just as well.
- Target dependable income by scanning for yield opportunities in our 3 dividend fortresses that already clear a 5% hurdle.
- Hunt for potential bargains using the 8 high quality undervalued stocks that blend solid cash flows with balance sheets built to handle shocks.
- Spot tomorrow’s potential standouts early by filtering for strong fundamentals in the 9 high quality undiscovered gems before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com