
Why Fifth Third Bancorp (FITB) Is Back In The Spotlight
Fifth Third Bancorp (FITB) just reshaped its leadership bench, formally putting executive vice president Darren King in charge of an expanded Commercial Bank that now folds in the Regional Banking operation he already oversees.
The leadership change comes at a time when Fifth Third Bancorp’s share price has eased. The 30-day share price return is down 7.46% and the 90-day share price return is down 11.44%. In contrast, the 1-year total shareholder return of 26.18% and the 3-year total shareholder return above 7x indicate that longer term momentum has been strong, while investors have recently been rethinking near term risk and income trade offs as the dividend profile evolves.
Spot opportunities across regional lenders reshaping their leadership and income profiles by scanning our handpicked 8 dividend fortresses, aligned with moves like Fifth Third Bancorp’s expanded Commercial Bank appointment.That leadership reshuffle at Fifth Third Bancorp could be read as management leaning into a growing commercial engine while the share price reflects cooler short term sentiment. Which side of that split does current valuation reward?
Most Popular Narrative: 20% Undervalued
On the most followed view of Fifth Third Bancorp, a fair value estimate of $62.90 sits well above the recent $50.64 close. This comparison puts the recent share price pullback next to a model that still prices in stronger earnings power over time.
Expansion and densification in fast growing Southeast and Southwest markets is being extended through the Comerica footprint and an accelerated de novo program, with the recent outperformance of de novo deposit goals and sizeable Southwest consumer deposit inflows supporting potential future revenue and market share growth.
See why 23 investors see Fifth Third Bancorp as 19% undervalued.
Result: Fair Value of $62.90 (UNDERVALUED)
Still, the bullish Fifth Third Bancorp story runs into trouble if Comerica integration problems linger or if rising deposit costs squeeze the benefit of its funding base.
Find out about the key risks to this Fifth Third Bancorp narrative.
Another View: Fifth Third Bancorp Through The P/E Lens
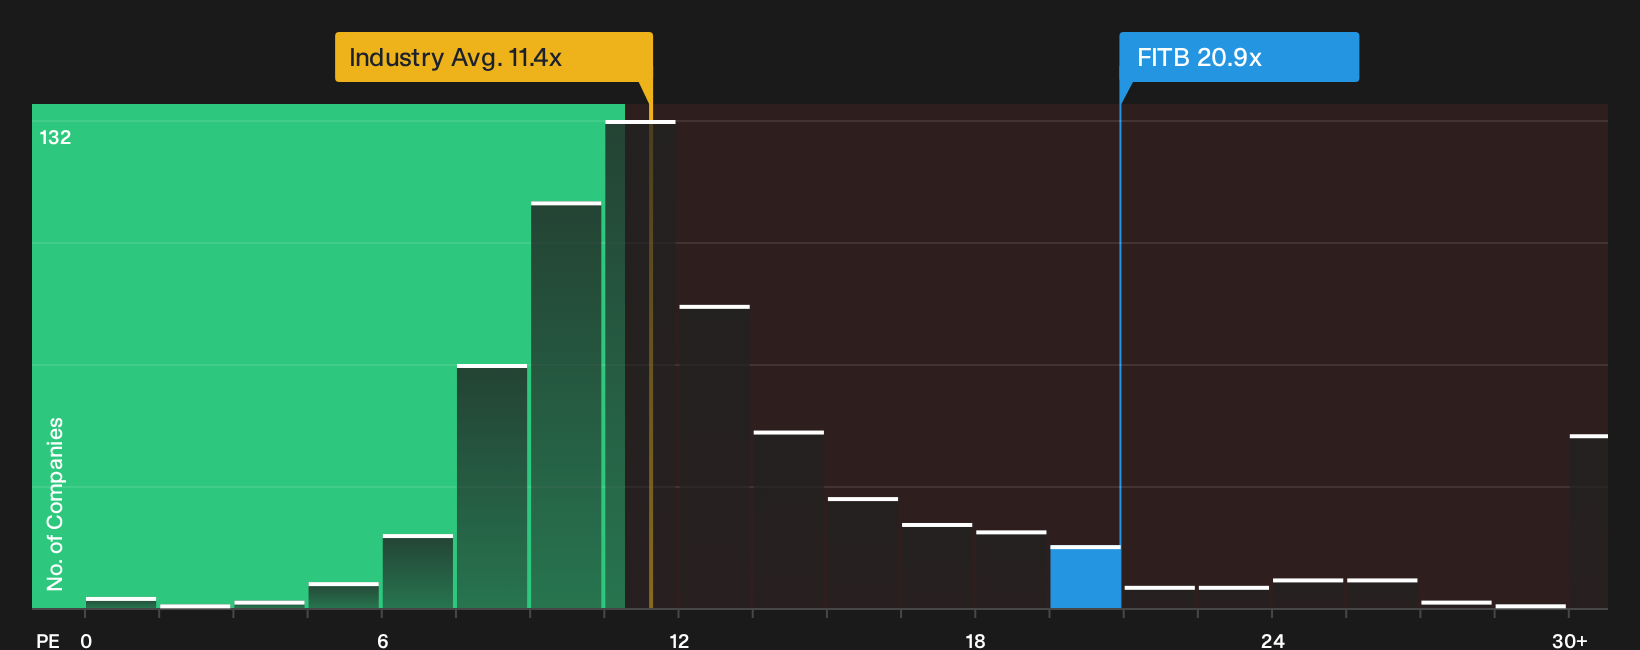
The DCF based fair value of $62.90 paints Fifth Third Bancorp as undervalued. The P/E picture is very different. At 20.9x earnings versus 11.4x for the US Banks industry, 12.2x for peers and a fair ratio of 17x, the stock carries a valuation premium that raises the question of how much execution risk investors are really being paid for.
See what the numbers say about this price in more detail in our valuation breakdown, then decide which story feels more convincing for your own framework. See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how Fifth Third Bancorp’s valuation stacks up against the wider banking group, review the comparative ratio chart here.
Next Steps
Mixed messages surround the Fifth Third Bancorp story so far. Act while sentiment remains divided and pressure test the data yourself with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Fifth Third Bancorp?
If Fifth Third Bancorp has sharpened your focus on pricing, risk and income, do not stop here. Broaden your watchlist and test fresh angles using targeted screeners.
- Chase potential mispricings by scanning a focused set of attractively valued companies through the 29 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with strong financial footing using the list of solid balance sheet and fundamentals (25 results).
- Hunt for emerging opportunities before the crowd by reviewing the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com