
Appian (APPN) Could Be 24% Undervalued After Investor Summit Spotlight
Appian (APPN) steps into the spotlight as Founder and CEO Matthew W. Calkins addresses investors at the American Growth Summit in Washington, DC, prompting fresh attention on the stock’s recent performance.
Recent trading reflects that renewed interest. The 1 day share price return of 3.7% and 7 day gain of 9.3% feed into a 90 day share price return of 53.9%. In contrast, the 1 year total shareholder return of 40.7% compares with a 5 year total shareholder return that is down 56.4%, suggesting near term momentum has improved even as longer term holders remain under water.
Scan how Appian’s conference buzz compares with other software plays showing strong price action and business quality in our hand picked 20 high quality undiscovered gems list.
Appian’s sharp rebound has shifted sentiment fast, yet the stock still trades at a discount to one estimate of intrinsic value, while longer term holders sit on deep losses. Does that setup still reward fresh risk?
Most Popular Narrative: 18% Overvalued
Analysts who follow Appian closely see fair value at $34, which sits below the last close at $40.10. As a result, the prevailing narrative frames the recent rally as stretching beyond that estimate while still hinged on AI driven automation tailwinds.
Broad enterprise demand for application modernization and workflow automation is accelerating, with AI seen as a catalyst that dramatically lowers modernization costs and complexity, positioning Appian's platform for increased adoption, larger deal sizes, and improved revenue growth over the coming years.
See why 17 investors see Appian as 18% overvalued.
Result: Fair Value of $34 (OVERVALUED)
Still, analyst assumptions face real tests if generative AI sidelines low code platforms or if heavy spending does not translate into durable profitability at Appian.
Find out about the key risks to this Appian narrative.
Another View: Appian’s Market Price Versus Cash Flow Value
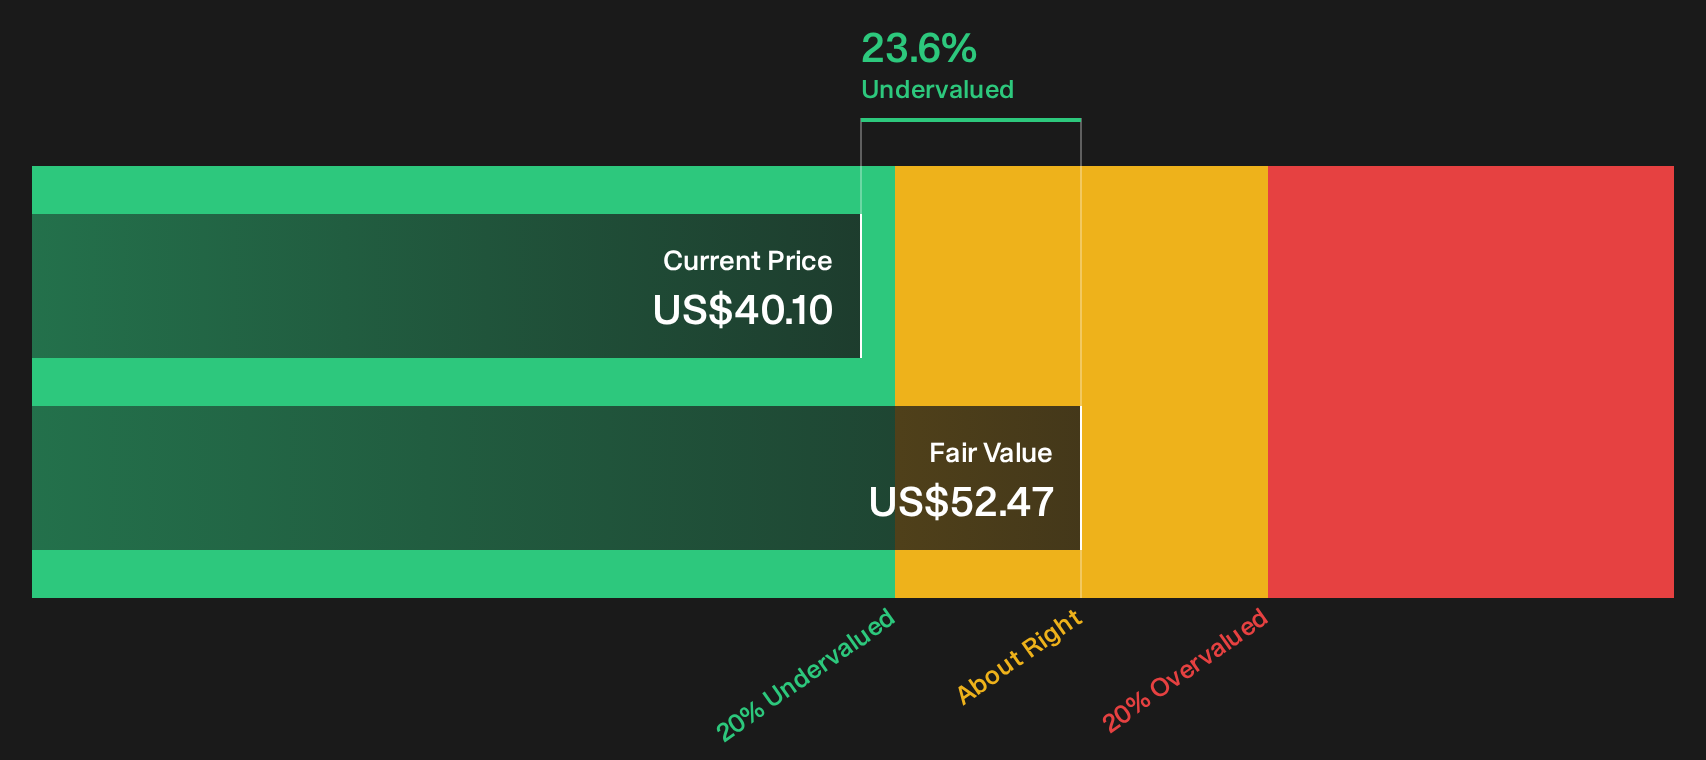
Analysts see Appian as 18% overvalued at $40.10 compared with a $34 fair value estimate, yet Simply Wall St’s DCF model points the other way. On that cash flow view, the share price sits about 23.6% below an assessed value of $52.47. Which story do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Appian is split right now. This is exactly when it helps to move fast, study the data yourself, and decide how much those 4 key rewards and 2 important warning signs matter to your own thesis through 4 key rewards and 2 important warning signs.
Looking for more Appian sized investment ideas?
Do not stop your research at Appian. Use Simply Wall Street's tools to hunt for other well supported opportunities before the crowd pays attention.
- Target potential mispricings by scanning a curated pool of quality businesses on the 29 high quality undervalued stocks.
- Shield your capital from shocks by filtering for sturdier balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Capture steady income opportunities by tracking companies that feature in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com