
Is Yoshinoya Holdings (TSE:9861) Expensive After Its Interim Dividend Board Meeting?
Why Yoshinoya Holdings’ latest board meeting matters for investors
Yoshinoya Holdings (TSE:9861) has called a board meeting for 8 October 2026 to decide on an interim dividend from retained earnings and to consider revising the interim payout planned for August 2027.
This kind of agenda puts shareholder returns at the center of the discussion. Management is effectively signalling how it wants to balance cash distributions against reinvestment across its beef bowl, noodle, ramen, and specialty restaurant businesses.
For you as a shareholder or prospective investor, any shift in interim dividends can influence the appeal of Yoshinoya Holdings as an income source and can also reset expectations around how predictable its future distributions might be.
Yoshinoya Holdings’ latest move on interim dividends comes after a strong run in the share price, with a 1-day share price return of 5.42% and a year-to-date share price return of 27.67% on a ¥3,950 close. Total shareholder return of 24.42% over the past year and 78.79% over five years reflects momentum that has built over time. Any shift in the payout policy can therefore quickly influence how investors weigh income against the potential for further capital appreciation.
Scan other consumer-focused stocks that pair income potential with business quality using our curated 28 dividend fortresses as a comparison set to Yoshinoya Holdings.
Bulls argue Yoshinoya Holdings’ dividend rethink confirms a confident, cash generative chain. Bears see a hot stock, a 27.67% year to date run, and limited upside. Which story does the current valuation support?
Price-to-Earnings of 43.4x: Is it justified?
On valuation, Yoshinoya Holdings trades on a P/E of 43.4x, which is being applied to a ¥3,950 share price after a strong run, so you are paying a full price for each yen of earnings compared with many listed Japanese restaurants.
The P/E ratio compares the current share price with earnings per share and, for a consumer services group like Yoshinoya Holdings, it effectively shows how much investors are willing to pay for its established beef bowl and noodle chain profits.
This is not a low figure. Relative to the JP Hospitality industry average P/E of 22x, the stock is valued far more expensively, and even compared with an estimated fair P/E of 21.8x there is a large premium that the market may not maintain if sentiment cools.
When lined up against peers measured on the same basis, Yoshinoya Holdings does have a lower P/E than the peer average of 58.2x, although the gap to both the industry benchmark and the fair P/E level suggests investors are pricing the shares aggressively rather than conservatively.
Explore the SWS fair ratio for Yoshinoya Holdings.
Result: Price-to-Earnings of 43.4x (OVERVALUED)
Still, Yoshinoya Holdings’ rich 43.4x P/E and any disappointment around that October 2026 dividend decision could both flip sentiment more quickly than recent returns suggest.
Find out about the key risks to this Yoshinoya Holdings narrative.
Another view on Yoshinoya Holdings’ valuation
The SWS DCF model points in the same direction as the P/E check. At ¥3,950, Yoshinoya Holdings trades above an estimated future cash flow value of ¥3,699.14, so the stock screens as overvalued on both earnings and cash flow. The question is how much optimism you are willing to pay for.
Look into how the SWS DCF model arrives at its fair value.
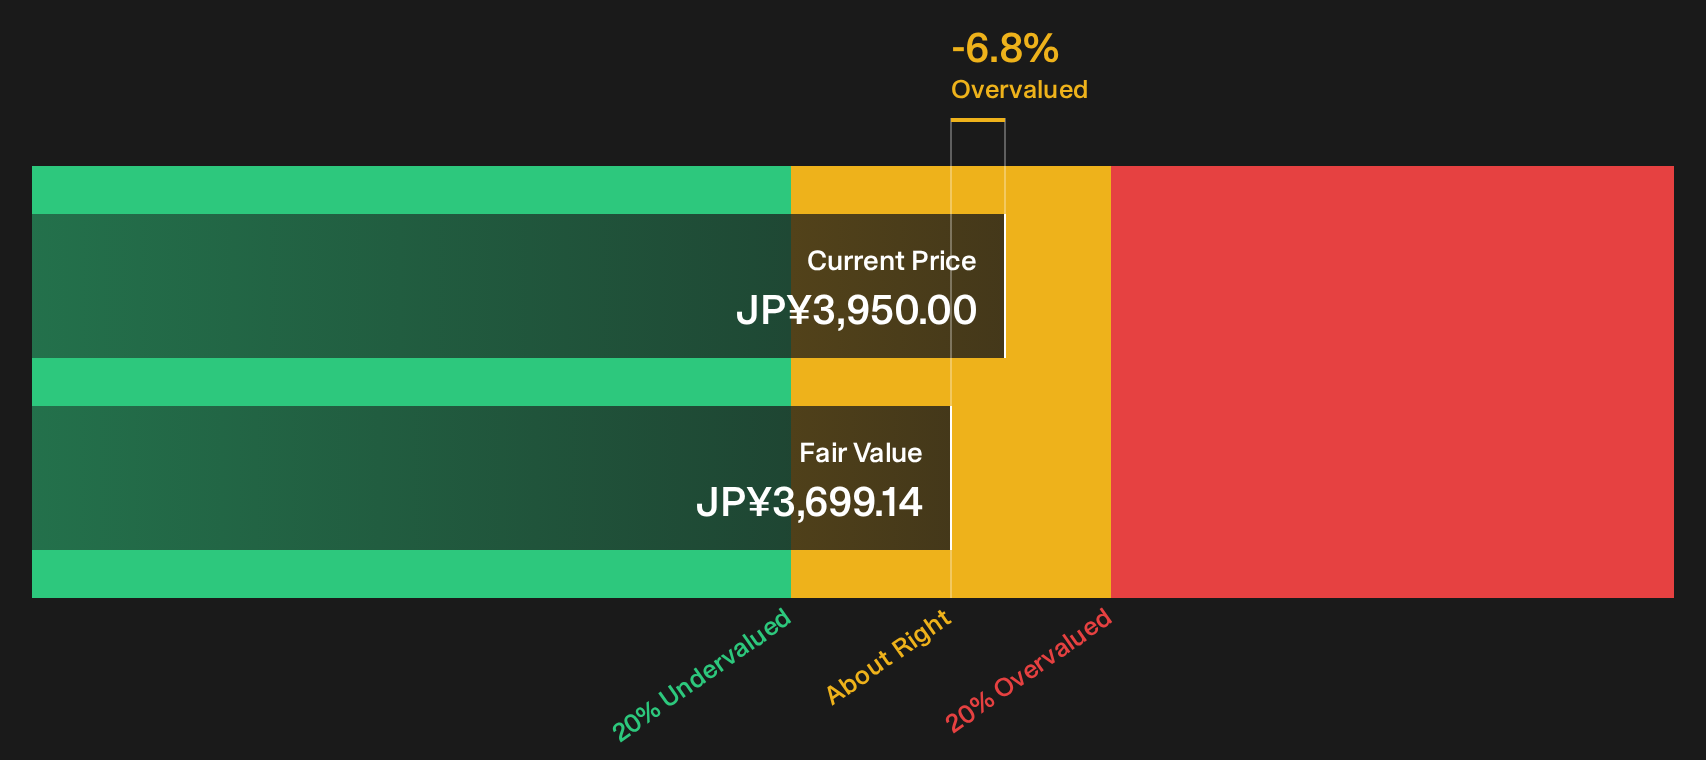
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yoshinoya Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the premium valuation on Yoshinoya Holdings and the dividend story taking shape is reasonable. Take a close look at the underlying factors that support that optimism and form your own stance while sentiment is still fresh. To see what the data flags as potential positives, review the 2 key rewards
Looking for more investment ideas beyond Yoshinoya Holdings?
If Yoshinoya Holdings has sharpened your focus on quality and income, now is the moment to widen your watchlist before the next set of opportunities moves away.
- Target resilient candidates with room for upside by scanning our 13 high quality undervalued stocks, which combines quality fundamentals with appealing prices.
- Prioritise financial strength first by reviewing a list of solid balance sheet and fundamentals (22 results), which can help support dividends and reinvestment through different business conditions.
- Get ahead of the crowd by checking a 74 high quality undiscovered gems, which pairs robust fundamentals with limited existing market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com