
DiamondRock Hospitality (DRH) Stock May Trade Below Fair Value After Resort Acquisition
DiamondRock Hospitality has delivered a strong share price run in recent years, which puts fresh attention on whether the current valuation is adequately supported by its earnings profile. With that backdrop, the key issue for investors is how the business's profits line up against what the market is now willing to pay.
- Over the past 3 years, DiamondRock Hospitality has returned 77.3%. This makes the link between its earnings power and current share price especially important to understand.
- The recent US$31 million purchase of The Bellmoor Inn & Spa adds another income-producing asset that can influence future earnings levels and the timing of cash flows used in valuation work.
- There is a second opinion on DiamondRock Hospitality worth weighing. See what analysts think DiamondRock Hospitality's shares could be worth.
The issue now is whether DiamondRock Hospitality's recent share price around US$12.62 is appropriately explained by what the business is generating in earnings today.
To sanity check DiamondRock Hospitality against other opportunities with an earnings and valuation angle, it can help to compare it with 29 high quality undervalued stocks.
Is DiamondRock Hospitality a Bargain on Earnings?
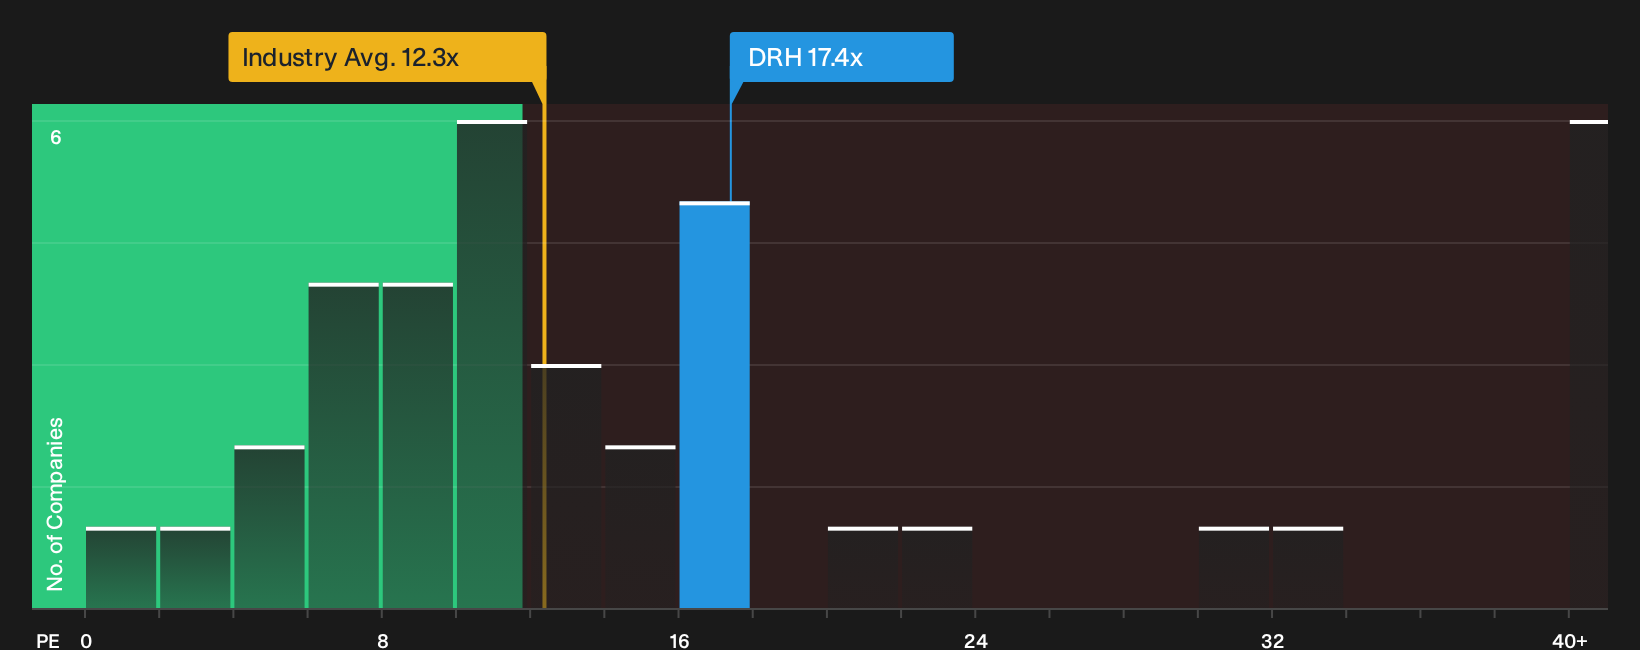
The P/E ratio suits DiamondRock Hospitality because earnings are a key reference point for many hotel and resort REIT investors. On this measure, the stock trades at about 17.4x earnings, which is above the Hotel and Resort REITs sector average of roughly 12.3x and below the peer group closer to 66.5x. That places the shares at a premium to the broader industry but not at the higher extremes seen across some listed rivals.
The fair-value framework, which blends factors like growth outlook, profitability profile, risk and size for DiamondRock Hospitality, points to a higher P/E than where the stock trades today. On this model, the current multiple screens as undervalued. Because the recent US$31 million acquisition of The Bellmoor Inn & Spa adds another earning asset, the market is effectively pricing that new property and the existing portfolio at a discount to what this tailored benchmark suggests. Explore the numbers behind DiamondRock Hospitality's P/E valuation.
The DiamondRock Hospitality Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/E puzzle for DiamondRock Hospitality leaves off, by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today. Rather than relying on a single multiple or model output, each narrative lays out the key drivers behind its view of fair value so you can compare those assumptions with DiamondRock Hospitality's actual results over time.
Community views on DiamondRock Hospitality split between investors who see more upside left in the story and those who think expectations already feel full.
Bull case: 10% undervalued
"Repositioning and renovation projects most notably the integration of the Cliffs at L'Auberge in Sedona and ongoing asset recycling are expected to yield stabilized double-digit cash returns and drive 25 to 50 basis points of portfolio RevPAR growth in 2026…"
Discover why this Narrative puts DiamondRock Hospitality at 10% undervalued.
Bear case: 9% overvalued
"The recent sale of the Courtyard by Marriott New York Manhattan/Fifth Avenue at a price that did not meet investment thresholds highlights the risk that similar assets could also prove uneconomic after required CapEx…"
Explore why this Narrative puts DiamondRock Hospitality at 9% overvalued.
The share price is only one piece of the DiamondRock Hospitality puzzle
Before treating DiamondRock Hospitality as purely a valuation story, it helps to know that separate checks have highlighted specific risks that could influence the investment case. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com