
3 US Mortgage Stocks Facing Higher For Longer Rates
Interest rates are climbing again, and the Fed is signaling that borrowing costs could stay higher for longer, which puts rate sensitive housing and mortgage stocks directly in the spotlight. That shift can hurt some corners of the market while opening unexpected doors for others. This article unpacks the story and then walks through 3 stocks from our US Rate-Sensitive Housing and Mortgage Equities screener that appear especially exposed to the latest Fed signals.
The three stocks below are just a starting sample. The full screen surfaced 24 more U.S. housing and mortgage related companies with equally compelling narratives that are not covered here.
Head straight into the US Rate-Sensitive Housing and Mortgage Equities screener to identify, analyze, and prioritize your own highest conviction rate sensitive housing and mortgage ideas.
UWM Holdings (UWMC)
UWM Holdings is one of the purest plays on US mortgage origination in this screener. Its wholesale broker model ties revenue directly to how rate moves and housing affordability shape loan demand and servicing income.
Continued investment and successful deployment of advanced AI tools such as Mia, Bolt and ChatUWM are now evidenced by hundreds of thousands of automated borrower contacts and tens of thousands of closed loans, which supports the view that UWM Holdings can push higher origination volumes through largely fixed expense levels and lift both revenue and operating margins.
What happens to those margin targets if a single key cost lever does not shift as management plans?
UWM Holdings focuses on originating, selling, and servicing US residential mortgages through its wholesale broker channel, generating US$2.9b from residential mortgage loans and carrying a market value of about US$1.7b.
If that cost lever is the real swing factor, the full narrative for UWM Holdings shows where UWM Holdings could still accelerate or stall as rates bite.

TPG Mortgage Investment Trust (MITT)
TPG Mortgage Investment Trust sits squarely in the rate sensitive housing trade, with its residential mortgage focus meaning every move in borrowing costs and mortgage spreads can ripple through earnings, book value, and ultimately the income it aims to return to investors.
TPG Mortgage Investment Trust runs a residential focused mortgage REIT portfolio in the US, with US$90 million of revenue from loans and securities and a smaller loss in other income, and carries a market value of about US$179 million.
Rotation of TPG Mortgage Investment Trust capital out of legacy commercial retail and hospitality loans into residential credit and home equity is expected to redirect roughly US$30 million into higher yielding core assets and support higher earnings available for distribution and dividend coverage.
The real question is what happens if a single pressure point in its funding mix shifts at the wrong moment for spreads and payout ambitions.
That funding swing factor is exactly what the full narrative for TPG Mortgage Investment Trust unpacks, revealing how TPG Mortgage Investment Trust could either accelerate distributions or see them quietly stalled.

Orchid Island Capital (ORC)
Orchid Island Capital is connected to the rate sensitive housing and mortgage theme as a US mortgage REIT that earns US$270 million from residential mortgage backed securities, all in the United States, with a market value of about US$1 billion.
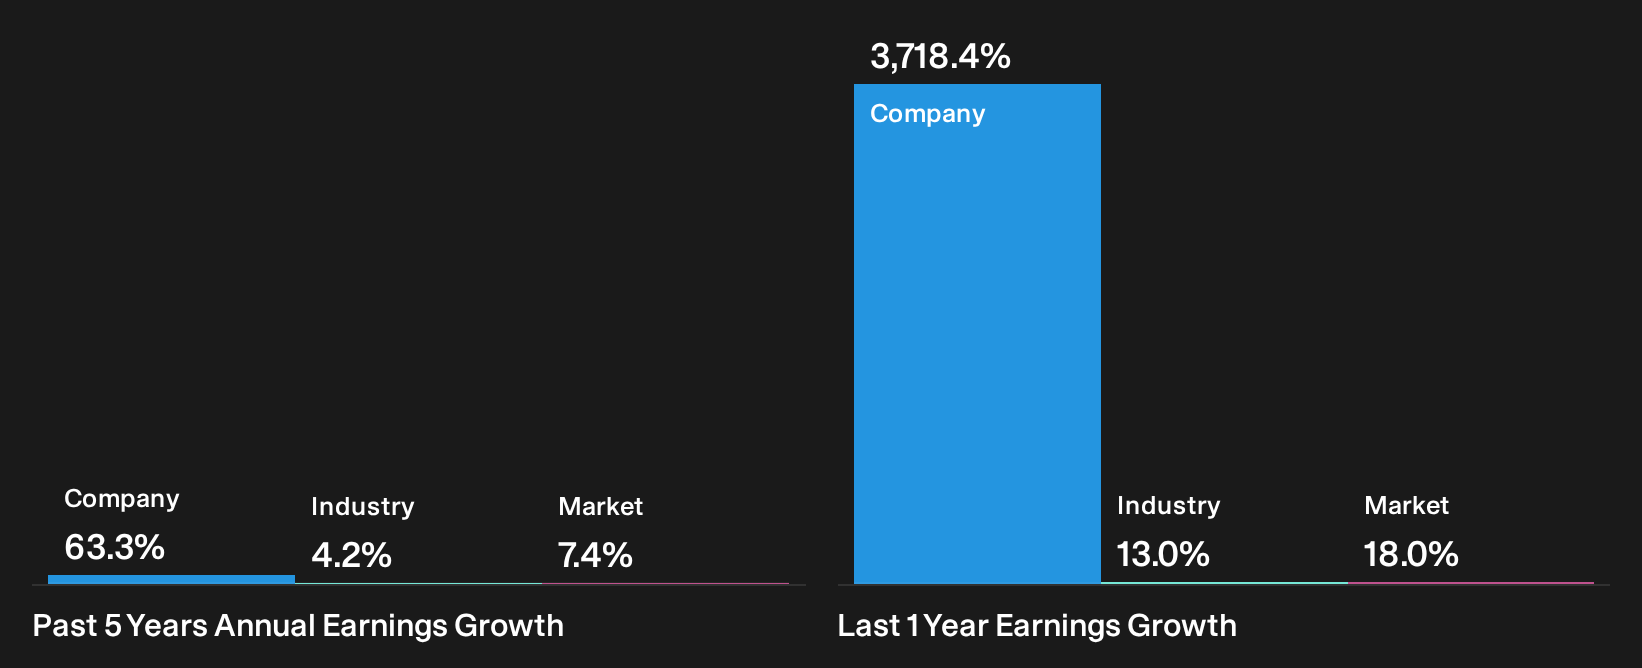
Orchid Island Capital provides exposure to how US mortgage rates and prepayment trends affect residential mortgage backed securities. The stock trades on a P/E of 4.1x with recent profit margins described as very high and a double digit dividend yield. However, the outlook is closely tied to the potential impact of changes in funding cost pressures on spreads.
Those funding cost swings are exactly what the 4 key rewards and 3 important warning signs (3 are major!) could be masking for Orchid Island Capital investors who are watching spreads and payouts closely.
Curious About Alternative Stock Paths?
Fresh opportunities can move fast, and once momentum starts flying the best entry points can get caught and dropped quickly. Scan under the radar ideas before the crowd and act now.
- Target reliable income streams while rates shift and assess a curated mix of high-yield candidates in the 8 dividend fortresses.
- Hunt for future compounders early and sift through a hand picked 20 high quality undiscovered gems before their stories go mainstream.
- Position ahead of major infrastructure upgrades and evaluate potential beneficiaries with the focused 43 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com