
Sands China (SEHK:1928) Moved Today, What Is Behind The Attention?
Sands China (SEHK:1928) is testing embodied AI on the casino floor, after receiving its first batch of Tutu robot dogs from Alibaba’s Amap to guide visitors through its Macau resorts and indoor navigation system.
The Amap partnership and rollout of Tutu comes as Sands China’s share price has been under pressure for some time, with the latest HK$11.46 level following a recent 1-day share price gain of about 4% but a 30-day share price return that declined roughly 14%, and a 1-year total shareholder return that fell close to 39%. This suggests that recent excitement around embodied AI is arriving against a backdrop of weaker longer term performance and an ongoing debate about what investors are willing to pay for the business.
Scan how embodied AI stories like Sands China compare with other hospitality and tech-driven plays using the hand picked 92 AI infrastructure stocks in the current market context.
Sands China is rolling out robot guides and posting rising annual revenue and net income. Yet the share price has fallen hard over 1 and 3 years. Is this still a strong business that is simply mispriced?
Preferred P/E of 13.4x: Is it justified for Sands China?
The market is currently valuing Sands China at a P/E of 13.4x, a level that sits slightly above both its estimated fair P/E of 13.3x and the Hong Kong hospitality sector at 13.1x, even as the share price has fallen sharply over 1 and 3 years.
P/E simply compares what investors are paying for each dollar of earnings to what the business is currently generating. For a casino and resort operator with HK$8,830 million in net income and a portfolio of large-scale Macau properties, that ratio gives you a quick sense of how much future profit strength is already reflected in the HK$11.46 share price.
The current P/E shows that the market is not treating Sands China as a clear bargain on earnings compared with hospitality peers on 13.1x. It is also close to the estimated fair P/E of 13.3x, which suggests only a very small gap between where the market is and where the fair ratio model suggests pricing could settle if sentiment and fundamentals move into line over time.
Compared with both the Hong Kong hospitality industry average and the estimated fair P/E, the stock trades on a slightly richer multiple. This indicates that investors are paying a bit more than those benchmarks for each dollar of profit today.
Explore the SWS fair ratio for Sands China.
Result: Price-to-earnings of 13.4x (ABOUT RIGHT)
Still, Sands China faces the risk that embodied AI fails to lift visitor spend meaningfully, while weaker multi year share returns keep pressure on investor confidence.
Find out about the key risks to this Sands China narrative.
Another View on Sands China’s Value
The earnings multiple paints Sands China as roughly fairly priced, yet the SWS DCF model points a different way. On that view, the stock at HK$11.46 trades well below an estimated future cash flow value of HK$20.69, which implies a wide gap that investors need to interpret carefully.
If cash flows are the anchor that matters most to you, this raises a simple question. Is the current price a warning about risk, or an opening created by weak sentiment while Macau assets and embodied AI experiments slowly play out in the background?
Look into how the SWS DCF model arrives at its fair value.
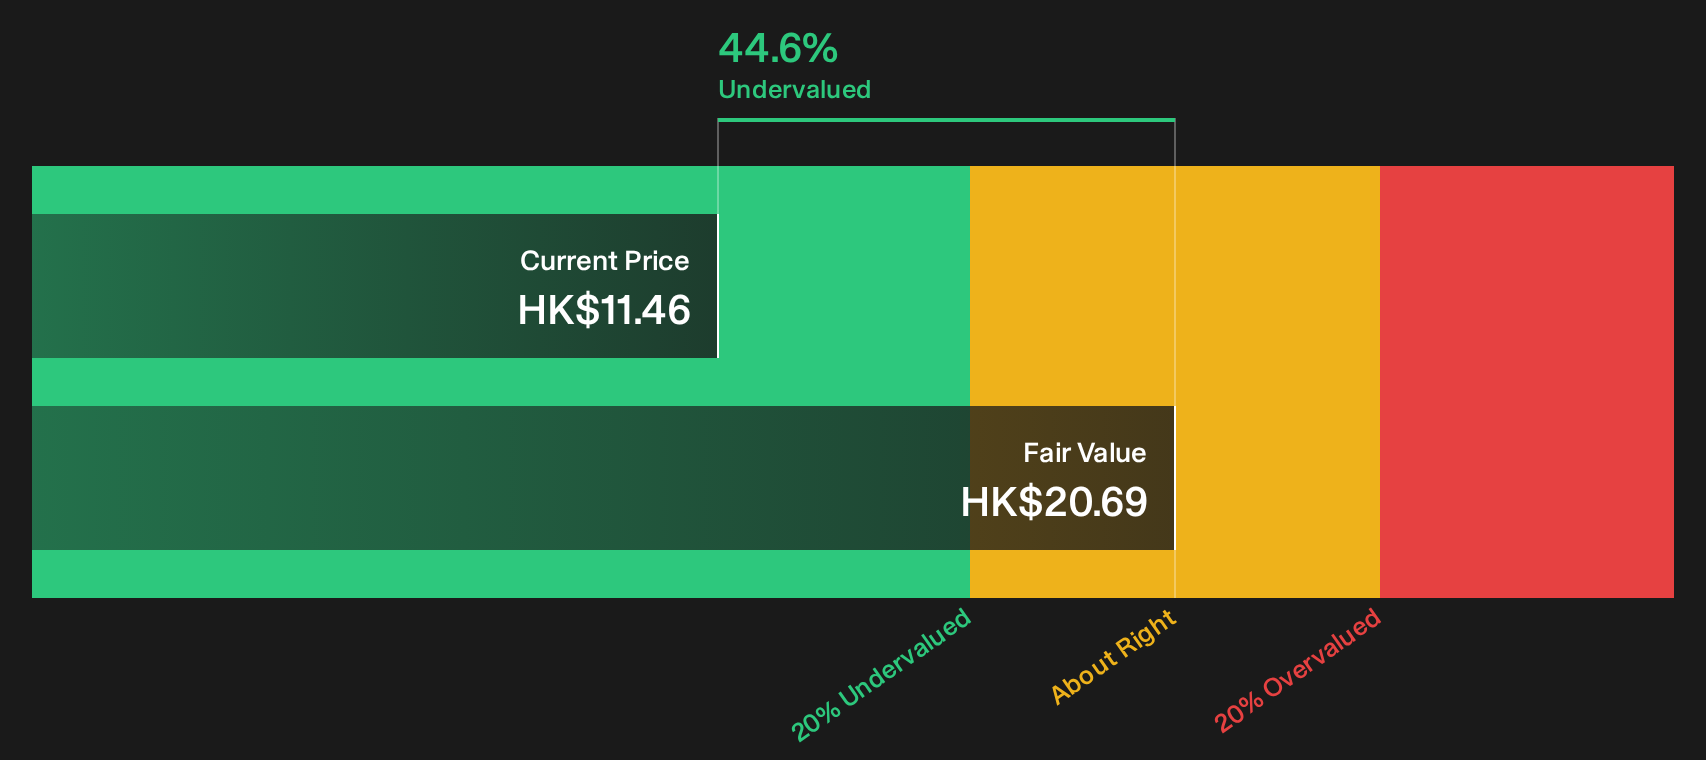
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sands China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sands China is mixed, so consider testing the numbers yourself, weighing the concerns against the potential, and reviewing the full picture in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sands China?
If Sands China has you thinking harder about price, quality, and risk, then broadening your watchlist with a few focused stock ideas can help you refine your next move.
- Target potential mispricings by reviewing a hand picked 179 high quality undervalued stocks that pairs strong fundamentals with what could be appealing entry points.
- Strengthen your income plan by scanning a curated 221 dividend fortresses that can help you compare yield with balance sheet support.
- Dial back downside risk by filtering through a focused 223 resilient stocks with low risk scores that highlights businesses with more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com