
Could New Power Partnerships Change The Bull Case For Wärtsilä Stock?
- Wärtsilä and RCT Solutions have launched Valo as a dedicated global integrator for utility-scale battery energy storage, entering the market with more than 20 GWh across over 130 completed projects and a mandate to provide continuity and broader capability for existing customers.
- Alongside the Valo launch, Wärtsilä’s joint “Generator-to-Chip” model with Schneider Electric and Stanley Consultants targets power hungry U.S. data centers, signaling a push toward higher value integrated energy and digital infrastructure solutions rather than standalone equipment sales.
- We will now look at how Wärtsilä's investment narrative could shift as integrated energy storage capabilities move closer to data centers.
Scan how Wärtsilä Oyj Abp’s energy storage and data center push compares with other power infrastructure plays by checking our curated list of 43 power grid technology and infrastructure stocks today.
Wärtsilä Oyj Abp Investment Narrative Recap
To own Wärtsilä Oyj Abp, you need to believe the business can keep turning its marine and energy footprint into growing high quality earnings while gradually tilting toward cleaner power and digital services. The near term story still revolves around converting its order backlog into revenue and keeping margins around the current 9.6% level or higher.
The key near term catalyst is execution on energy and data center related orders without cost overruns or delays, especially as supply chains remain exposed to geopolitical risk. The biggest risk is that customers move faster toward pure renewables and next generation clean tech than Wärtsilä’s engine heavy portfolio adapts, which could cap new equipment demand.
The “Generator to Chip” model with Schneider Electric and Stanley Consultants looks tightly linked to those catalysts. It ties Wärtsilä’s flexible engine plants and storage capabilities to data center power architectures, where grid connection delays are a real pain point for developers across the United States.
If this approach converts into more complex, multi year data center power projects, it could support order intake and future service agreements, especially given Wärtsilä’s existing €6.9b revenue base. Execution risk is real though. These projects involve tight coordination across design, permitting and construction, so any stumble could limit the benefit from what is currently a high profile opportunity.
Wärtsilä Oyj Abp’s current analyst storyline points to €8.0 billion in revenue and €920.6 million in earnings by 2029, based on 5.1% yearly top line growth and an earnings increase of about €259.6 million from today’s €661.0 million base.
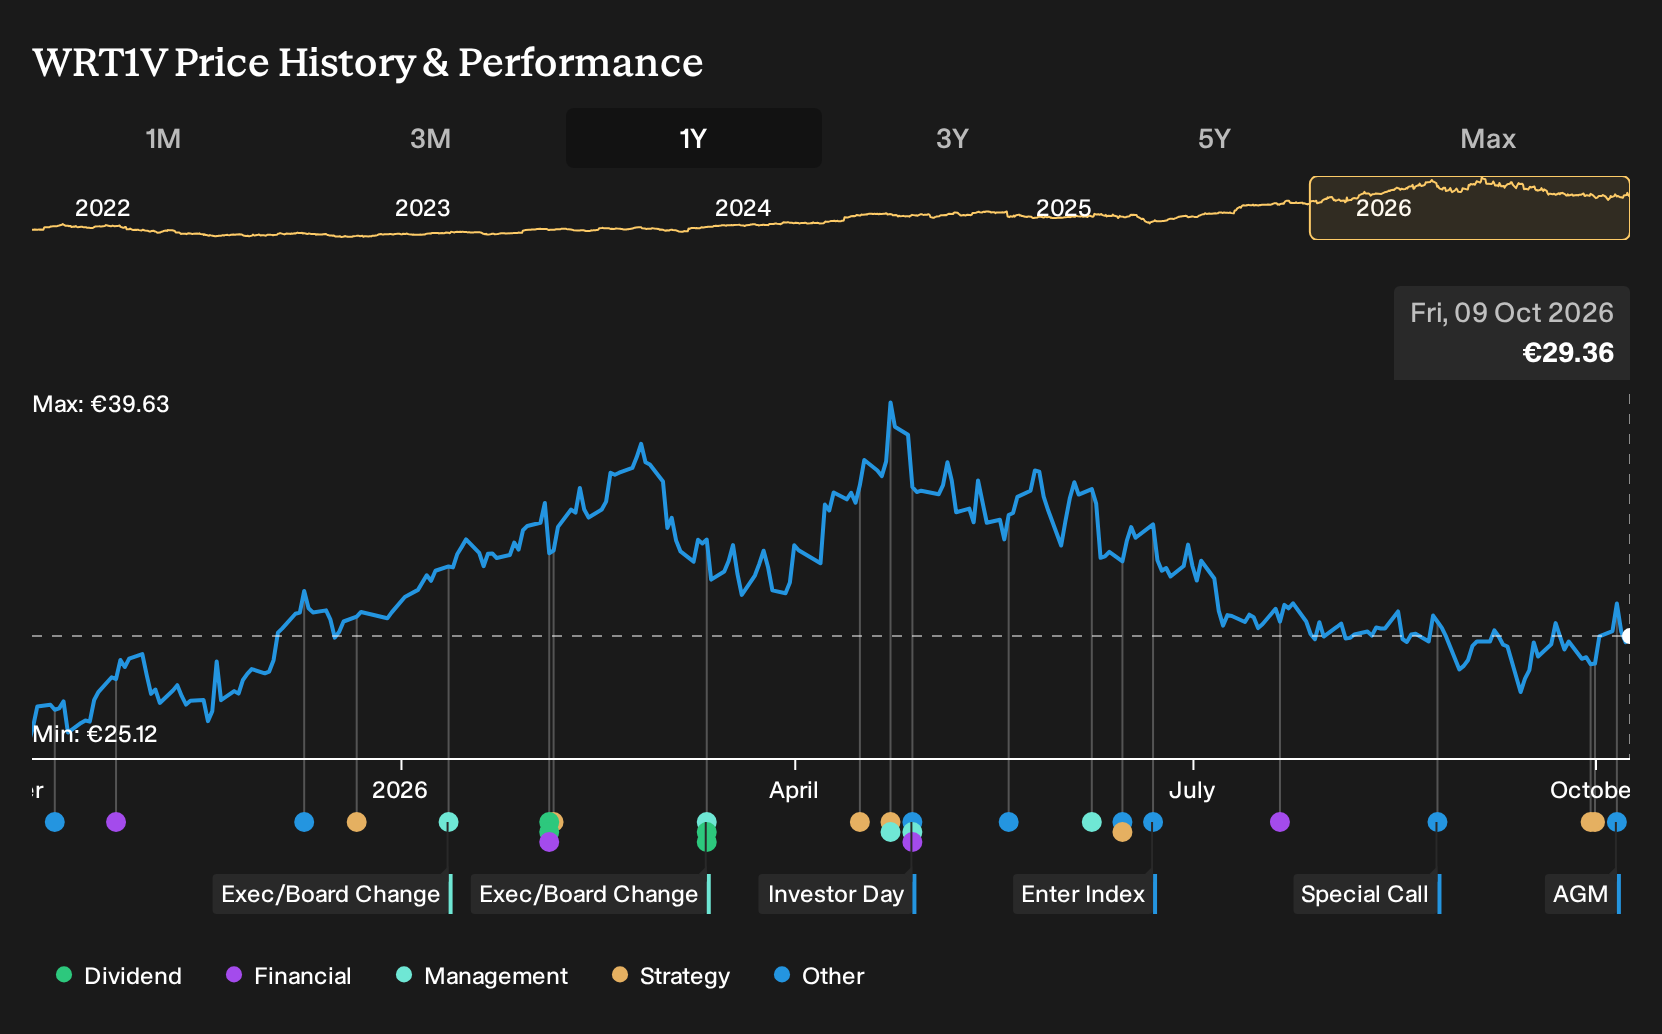
Uncover why Wärtsilä Oyj Abp's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view around Wärtsilä Oyj Abp is much more cautious on how quickly its record order book turns into earnings. The most bearish analysts were only pencilling in about €7.2b of revenue and €803.4m of earnings by 2029 before this Valo and Generator to Chip news, so they saw far less upside. That gap in expectations shows how widely opinions can differ, so it makes sense to explore those lower forecasts alongside the new storage and data center story.
Explore 4 other Wärtsilä Oyj Abp fair value estimates, including one that suggests as much as 28% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Wärtsilä Oyj Abp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Wärtsilä Oyj Abp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wärtsilä Oyj Abp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wärtsilä Oyj Abp?
If you want to pressure test your view on Wärtsilä Oyj Abp against other opportunities, the Simply Wall St Screener gives you a quick way to compare different business profiles side by side.
- If you care most about valuation upside with quality fundamentals, line up your options using our 179 high quality undervalued stocks.
- For investors who prefer sturdier balance sheets and fewer financial surprises, start with the list of solid balance sheet and fundamentals (202 results).
- When you want to hunt for smaller, under followed opportunities with strong underlying numbers, scan through the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com