
Global Insights Into 3 Stocks Possibly Priced Below Fair Value
In recent weeks, global markets have experienced mixed performances, with major U.S. indices showing modest gains amid volatility in AI-related stocks and fluctuating energy prices due to Middle East tensions. As investors navigate these uncertain times, identifying stocks that may be undervalued can offer potential opportunities for those looking to balance their portfolios against market fluctuations. In this context, a good stock is typically characterized by strong fundamentals and the potential for growth despite current economic challenges.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €26.62 | €52.96 | 49.7% |
| Nissui (TSE:1332) | ¥1085.00 | ¥2155.77 | 49.7% |
| Monde Nissin (PSE:MONDE) | ₱6.35 | ₱12.68 | 49.9% |
| Kumagai GumiLtd (TSE:1861) | ¥1196.00 | ¥2370.12 | 49.5% |
| Kona ILtd (KOSDAQ:A052400) | ₩34650.00 | ₩69061.19 | 49.8% |
| Innocean Worldwide (KOSE:A214320) | ₩18040.00 | ₩35756.40 | 49.5% |
| Chow Sang Sang Holdings International (SEHK:116) | HK$13.84 | HK$27.60 | 49.9% |
| Astellas Pharma (TSE:4503) | ¥2247.50 | ¥4494.42 | 50% |
| Apex Mining (PSE:APX) | ₱16.68 | ₱33.18 | 49.7% |
| APAC Realty (SGX:CLN) | SGD0.52 | SGD1.04 | 49.8% |
Let's uncover some gems from our specialized screener.
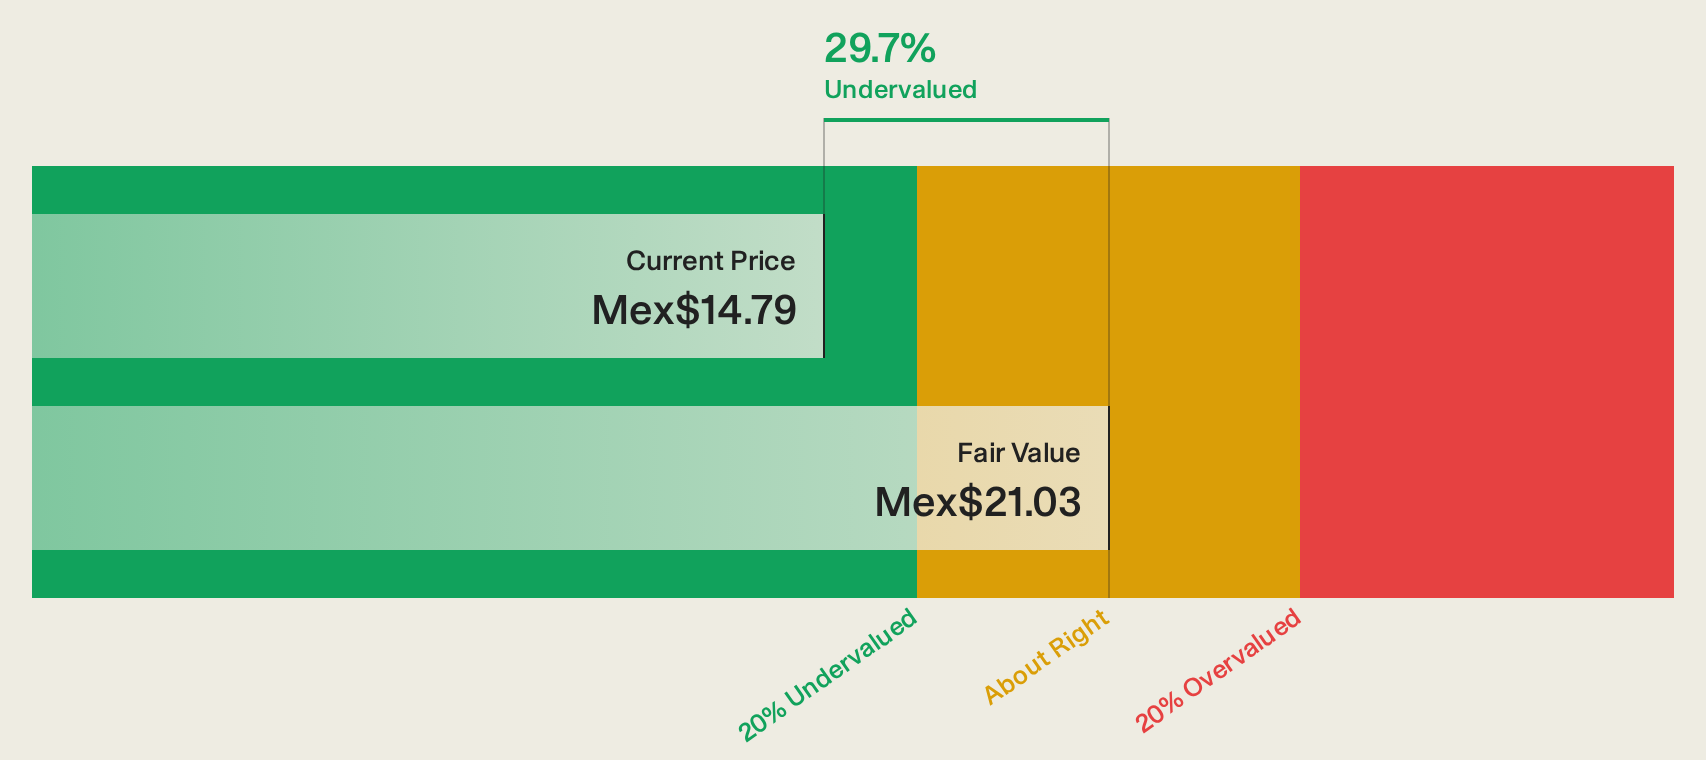
Becle. de (BMV:CUERVO *)
Overview: Becle, S.A.B. de C.V. is a company that manufactures and distributes spirits and other distilled beverages across Mexico, the United States, Canada, and internationally with a market cap of MX$50.64 billion.
Operations: The company's revenue from alcoholic beverages amounts to MX$39.27 billion.
Estimated Discount To Fair Value: 23.6%
Becle, S.A.B. de C.V. is trading at MX$14.1, below its estimated future cash flow value of MX$18.47, indicating it is undervalued based on discounted cash flows by over 20%. Despite earnings growing by 29.6% last year, revenue and net income have declined compared to the previous year. The company's forecasted revenue growth of 5.8% per year is slightly below the market average, while its return on equity remains low at a projected 7.2%.
- Upon reviewing our latest growth report, Becle. de's projected financial performance appears quite optimistic.
- Click here to discover the nuances of Becle. de with our detailed financial health report.
Nippon Signal (TSE:6741)
Overview: Nippon Signal Co., Ltd. and its subsidiaries specialize in developing railway signal systems technologies in Japan, with a market cap of ¥112.70 billion.
Operations: The company's revenue is primarily generated from two segments: ICT Solutions, contributing ¥56.64 billion, and Transportation Infrastructure, accounting for ¥62.92 billion.
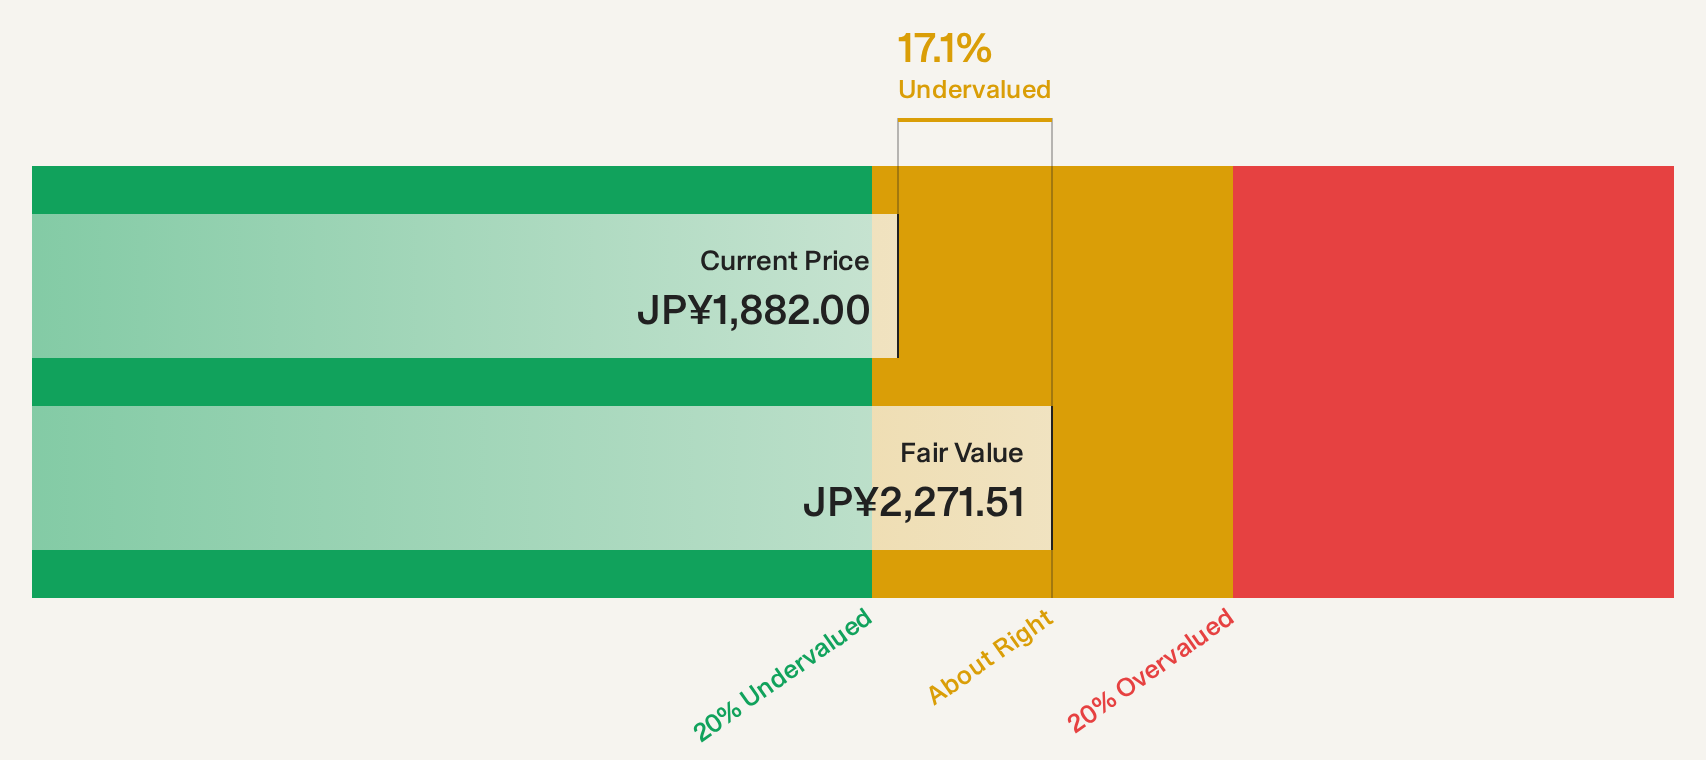
Estimated Discount To Fair Value: 20.1%
Nippon Signal is trading at ¥1,807, which is below its estimated future cash flow value of ¥2,261.02, highlighting it as undervalued by more than 20%. Recent earnings show significant improvement with sales reaching ¥23.55 billion and net income of ¥1.52 billion for Q1 2026 compared to a loss last year. However, earnings are forecasted to decline by an average of 2.6% annually over the next three years despite revenue growth projections outpacing the market slightly at 7% per year.
- Our comprehensive growth report raises the possibility that Nippon Signal is poised for substantial financial growth.
- Take a closer look at Nippon Signal's balance sheet health here in our report.
Aisan Industry (TSE:7283)
Overview: Aisan Industry Co., Ltd. manufactures and sells automotive parts both in Japan and internationally, with a market cap of ¥125.52 billion.
Operations: The company's revenue segments are comprised of ¥136.96 billion from Asia, ¥143.39 billion from Japan, ¥15.96 billion from Europe, and ¥80.04 billion from the Americas.
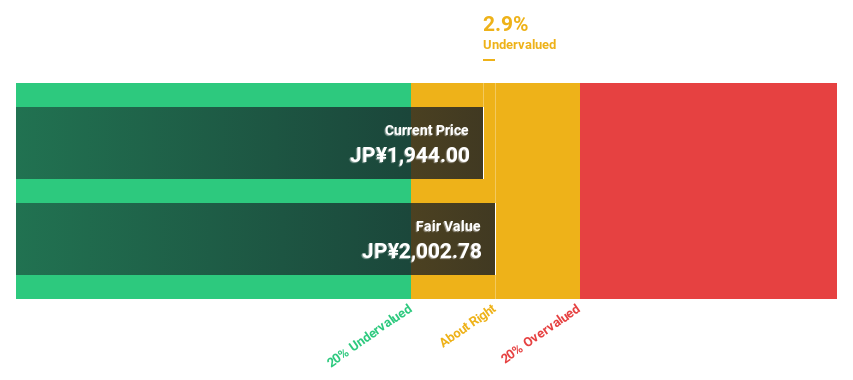
Estimated Discount To Fair Value: 41%
Aisan Industry, trading at ¥2,201, is significantly undervalued compared to its future cash flow value of ¥3,730.49. Despite forecasted earnings growth of 8.83% per year being below the market average and revenue growth trailing the market at 5.9%, recent corporate guidance revisions show improved financial expectations with net sales projected at ¥335 billion and operating profit increased to ¥19.5 billion for fiscal year ending March 2027. The dividend yield remains unsustainably high relative to free cash flows.
- In light of our recent growth report, it seems possible that Aisan Industry's financial performance will exceed current levels.
- Dive into the specifics of Aisan Industry here with our thorough financial health report.
Taking Advantage
- Delve into our full catalog of 257 Undervalued Global Stocks Based On Cash Flows here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com