
Chefs' Warehouse (CHEF) Draws Fresh DCF Attention, Is It Still A Bargain?
Why fresh DCF chatter has investors revisiting Chefs' Warehouse
Fresh discounted cash flow commentary has pushed Chefs' Warehouse (CHEF) back into focus, as investors weigh projected free cash flow and long term cash generation against the current share price.
Recent trading has been strong, with Chefs' Warehouse posting share price returns of 3.5% over 30 days and 15.7% over 90 days, while its year to date share price return of 83.23% and three year total shareholder return of almost 5x point to powerful momentum that fresh DCF analysis is now being used to justify or question.
Compare Chefs' Warehouse's DCF story with a curated set of other potential mispriced opportunities on our 29 high quality undervalued stocks, which also pair cash flow strength with solid balance sheets.
Bulls point to Chefs' Warehouse trading at a 38% discount to estimated intrinsic value, while bears see a hot stock after an 83.23% YTD run. Which story does the cash flow math support?
Most Popular Narrative: 6% Undervalued
Chefs' Warehouse currently trades at $114.32 against a most-followed narrative fair value of $122, so investors are weighing a modest implied upside against a stock that already reflects a strong run.
The numbers now imply that if Chefs' Warehouse delivers on the raised 2030 revenue and EBITDA goals and maintains free cash flow conversion and leverage within its stated ranges, the current share price already embeds a valuation that reflects a bullish view on the durability of this growth and cash generation profile.
See why 6 investors see Chefs' Warehouse as 6% undervalued.
Result: Fair Value of $122 (UNDERVALUED)
Still, Chefs' Warehouse depends heavily on premium foodservice demand, and persistent cost inflation or supply chain rerouting could compress margins and undercut the current DCF optimism.
Find out about the key risks to this Chefs' Warehouse narrative.
Another View: What Chefs' Warehouse's P/E Is Telling You
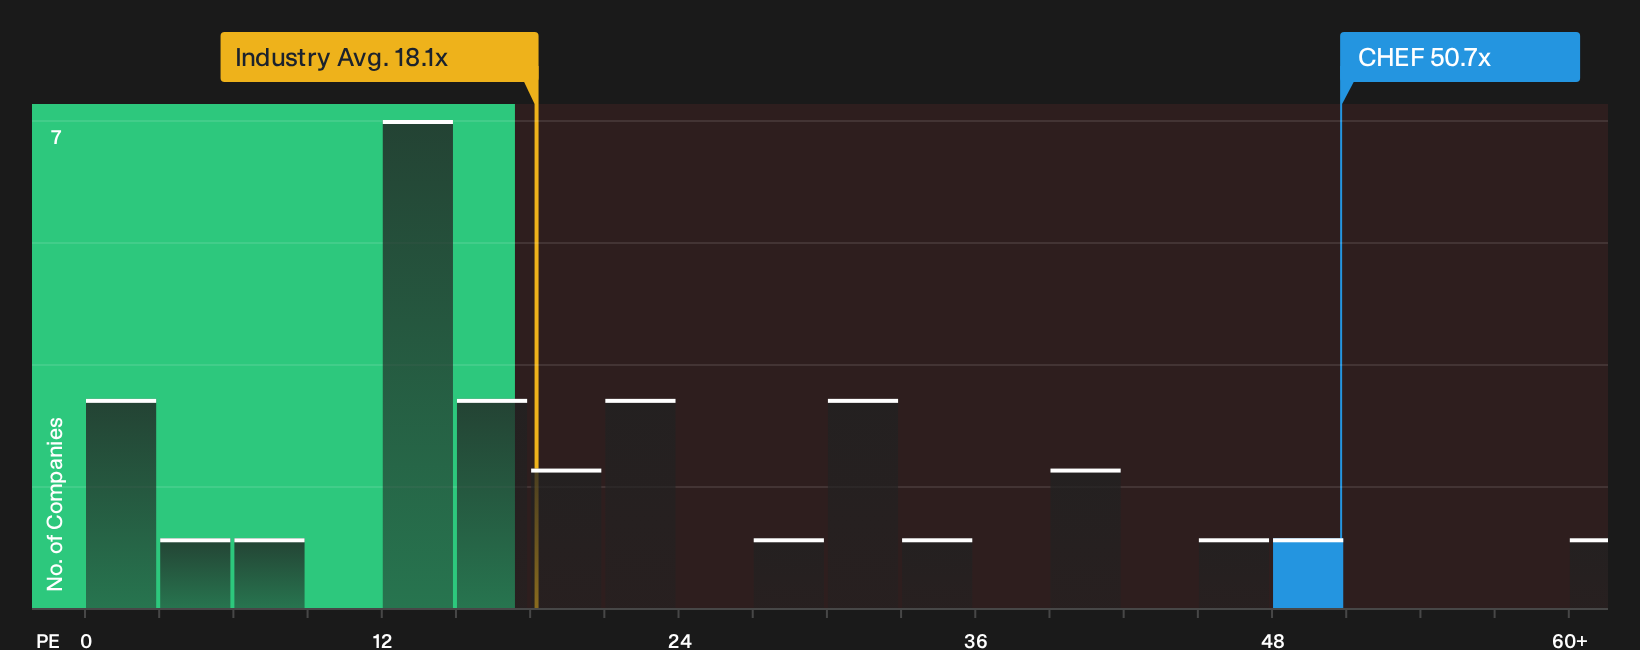
DCF fans see Chefs' Warehouse as undervalued, yet the P/E picture is far less relaxed. The stock trades on 50.7x earnings, compared with 18.1x for the US Consumer Retailing group and a peer average of 28.7x. The fair ratio is estimated at 26.4x, which points to meaningful valuation risk if sentiment cools.
This kind of gap means you are paying a much richer price for each dollar of profit than both the sector and similar businesses, and there is less room for error if growth or margins fall short. The real question is whether you think Chefs' Warehouse can justify such a premium or whether the share price could drift toward that fair ratio over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Chefs' Warehouse valuation and growth story create a split view. Consider acting promptly, reviewing the underlying data, and weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Chefs' Warehouse?
Chefs' Warehouse may be front of mind today, but the next opportunity could be sitting in plain sight while others stay glued to a single ticker.
Use the Simply Wall St Screener to broaden your watchlist before those ideas get crowded.
- Target income stability by reviewing companies in the 8 dividend fortresses that combine high yields with resilient payout histories.
- Hunt for potential mispricing by scanning the 20 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Control risk first and upside second by focusing on the 31 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com