
The Bet Behind Intel's 181% Run
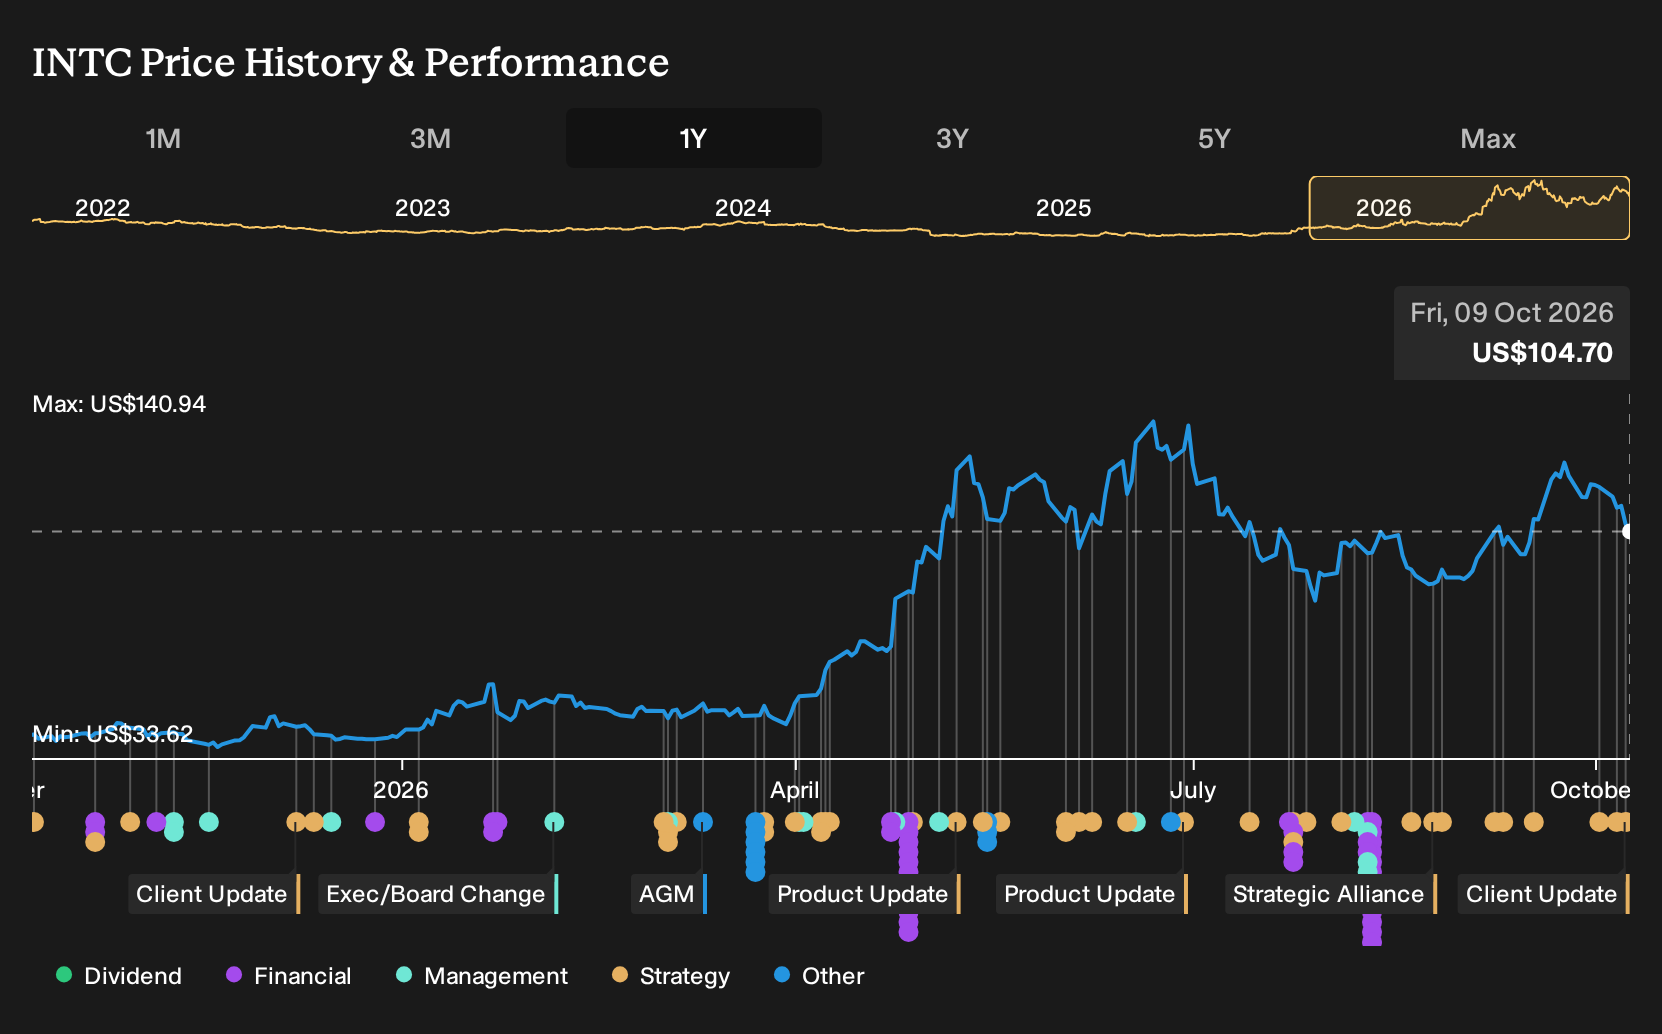
If you had been weighing Intel in October 2025, the headlines were full of AI promises, restructuring noise, and lingering questions about its foundry ambition. For Intel shareholders, the return over the past year was 181.3%, including dividends. The obvious question now is not whether that outcome was pleasant but whether the early buyers were focused on the right things, especially around AI CPUs and capital intensity, when they made their call.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Intel. See which of 92 AI infrastructure stocks may still merit a closer look.
The Two Intel Narratives Investors Had To Weigh
The shares cost US$37.8 at the start of the period. Anyone looking at Intel then had to choose between two very different stories about where the business might be heading.
On the optimistic side, the July 2023 Intel Narrative put Fair Value at US$79, which is 109% above the start price. That view leaned on an ambitious product roadmap, revenue growth assumptions of 10.0% and a 22.0% profit margin, with management aiming to reclaim CPU leadership and benefit from a PC recovery.
The more cautious September 2025 Narrative saw Fair Value at US$25.18, which is 33% below the start price. It treated 3.5% revenue growth and a 7.8% profit margin as more realistic, and flagged execution risk around AI workloads and organizational complexity as potential threats to Intel’s earnings power.
What The Intel Results Actually Tested
Intel’s Q2 2026 report gave the bullish thesis its biggest test. Revenue was US$16,128m versus US$12,859m a year earlier, closer to the growth-led Narrative. At the same time, the business reported a loss of US$11,033m and net margin fell from a 22.7% loss to a 68.4% loss, leaving the profitability part of the optimistic case unproven. Overall, the evidence cut both ways.
The hinge assumption here was not just AI demand but the path to positive net margin. When you assess another chip stock, track whether rising sales actually narrow losses or lift net margin into the black, rather than assuming volume alone fixes the story.
What Intel’s 181% Run Now Asks You To Believe
Intel now trades at US$105. The current cautious Narrative sets its Fair Value below that level and frames the stock as pricing in a demanding recovery story rather than a simple mean reversion.
The Narrative leans on Intel’s breadth in AI chips and restructuring efforts. A buyer today effectively banks on regained execution strength, so the open question is how the manufacturing and competitive risks in that view shape the odds of that outcome.
"BEAR Intel encountered significant manufacturing delays in years past, and there is no guarantee that it can execute well in its aggressive aspirations to develop five process nodes in four years. Even if Intel can regain manufacturing parity with TSMC, AMD now sits as a far more credible chip designer in the x86 space for PC and server CPUs."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 34% below our estimate - converts a large backlog of technology-focused data center and modular construction work.
- Company 2 - 44% below our estimate - integrates acquired banks so anticipated cost efficiencies appear in financial reporting.
- Company 3 - 33% below our estimate - advances late-stage kidney, gene editing and endocrinology treatments beyond existing core therapies.
Those are three of them. See every one of the 29 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com