
Will Class Action Lawsuit Change Dick's Sporting Goods Stock Narrative
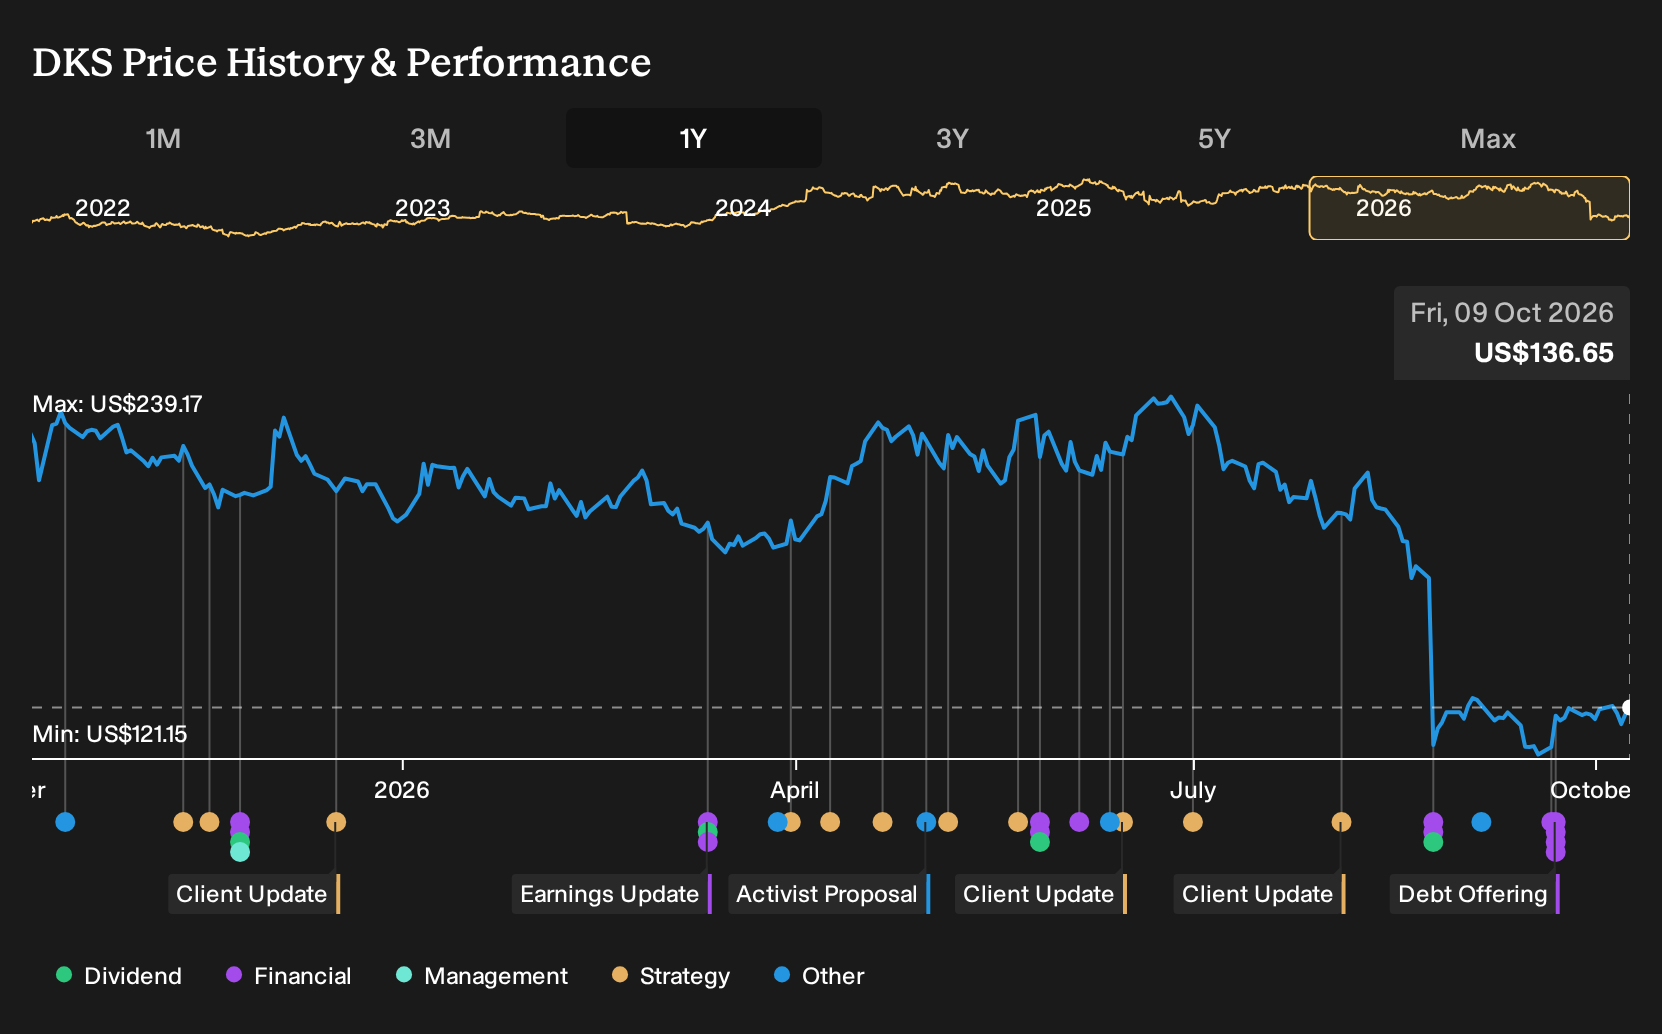
- DICK'S Sporting Goods faces securities class action lawsuits filed after investors alleged the company misled the market on Foot Locker related inventory and promotional challenges during the September 2025 to August 2026 period.
- The litigation highlights how unresolved Foot Locker integration issues, including excess inventory and heavier discounting, could weigh on margins and Foot Locker turnaround expectations for DICK'S Sporting Goods.
- We will now look at how DICK'S Sporting Goods' investment narrative is tested by alleged Foot Locker related misstatements around inventory pressures.
DICK'S Sporting Goods Investment Narrative Recap
To stay a shareholder in DICK'S Sporting Goods, you need to believe the core retail engine, including House of Sport and digital platforms, can offset Foot Locker drag and heavier inventory clearing. The recent lawsuits reinforce that inventory and promotional pressures are front and center. They may keep near term focus squarely on merchandise margins and cash generation.
The key near term catalyst is evidence that Foot Locker losses narrow and discounting pressure stabilizes, alongside steady performance at the core DICK'S banner. The biggest current risk is that excess footwear stock and high integration charges continue, which could keep profit margins around 4% and limit flexibility on dividends and store investments.
The most relevant announcement is the Q2 2026 earnings report and full year guidance cut that triggered the stock drop and the class action filing. Management reported a Foot Locker operating loss of US$31.9 million and comparable sales down 3.6%, and flagged heavier promotional activity tied to excess footwear inventory.
For you, that disclosure sits right on top of the existing Foot Locker catalyst list. Cost synergies of US$100 million to US$125 million, Fast Break remodels showing early double digit comps and better merchandise margins, and planned tapering of up to US$750 million in pretax integration charges now carry more execution risk. Progress here, or lack of it, is likely to define how investors view DICK'S Sporting Goods over the next stretch.
DICK'S Sporting Goods' current analyst narrative points to revenues of US$23.9b and earnings of US$1.4b by 2029, based on 4.2% yearly revenue growth and an earnings increase of about US$561.2m from US$838.8m today.
Uncover how DICK'S Sporting Goods' fair value indicates a 16% potential upside to its current price, a discount that may close sooner than many investors expect.
Exploring Other Perspectives
Some of the lowest analysts put far more weight on legal and Foot Locker related spending, warning that heavy capex and up to US$750m of charges could strain DICK'S Sporting Goods if monetization of media and experiential formats underdelivers. Before this lawsuit news, that group was only penciling in about US$23.0b of 2029 revenue and roughly US$1.0b of earnings, which is well below the consensus path. Use that gap as a prompt to compare several viewpoints and decide which story you find more realistic if these allegations reshape expectations.
Explore 3 other DICK'S Sporting Goods fair value estimates, including one that suggests as much as 70% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DICK'S Sporting Goods research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DICK'S Sporting Goods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DICK'S Sporting Goods' overall financial health at a glance.
Looking for more DICK'S Sporting Goods style investment ideas?
If this Foot Locker story has sharpened how you think about risk and execution at DICK'S Sporting Goods, you can use that same lens across the wider market with the Simply Wall St Screener.
- If you want sturdier balance sheets to compare against these litigation headlines, you can start by scanning a list of solid balance sheet and fundamentals (25 results) that can shoulder tougher conditions.
- For readers focused on price paid versus fundamental quality, you can check out a curated pool of 29 high quality undervalued stocks that combine cash generation with disciplined capital allocation.
- Income focused investors can anchor their watchlist around 8 dividend fortresses that pair higher yields with business models built for consistent payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com