
How Falling Book Value Has Changed Its Investment Story At Horace Mann Educators Stock
- Horace Mann Educators has faced weak growth in insurance policies, pressure on book value per share, and low return on equity, highlighting ongoing operational challenges in a tougher insurance cycle.
- The combination of slower policy momentum, erosion in per share book value, and subpar capital efficiency points to deeper issues in how Horace Mann Educators converts its educator-focused footprint into sustainable profitability.
- We will look at how Horace Mann Educators' investment narrative aligns with recent concerns over low return on equity and execution.
Horace Mann Educators Investment Narrative Recap
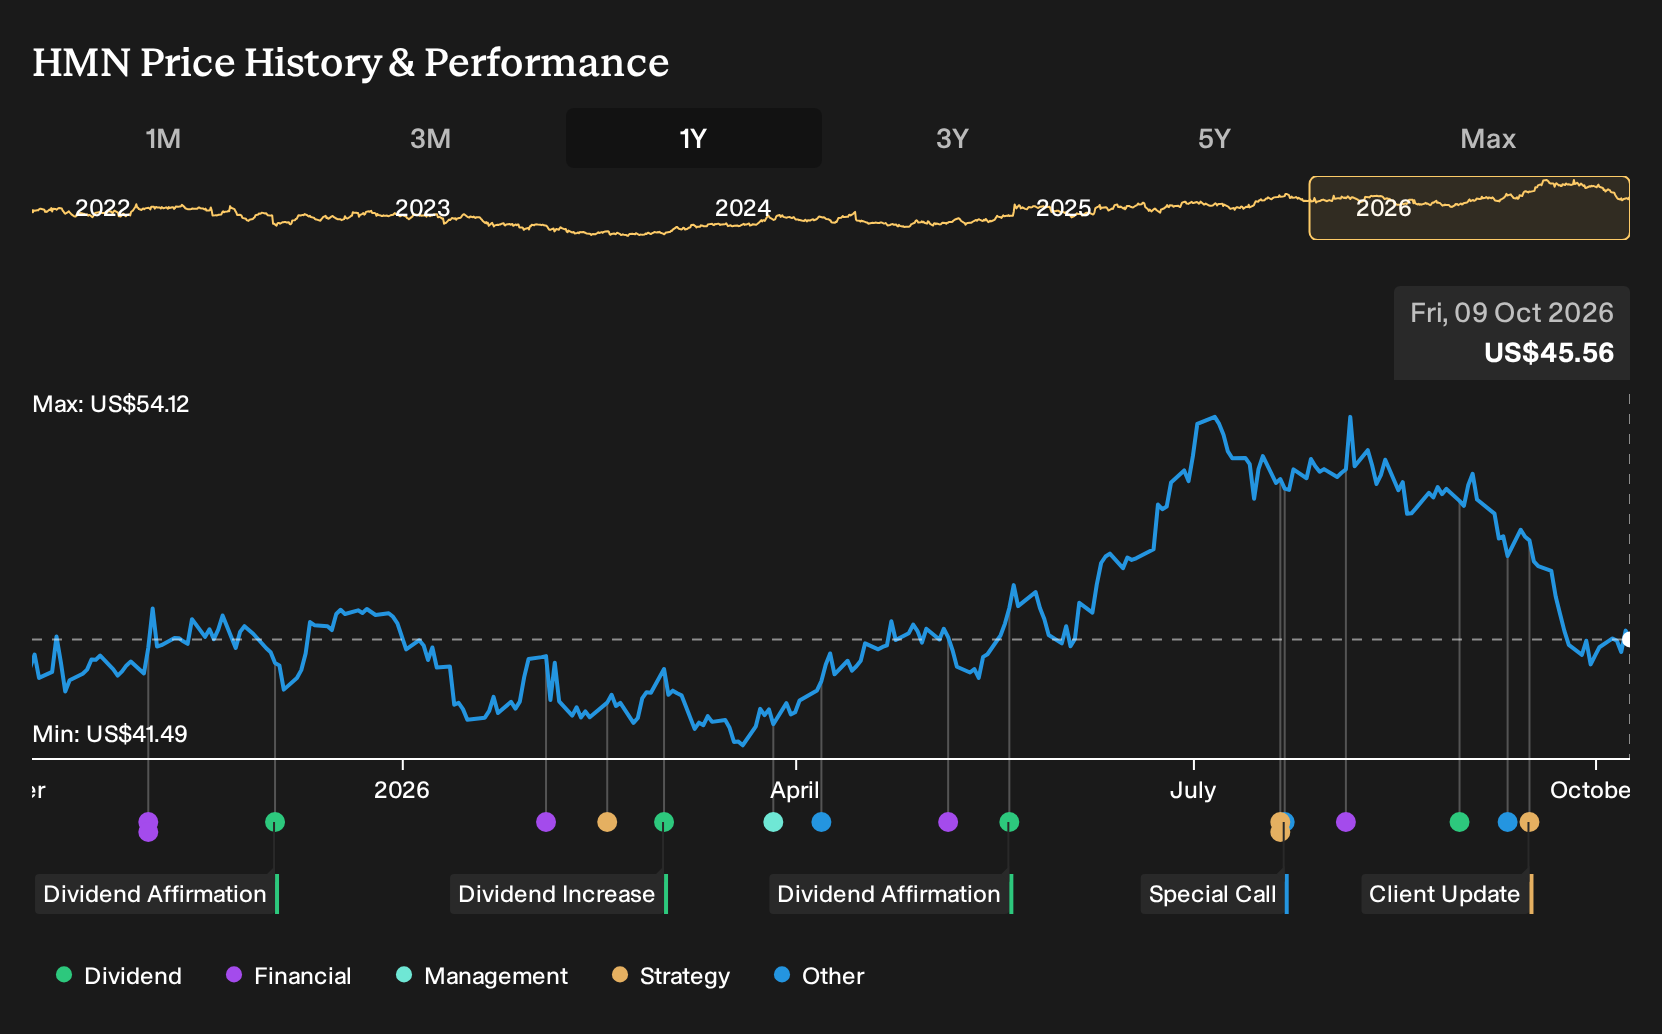
To own Horace Mann Educators, you need to believe the educator focused model can still turn long standing school district relationships into consistent, higher margin protection and retirement earnings. The recent concerns around weaker policy momentum, lower book value per share and modest return on equity speak to execution rather than a sudden shift in the educator market.
The key short term swing factor is whether management can stabilise capital efficiency while keeping underwriting and benefits performance disciplined. The biggest risk remains concentration in public K 12 employment and budgets. The latest news around sluggish policy growth reinforces that risk but does not materially change it.
One of the more important recent developments is management’s move to lower the 2026 total net investment income outlook to US$465 million to US$475 million. For Horace Mann Educators, that matters because the investment portfolio is a major earnings pillar alongside underwriting and benefits profitability.
This guidance cut directly interacts with the low return on equity discussion. If investment returns stay under pressure while policy growth and book value per share remain soft, it becomes harder for the business to lift overall ROE, which is already described as low, and for any operational catalysts in supplemental and group benefits to fully show through.
Horace Mann Educators' narrative projects US$2.3b revenue and US$226.1 million earnings by 2029. This assumes 9.9% yearly revenue growth and an earnings increase of about US$48.8 million from current earnings of US$177.3 million.
Uncover how Horace Mann Educators' fair value indicates a 24% potential upside to its current price that may not be sustained for long.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Horace Mann Educators research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Horace Mann Educators. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Horace Mann Educators' overall financial health at a glance.
Looking For More Investment Ideas Beyond Horace Mann Educators?
If the Horace Mann Educators narrative leaves you wanting a broader watchlist, it can help to line it up against other opportunities with different risk, income and balance sheet profiles using the Simply Wall St Screener.
- If resilience matters most to you, start with a basket of companies that screen well on financial strength and risk using the list of solid balance sheet and fundamentals (25 results).
- Income focused investors who prefer cash returns today rather than only potential capital gains can review a curated set of higher yielding opportunities through the 8 dividend fortresses.
- For those who like to fish where fewer people are looking, widen your search to smaller businesses with strong fundamentals via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com