
How to Play PFE Stock as Pfizer Cuts 300 Jobs
Popular biopharmaceutical company Pfizer (PFE) plans to cut around 330 jobs at its Catania plant in Sicily. This is part of a broader restructuring that includes closing its penicillin department. Earlier, the company had announced that it would add $2.5 billion to its ongoing restructuring in the form of technology and simplification efforts, which extend through 2029 with total savings of $6.7 billion.
The company’s efforts have been mostly to counter the post-Covid drop-off in revenue. There is also the headache of a patent cliff. Pfizer’s Xeljanz, Prevnar 13, and Eliquis offerings are set to lose protection this year, with Ibrance and Xtandi following in 2027. To counter this threat, the company is pursuing potential product launches, such as fast-tracking its obesity programs. However, the obesity push has not yielded much so far.
Therefore, as the company searches for new revenue avenues, restructurings may continue in the near term. Let's take a closer look at what this means for PFE stock.
About Pfizer Stock
Pfizer is a global biopharmaceutical company headquartered in New York City. It discovers, develops, manufactures, and commercializes medicines and vaccines across oncology, immunology, internal medicine, rare disease, and hospital care. Pfizer has a market capitalization of $158.57 billion.
The company is pursuing growth through newer product launches, cost discipline, and strategic acquisitions, including its completed purchase of Metsera, which strengthens its obesity and cardiometabolic pipeline. Pfizer is also expanding access programs and adapting to U.S. drug-pricing policy changes while maintaining a broad research, development, and manufacturing footprint worldwide.
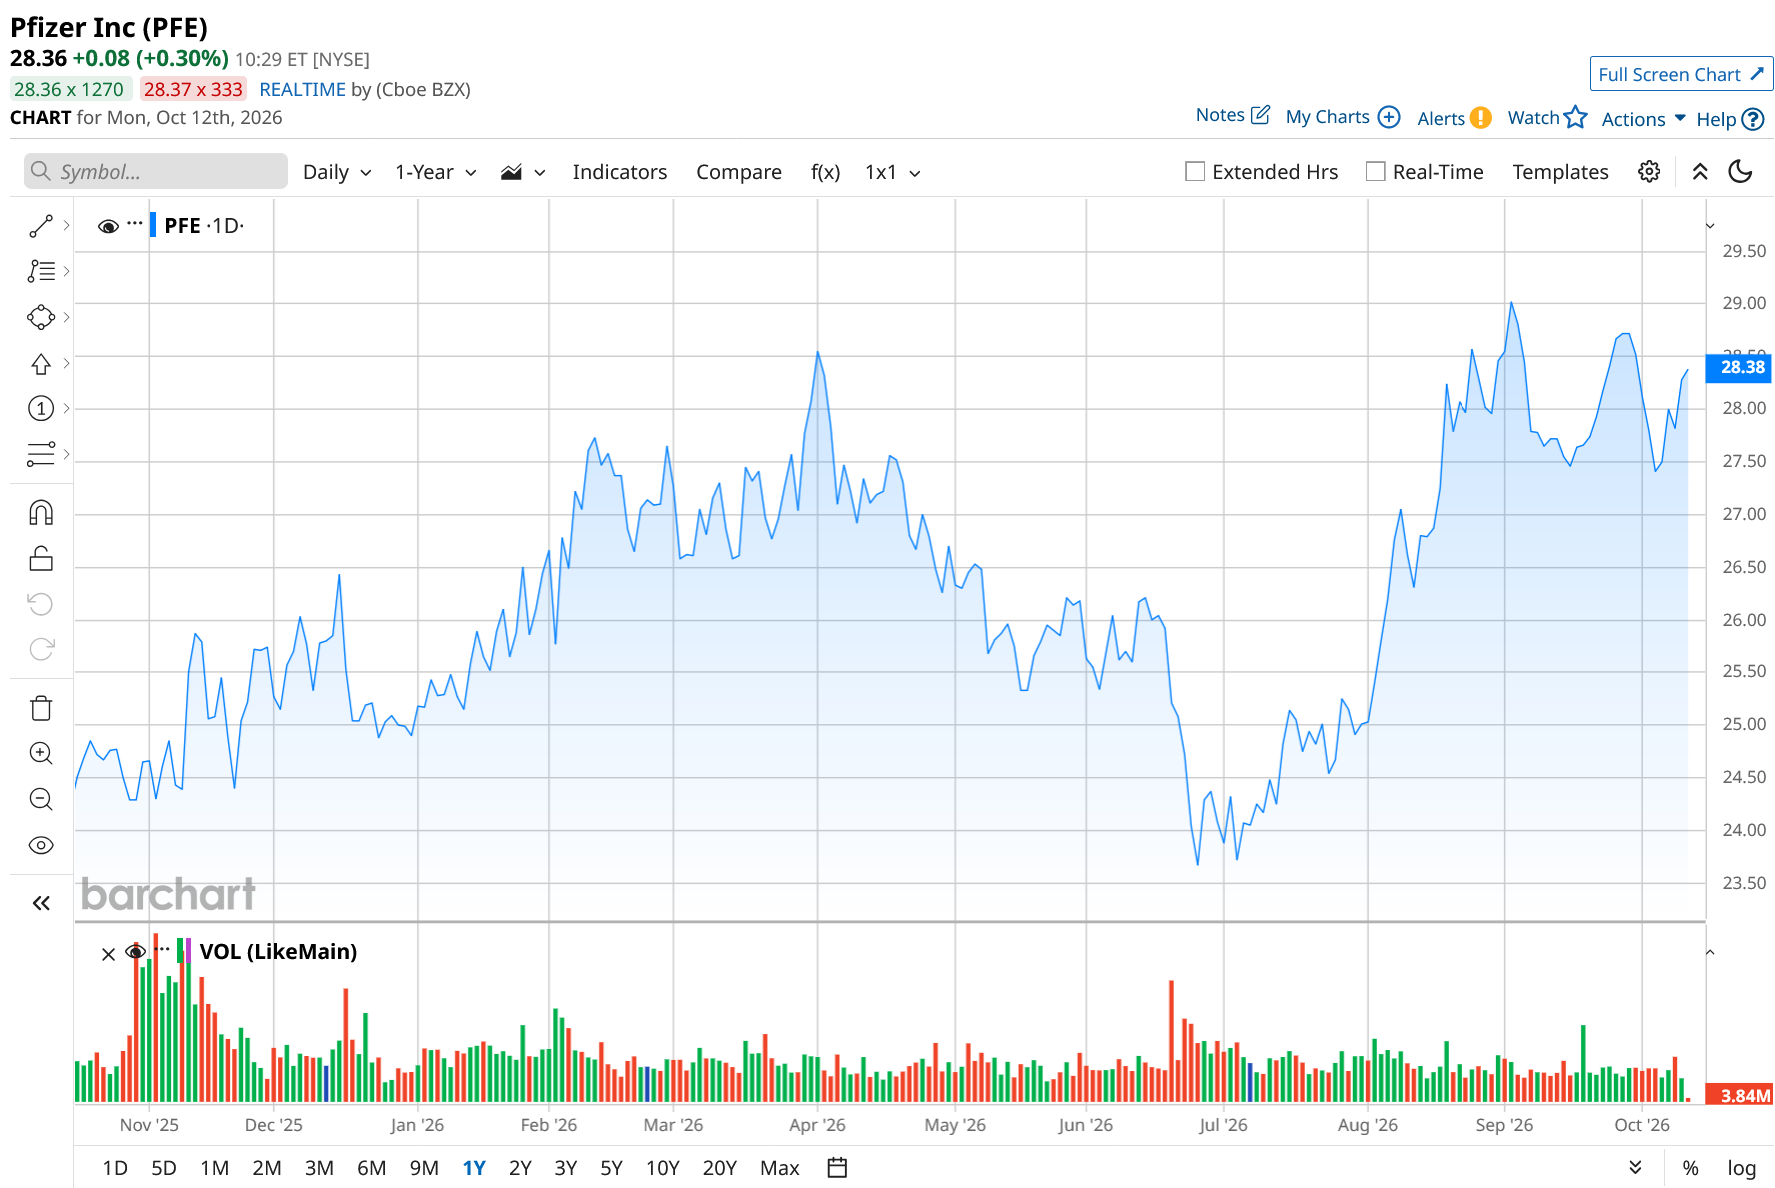
Pfizer’s 15% gain over the past 52 weeks reflects a shift from “Covid decline” concerns toward evidence that its non-Covid business and pipeline can support the next growth phase. Over the past three months, the stock is up 18%. The company’s shares reached a 52-week high of $29.21 on Sept. 3, but are down 2.7% from that level. It had also reached a 52-week low of $23.62 on July 6, but is up 20% from that level.
As volatility has somewhat capped gains, Pfizer’s stock is now trading relatively cheaply. Its forward-adjusted price-to-earnings (non-GAAP) ratio of 9.37x is lower than the industry average of 18.69x.
Q2 Revenue Rose on Non-Covid Growth; Company Lifted Full-Year Outlook
For the second quarter, Pfizer reported a solid quarter based on products that are not tied to Covid-19. The company’s focused execution efforts drove an 18% operational revenue growth from launched and acquired products. Pfizer’s total revenues increased 3% year-over-year (YoY) to $15.03 billion.
Excluding contributions from Comirnaty and Paxlovid (Pfizer’s Covid-19 products), revenues grew 5% operationally. This was driven by biopharma revenues growing 2% YoY (1% operationally) to $14.66 billion. Adjusted EPS remained roughly flat at $0.77.
Based on this, Pfizer raised its full-year revenue guidance by $500 million at the midpoint to a range of $60.50 billion to $62.50 billion, from $59.50 billion to $62.50 billion. The company also reaffirmed its adjusted EPS guidance to $2.80-$3.0. However, Wall Street analysts have a tepid opinion of Pfizer’s bottom-line trajectory. For fiscal 2026, EPS is projected to drop 7.5% YoY to $2.98, followed by another marginal drop to $2.96 in fiscal 2027.
What Do Analysts Think About PFE Stock?
This month, analysts at Cantor Fitzgerald raised its price target from $27 to $28 while maintaining a “Neutral” rating. Analysts at the firm believe PFE stock remains tied to MEVPRO-1 results, while the company faces questions about the sustainability of its dividend and long-term growth. Analysts also see the third-quarter results as a non-event, tying the price target raise to a renewed assessment of growth in the company’s legacy products.
Scotiabank analysts raised Pfizer’s price target from $30 to $33, while maintaining an “Outperform” rating. Analysts at the firm think the price target raise was warranted because the company’s products, pipeline, and execution continue to exceed expectations.
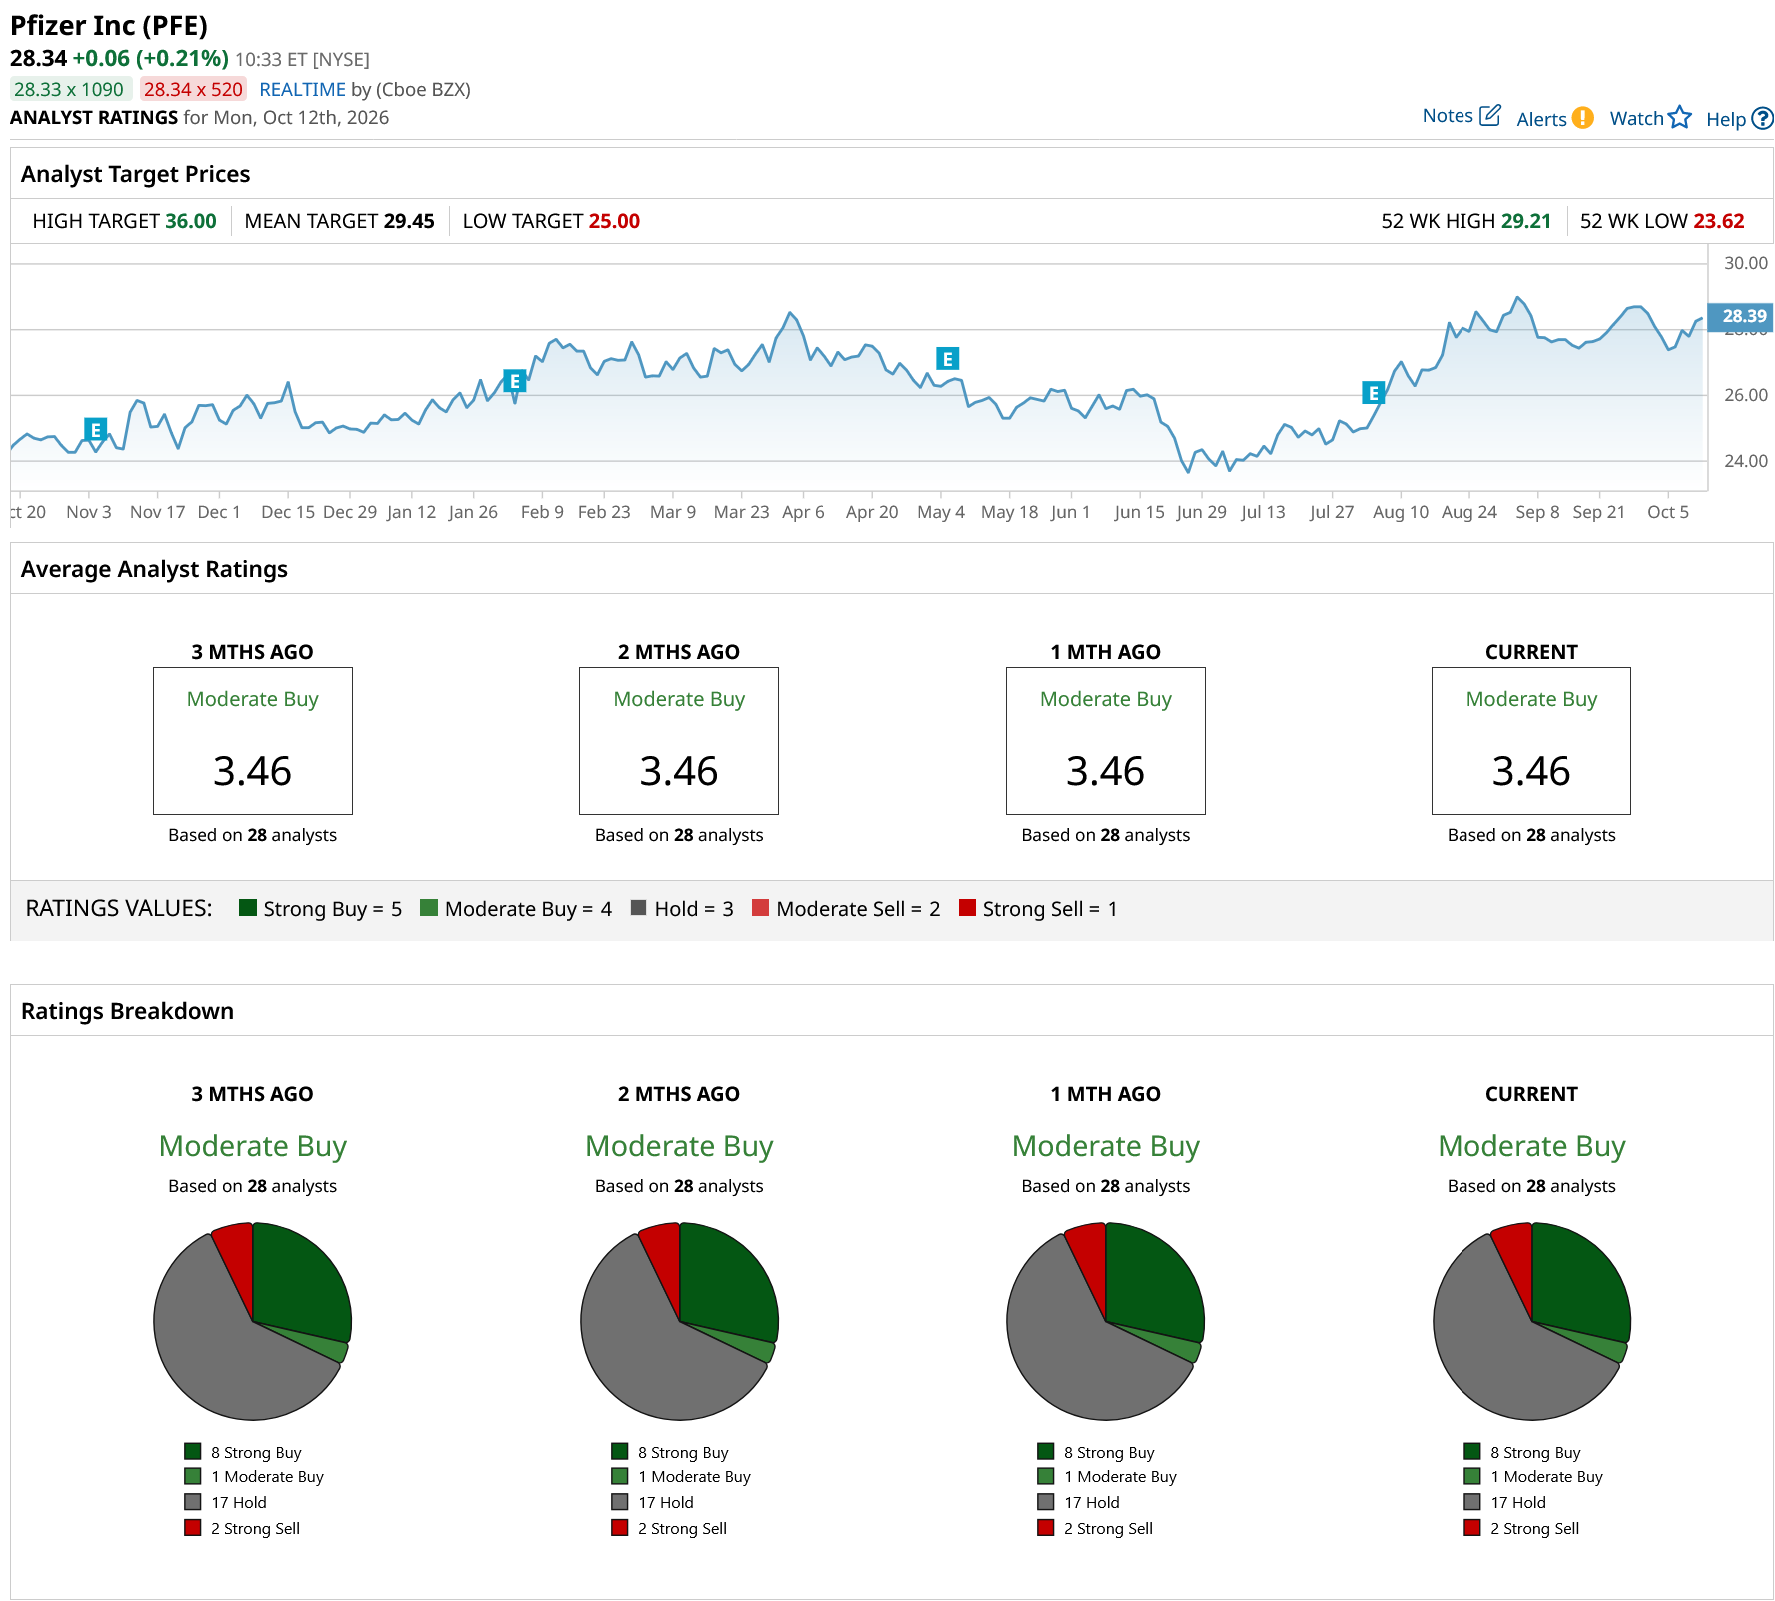
PFE stock has been in the spotlight on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating. Of the 28 analysts rating PFE, eight analysts have rated it a “Strong Buy,” one analyst suggests a “Moderate Buy,” 17 analysts are playing it safe with a “Hold” rating, and two analysts gave a “Strong Sell” rating. The consensus price target of $29.45 represents a 4% upside from current levels. The Street-high price target of $36 indicates a 27% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.