
Amazon.com (AMZN) Eyes Decart, Is The AI Upside Already Priced In?
Amazon.com (AMZN) is back in focus after reports the retailer is weighing a roughly US$7b purchase of AI startup Decart, a potential move aimed at strengthening its custom chip ecosystem.
Recent trading shows that enthusiasm around Amazon.com’s AI push is feeding into price momentum, with a 1-day share price return of 3.29% and a 7-day share price return of 4.39% as the Decart talks hit headlines.
Across 2026 so far, the share price return of 15.86% points to a steady grind higher rather than a sudden spike. A 1-year total shareholder return of 19.25% and a 3-year total shareholder return of 97.99% highlight how long-running AI and cloud themes continue to frame how investors view the stock.
Scan for other AI infrastructure plays moving on similar catalysts using our hand picked 92 AI infrastructure stocks, which is tied to cloud spend, data centers, and custom chips like Amazon.com’s Trainium platform.
Amazon.com has the scale, cash generation and AI footprint many investors look for. After the Decart headlines and recent gains, the real work now is testing whether that strength is already fully priced in.
Most Popular Narrative: 45% Undervalued
Amazon.com last closed at $262.43, while the most followed narrative on the stock pegs fair value at $475.09 according to KiwiInvest. That gap raises a clear question for readers about whether the market is fully factoring in the mix of retail, cloud, and AI that now defines the business.
Amazon is a company of two sides. A high tech, high margin side, comprising its AWS, Advertising and subscription services segments, and its more traditionally known low margin, high volume stores and third-party seller segments. These two sides form a cohesive whole. The Amazon online store motivates customers to purchase subscriptions and hosts its advertising. AWS underpins the functioning of the online store, but is also easy to integrate with for Amazon's many third-party sellers, encouraging adoption.
See why 296 investors see Amazon.com as 45% undervalued.
Result: Fair Value of $475.09 (UNDERVALUED)
Still, the Amazon.com story can get knocked off course if AI infrastructure spending cools or if the lower margin retail engine puts more pressure on profits.
Find out about the key risks to this Amazon.com narrative.
Another View On Amazon.com’s Valuation
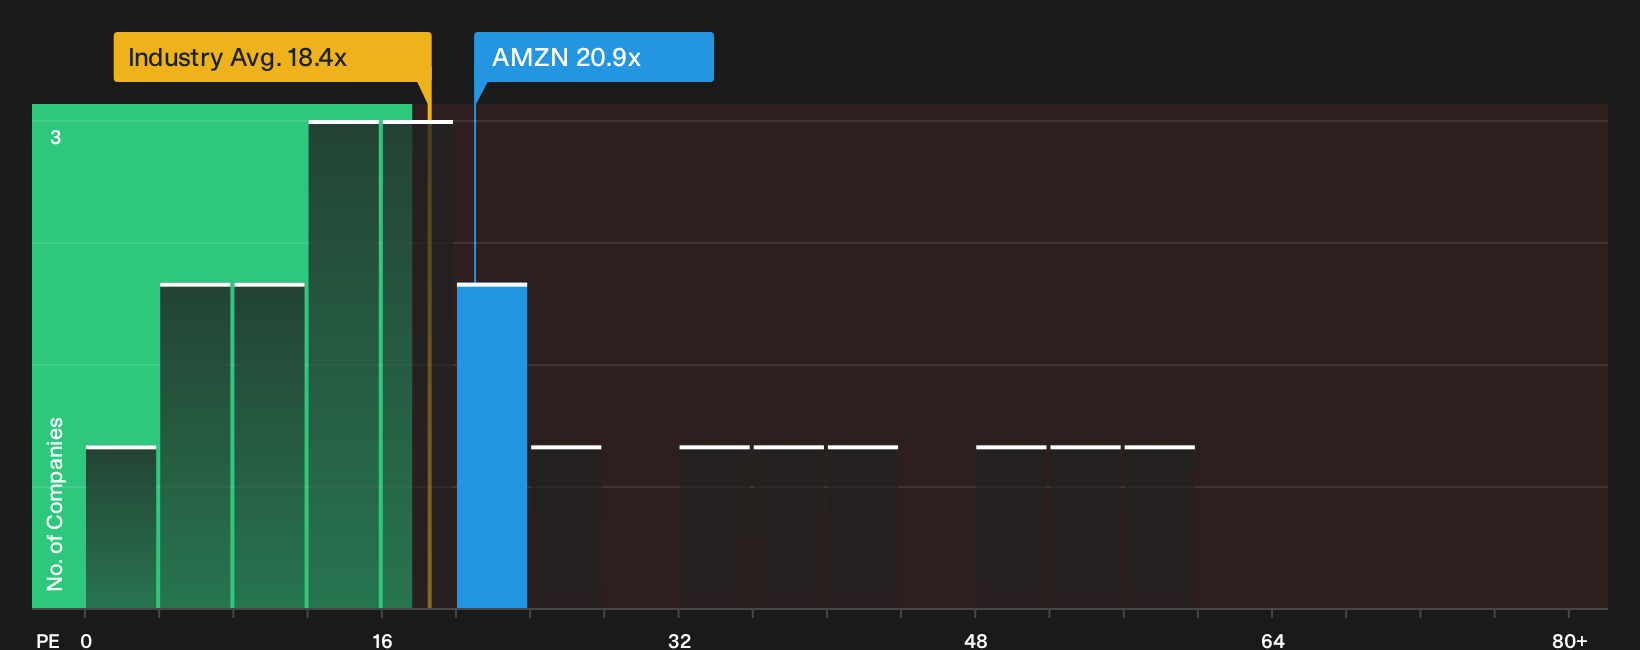
Market pricing tells a different story to the KiwiInvest fair value. At $262.43, Amazon.com trades on a P/E of 20.9x, which is richer than the Global Multiline Retail industry on 18.4x, yet below the peer average on 27x and under a fair ratio of 29.3x.
That mix of higher pricing than the wider sector but a discount to peers and the fair ratio points to a tighter margin of safety than a 45% undervaluation headline might suggest. The key question is which signal you treat as your anchor.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Amazon.com after reading all this. Do not wait for consensus to form around you; review the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Amazon.com?
If you only focus on Amazon.com, you miss other opportunities that fit your goals, risk limits, and income needs across very different types of businesses.
- Target faster growth potential with carefully filtered small caps by using the 12 elite penny stocks with strong financials.
- Hunt for quality businesses at appealing prices through the 29 high quality undervalued stocks.
- Strengthen your income stream with companies that focus on reliable payouts via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com