
Ichibanya (TSE:7630) Sales Rose As Earnings Softened, Is The Stock Now Too Expensive?
Ichibanya (TSE:7630) has put two signals on the table for investors. The curry chain reported half year results with higher sales but weaker earnings, while keeping its second quarter dividend flat at ¥8 per share.
The share price tells a mixed story. Ichibanya’s stock has a 90 day share price return of 14.98% and a year to date gain of 14.10%, while the 1 year total shareholder return of 13.36% and 5 year total shareholder return of 24.17% point to momentum that has softened recently rather than sharply reversed.
Compare Ichibanya’s mix of steady dividends and softer earnings with hand picked consumer and restaurant stocks screened for resilient fundamentals using our list of solid balance sheet and fundamentals (22 results) today.
Ichibanya appears to be a solid curry franchise with rising sales and a dividend that has held steady even as earnings softened. After the recent share price climb, is that quality now fully reflected in the valuation, or not yet?
Price-to-Earnings of 73.3x: Is it justified?
On valuation, Ichibanya trades on a P/E of 73.3x at a last close of ¥1,044, which is a rich tag compared to both peers and its own recent earnings softness.
The P/E ratio compares what investors are willing to pay today for each unit of current earnings. For a consumer services group like Ichibanya, a higher multiple often reflects confidence in the durability of its brand, store economics and the potential for future profit growth rather than just the most recent year of results.
For this stock, the market appears to be pricing in earnings that are expected to grow 12.5% per year while accepting a low return on equity of 7.1% and thinner profit margins than last year. That is a steep premium to what the SWS fair P/E suggests, which signals a level the share valuation could move closer to if expectations cool.
The gap is stark. Ichibanya’s 73.3x P/E is much higher than the 30.9x average of its peer group and far above the 22x average for the wider JP Hospitality industry, which highlights how aggressively this franchise is valued right now compared with sector norms and the estimated fair P/E of 22.6x.
Explore the SWS fair ratio for Ichibanya.
Result: Price-to-Earnings of 73.3x (OVERVALUED)
Still, the valuation story for Ichibanya could quickly look different if earnings growth disappoints or if sentiment toward premium consumer stocks cools.
Find out about the key risks to this Ichibanya narrative.
Another view on Ichibanya’s value
The SWS DCF model paints a very different picture to the rich 73.3x P/E. On this approach, Ichibanya at ¥1,044 is trading well above an estimated future cash flow value of ¥200.34. This points to a stock that screens as expensive rather than cheap on cash generation.
For readers who want to see how the cash flow based estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
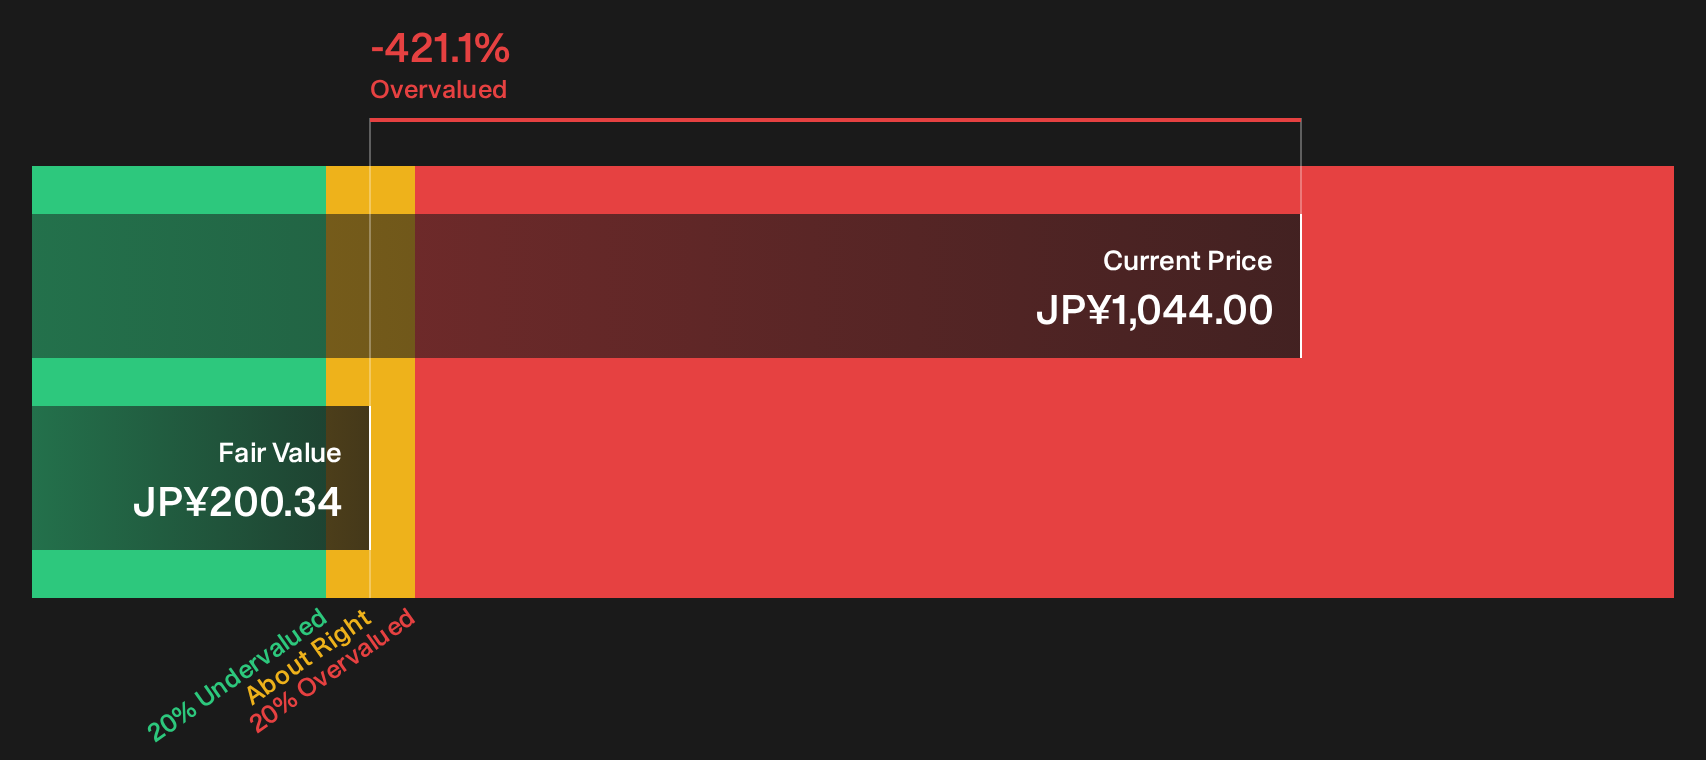
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ichibanya for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message on Ichibanya? Move quickly from just reading to testing the numbers yourself by starting with its 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Ichibanya?
Do not stop at Ichibanya. Give yourself an edge by scanning fresh ideas across different angles so you always have strong candidates on your radar.
- Target income potential by reviewing companies in the 28 dividend fortresses that could help anchor a portfolio with cash returns.
- Spot quality at a discount by checking the 12 high quality undervalued stocks and see which businesses combine solid fundamentals with appealing pricing.
- Strengthen your downside protection by filtering through the 23 resilient stocks with low risk scores and focus on stocks that score well on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com