
New CFO Appointment Could Be A Big Moment For VERBUND Stock (WBAG:VER)
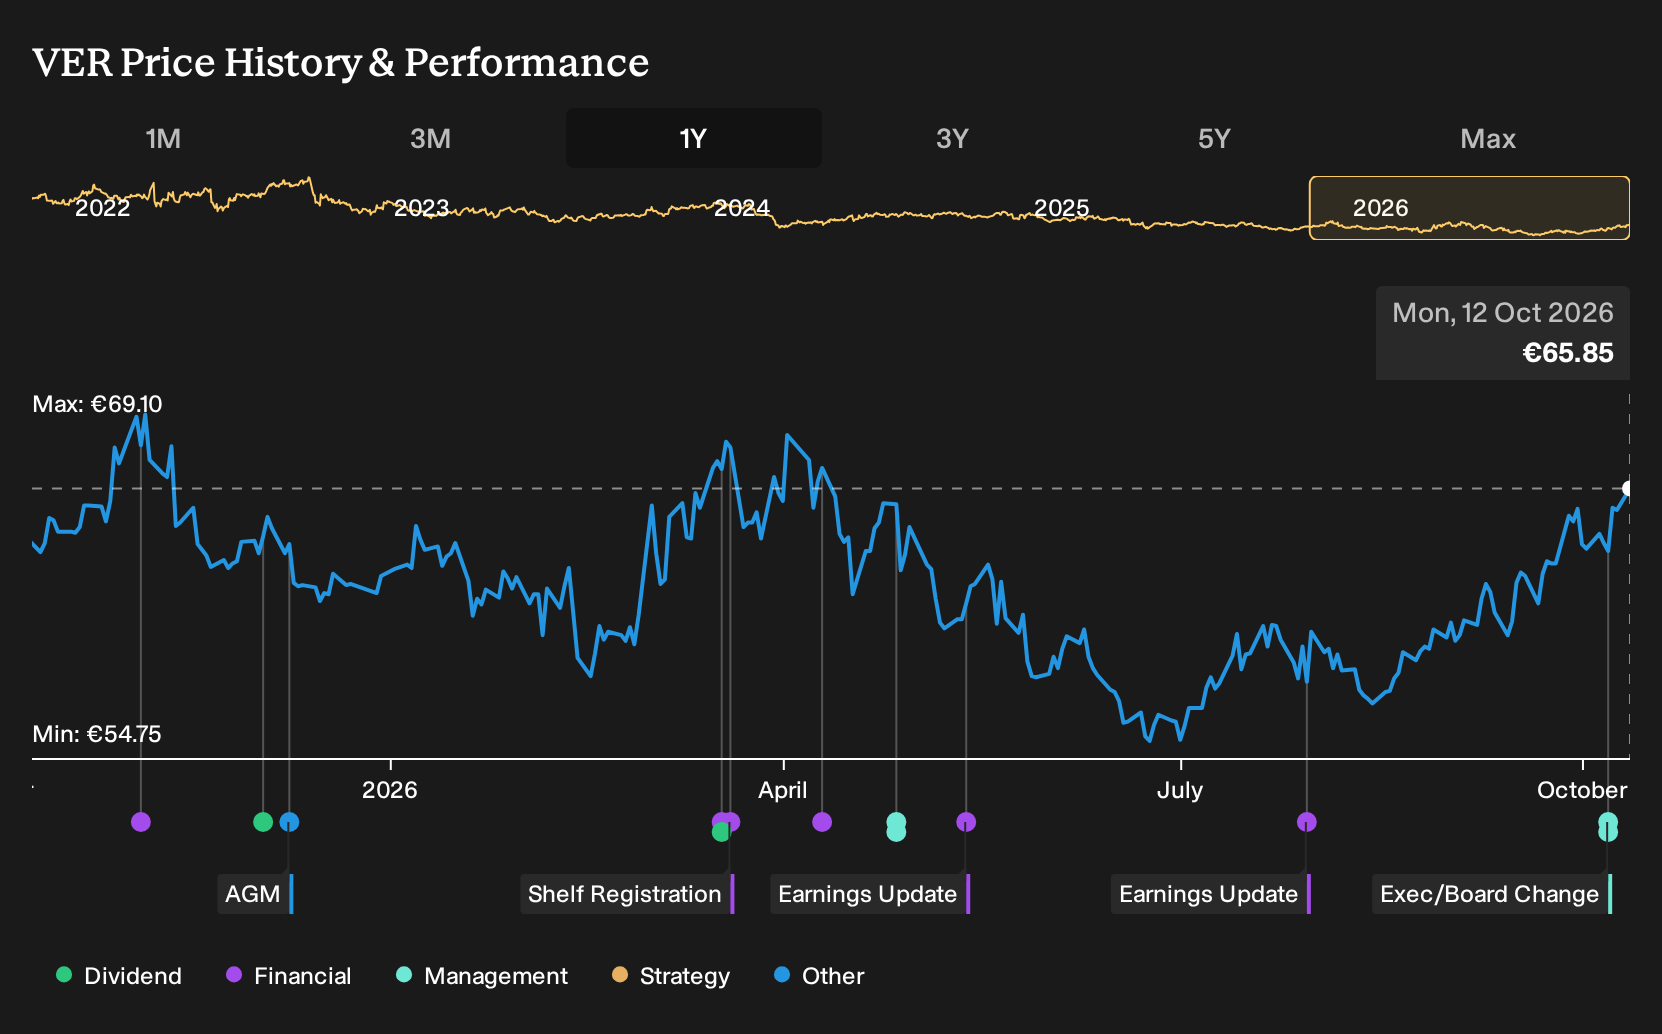
- VERBUND AG’s Supervisory Board appointed Stefan Waldner as Chief Financial Officer and Management Board member in October 2026, on an initial two year term with an option for a further two years, following the August departure of former CFO Peter Kollmann.
- Waldner’s background in international energy finance, capital markets and M&A, including senior roles at OMV and earlier experience at Merrill Lynch, directly connects VERBUND’s financing leadership to large project funding and balance sheet decisions.
- We will now look at how VERBUND’s investment narrative may evolve as a seasoned, capital-markets-focused CFO joins the board.
Compare how VERBUND’s new capital markets focused CFO stacks up against peers by scanning our hand-picked list of list of solid balance sheet and fundamentals (202 results) for ideas with similar financial discipline.
VERBUND Investment Narrative Recap
To own VERBUND, you need to be comfortable with a utility whose fortunes are tightly linked to hydropower, storage projects and European power and gas pricing rather than rapid volume expansion. The big operational swing factor in the near term remains execution of large pumped storage investments and how effectively that portfolio is traded and hedged in volatile wholesale markets.
The biggest immediate risk is that actual revenue, margins and earnings land far from current assumptions, which could reset how the market prices VERBUND’s earnings stream. The CFO switch itself is more about who steers capital allocation through that volatility than a new short term catalyst. On its own, the appointment does not radically change near term drivers.
The CFO appointment on 7 October 2026 is the announcement that really ties into today’s story. VERBUND now has a finance chief whose experience spans international energy, capital markets and M&A, including senior roles at OMV and earlier work at Merrill Lynch. That background connects directly to decisions on funding hydropower storage builds and managing balance sheet risk.
For you as a shareholder, the key link is execution. Hydropower storage projects in Germany and elsewhere require disciplined financing, careful leverage and clear return hurdles. A capital markets focused CFO can influence how VERBUND sequences new capacity, structures debt and weighs dividends against investment needs. All of these factors shape how resilient earnings and free cash flow look if power prices or margins move against current expectations.
What Analysts Are Pricing In For VERBUND
Analyst models around VERBUND are built on a fairly tight band of expectations. They point to revenue shrinking by 3.6% a year while profit margins edge higher and earnings hold steady. That mix matters for how you interpret the new CFO hire because it frames what the market already assumes about cash generation and balance sheet capacity.
Under the current consensus, earnings today sit at about €1.2b, with the same €1.2b figure used as the anchor for 2029 forecasts. The range around that is wide. The most optimistic analyst pencils in about €1.6b of profit, while the most cautious sits closer to €857.7m. For you as an investor, that spread shows how much disagreement there is on what future hydropower storage returns and power pricing could mean for the income statement.
To make these numbers line up with published price targets, brokers assume VERBUND trades on a P/E of 20.4x in 2029, up from about 18.7x today and higher than the 14.5x cited for the GB electric utilities sector. A higher multiple usually implies confidence in earnings quality or project pipeline. It also means the stock could be sensitive if sentiment on execution, regulation or commodities shifts away from current assumptions.
Those same analyst models plug in 2029 revenue of €6.8b alongside that €1.2b earnings outcome, using discount rates of just over 6% to bring everything back to today. With the current share price around €64.9 and a consensus target of €60.75, the implied downside sits at roughly 6.8%. That small gap suggests the average view is that VERBUND is trading close to what these scenarios describe, even if individual broker targets stretch from the mid €50s to the high €80s.
VERBUND's narrative projects €6.8b revenue and €1.2b earnings by 2029. This rests on revenue decreasing 3.6% yearly and earnings staying flat around €1.2b.
Uncover how VERBUND's fair value indicates an 8% potential downside to its current price, a valuation premium that leaves little room for error.
Exploring Other Perspectives
One potential angle to explore is how pumped storage could reshape VERBUND’s earnings path. The most optimistic analysts were already sketching out about €9.0b of revenue and €1.6b of earnings by 2029, compared with the €6.8b and €1.2b in the baseline view. With Stefan Waldner stepping in as CFO, those pre news scenarios might shift again. This may be a useful moment to compare these very different stories and decide which assumptions you find more convincing.
Explore 3 other VERBUND fair value estimates, including one that suggests as much as 17% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A useful starting point for your VERBUND research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for VERBUND. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate VERBUND's overall financial health at a glance.
Looking for more VERBUND sized investment ideas?
If VERBUND has sharpened your focus on balance sheets, earnings quality and capital allocation, it can help to widen your watchlist with companies that share some of those financial traits. The Simply Wall St Screener is a quick way to surface stocks that match the type of risk and return profile you want to research next.
- For investors who care most about resilient business models and capital preservation, consider starting with a curated set of 226 resilient stocks with low risk scores that aim to keep downside in check.
- If your priority is finding companies that pair strong fundamentals with attractive pricing, use the filter for 179 high quality undervalued stocks and see which ideas line up with your return expectations.
- Income focused investors who want yield backed by solid finances can scan a targeted pool of 220 dividend fortresses and compare payout strength against balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com