
Energix Renewable Energies (TASE:ENRG) Advances Lithuania Wind Buildout, Is The Stock Fully Priced?
Energix - Renewable Energies (TASE:ENRG) has moved ahead with its Lithuanian growth plan by signing agreements to purchase and install 296MW of wind turbines for the Tower, Boniskiai and Vandziogala projects.
Investors have already been reacting to Energix - Renewable Energies' expansion plans, with the 1-day share price return of 2.16% and year-to-date share price gain of 7.78% sitting alongside a 1-year total shareholder return of 15.27%. However, the 30 and 90 day share price returns show fading short term momentum compared with the stronger 3 and 5 year total shareholder returns of 99.49% and 44.68% respectively.
Scan other renewable-focused stocks showing similar expansion stories by checking the hand picked 43 power grid technology and infrastructure stocks.
So is this Lithuanian push a sign that Energix - Renewable Energies is quietly executing on an existing growth engine while sentiment cools, or has enthusiasm run ahead of what the business itself justifies on the numbers?
Price-to-Earnings of 79.6x: Is it justified for Energix - Renewable Energies?
On the latest close at ₪18.00, Energix - Renewable Energies trades on a P/E of 79.6x, which places the stock at a rich valuation compared with both its peer group and the broader Asian renewable energy sector.
P/E looks at what investors are paying today for each unit of reported earnings. For a capital intensive renewables player such as Energix - Renewable Energies, such a high earnings multiple usually reflects strong confidence in future profit growth or a willingness to look through current margin pressure.
The picture is mixed. Earnings have grown by 14% per year over the past 5 years, yet profit fell 37.2% over the last year and net margins moved from 23.7% to 16.3%. High levels of non cash earnings and interest payments that are not well covered by earnings also point to some quality and balance sheet questions sitting behind that elevated multiple.
Compared with the Asian renewable energy industry average P/E of 14x and a peer average of 46.4x, Energix - Renewable Energies is trading on a much steeper valuation that prices in a far stronger earnings profile than its group, without clear evidence from current profitability to support that gap.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 79.6x (OVERVALUED)
Still, Energix - Renewable Energies faces clear pressure points if expectations crack, including concerns about earnings quality and any slowdown or disruption in bringing new capacity on line.
Find out about the key risks to this Energix - Renewable Energies narrative.
Another View: What the SWS DCF Model Says About Energix - Renewable Energies
The rich 79.6x P/E paints Energix - Renewable Energies as a high expectation story. The SWS DCF model tells a different story. On that framework, the estimated future cash flow value sits at ₪3.81 per share, well below the current ₪18 price, which points to a stock that screens as heavily overvalued on cash flows.
That kind of gap can reflect investors putting more weight on long term project optionality than on near term cash generation. It leaves a clear question for you as a holder or potential buyer: Which lens should carry more weight in your own process, earnings multiples or cash flow value?
Look into how the SWS DCF model arrives at its fair value.
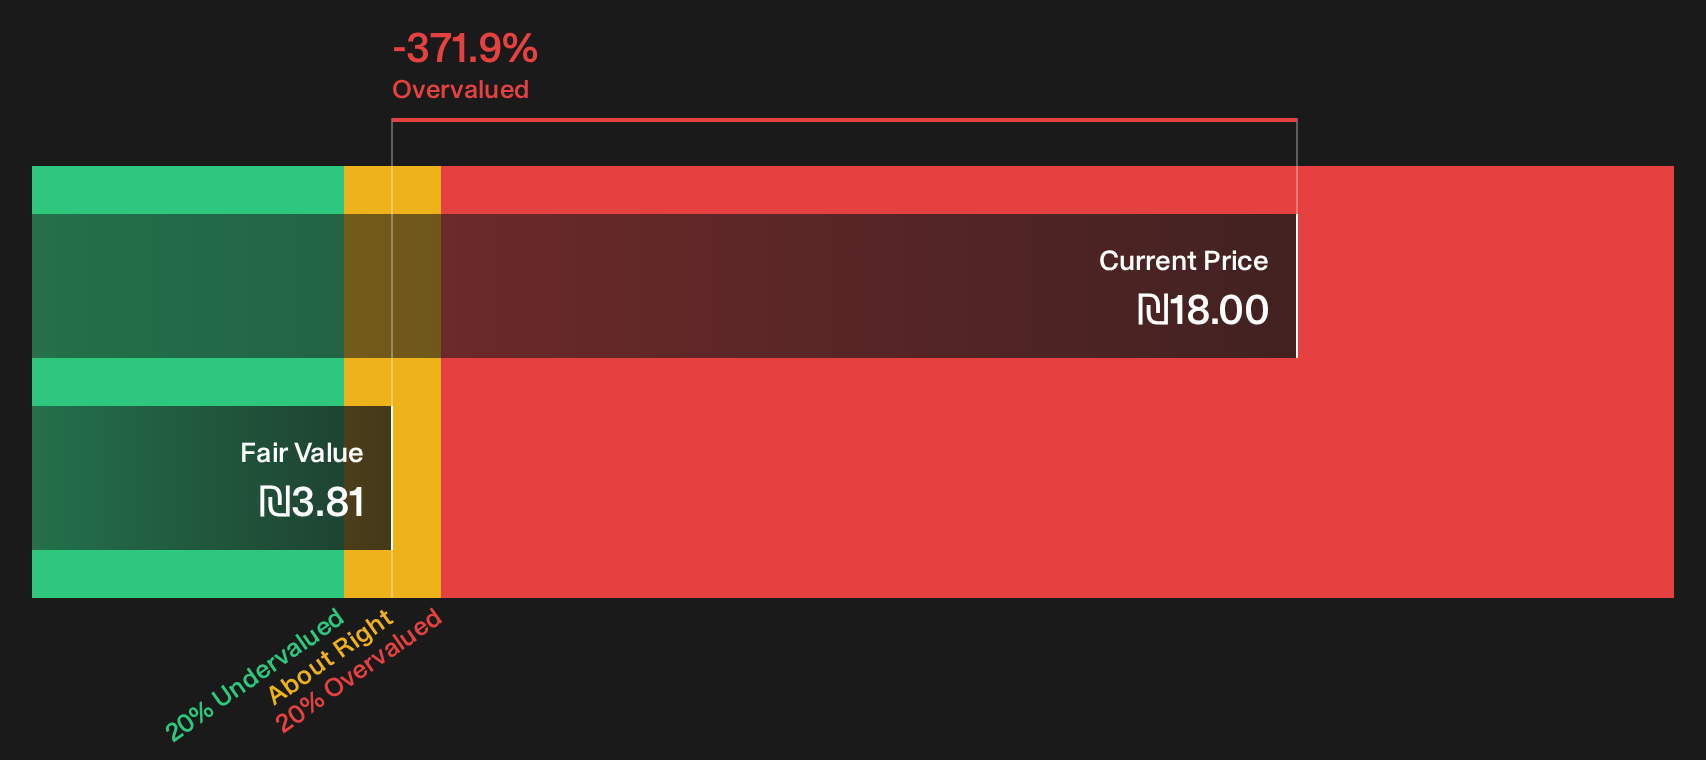
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Energix - Renewable Energies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this all sounds cautious on Energix - Renewable Energies, treat it as a prompt to check the data yourself and move fast in forming a view. To weigh those pressure points alongside the growth story, start with our breakdown of 4 important warning signs
Looking for more investment ideas beyond Energix - Renewable Energies?
Do not stop at Energix - Renewable Energies. Broaden your watchlist now with focused stock ideas that match different risk levels, income goals and value preferences.
- Target potential mispriced opportunities early by scanning the 620 high quality undiscovered gems before they attract wider attention.
- Prioritise resilience and capital protection by reviewing the 228 resilient stocks with low risk scores that score well on stability.
- Combine quality with compelling entry prices by working through the 179 high quality undervalued stocks that screen strongly on fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com