
Unite Group (LSE:UTG) Faces Fresh Activist Pressure, Does The Valuation Gap Still Hold?
Unite Group (LSE:UTG) is back in focus after fresh activist noise around Achilles Investment Company, which holds an 11.3% stake and is eyeing new campaigns across real estate and infrastructure holdings.
Recent trading tells a different story to the activist noise. Unite Group’s share price has slipped, with a 30 day share price return down 9.08% and a year to date share price return down 22.07%, while the 1 year total shareholder return has declined 22.83%. This signals fading momentum even as renewed interest from Achilles and fresh analyst commentary keep the stock firmly on investors’ radar.
Compare the activist pressure and student housing story at Unite Group with other real estate and infrastructure plays by scanning our hand picked 4 resilient stocks with low risk scores for ideas with more resilient profiles.
Bulls point to Unite Group’s student housing footprint and analyst optimism, while bears highlight share price weakness and recent revenue decline. Which side do the current valuation metrics support next?
Preferred Price-to-Sales of 5.3x: Is it justified?
On Simply Wall St’s numbers, Unite Group trades on a P/S of 5.3x, which screens as cheap compared to both peers and the wider European residential REITs group, even after the share price slide to £4.29.
The P/S ratio compares the company’s market value to its £413.4m of revenue and is often used for property vehicles where earnings can be distorted by valuation swings. For Unite Group, this helps anchor the discussion when the business is currently reporting a net loss of £506.2m and traditional profit metrics are harder to use.
Against that backdrop, the 5.3x P/S looks restrained when set beside the European Residential REITs industry average of 7.7x. It also sits below the estimated fair P/S of 6.8x for Unite Group. This suggests the market is pricing the stock more cautiously than the fair ratio level that the SWS model suggests could be reasonable over time.
Explore the SWS fair ratio for Unite Group.
Result: Price-to-sales of 5.3x (UNDERVALUED)
Still, revenue contraction of 4.1% and a reported net loss of £506.2m leave Unite Group exposed if investor patience with the student housing story shortens.
Find out about the key risks to this Unite Group narrative.
Another View: SWS DCF flags deeper upside
The P/S workup already points to value at Unite Group. The SWS DCF model goes further, with an estimated future cash flow value of £7.15 per share against a current price around £4.29. This frames the stock as materially undervalued on cash generation assumptions.
DCF models lean heavily on forecasts and discount rates, so the gap between price and value can close in more than one way. That raises the key question for you as an investor: which moves first, the cash flows or the share price?
Look into how the SWS DCF model arrives at its fair value.
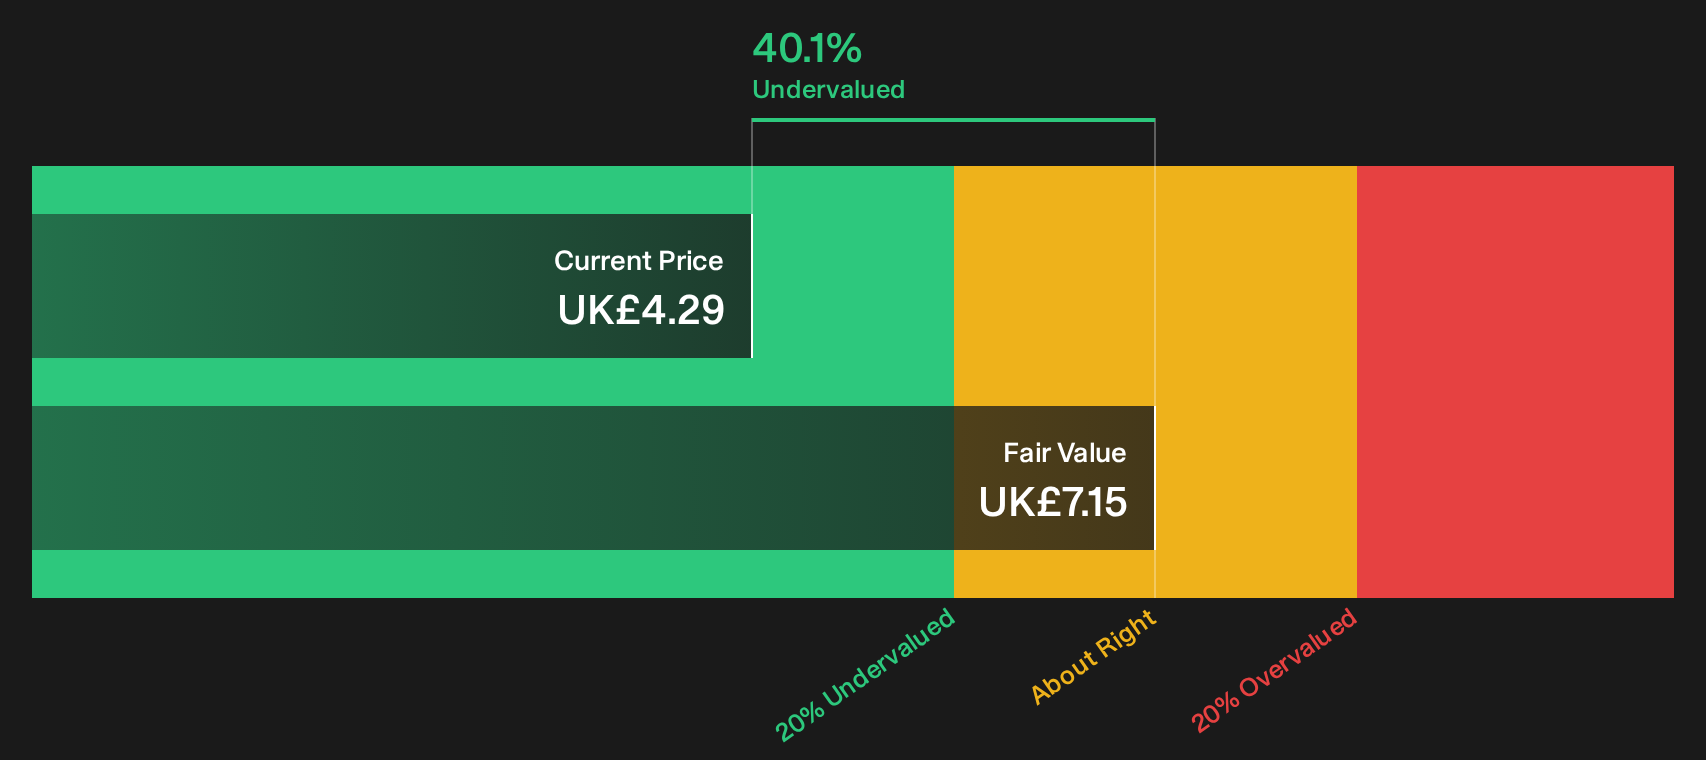
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unite Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Unite Group is pulled in two directions right now, with pressure on recent returns set against a long term student housing story that still appeals to some investors. Act before the next wave of headlines and run the numbers yourself by weighing up the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Unite Group?
If Unite Group has you thinking harder about risk, return, and timing, then broadening your opportunity set with a few focused stock shortlists can help you refine your next move.
- Target strong potential value setups by scanning companies on the 7 high quality undervalued stocks that combine quality fundamentals with prices that look out of sync with their underlying strength.
- Prioritise financial resilience by filtering for businesses in the list of solid balance sheet and fundamentals (9 results) so you are not caught out when conditions get tougher.
- Hunt for possible future market favourites early by checking the 5 high quality undiscovered gems before the crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com