
Shawbrook Group (LSE:SHAW) Stock May Still Trade At A Discount On Earnings
Shawbrook Group has seen its share price fall sharply this year, which naturally puts the focus on whether the current valuation can still be explained by its earnings power. With the stock under pressure, investors are asking if the market is recalibrating expectations or simply marking the shares down too far based on the profit profile of the business.
- The share price is down 40.1% year to date, which puts a lot of weight on the question of whether Shawbrook Group's earnings still justify even this lower level.
- The business model relies heavily on its ability to generate consistent profits from lending and related banking services, so any shift in margin quality or credit performance can materially affect what investors are willing to pay for those earnings.
- There is a second opinion on Shawbrook Group worth weighing. See what analysts think Shawbrook Group's shares could be worth.
The stock's next move may depend on whether Shawbrook Group's current earnings profile is strong enough to support the price that the market is assigning today.
If you want a broader watchlist while you assess whether Shawbrook Group's recent share price slump matches its earnings, you can use a focused screener of 7 high quality undervalued stocks.
Is Shawbrook Group Still Cheap on Earnings?
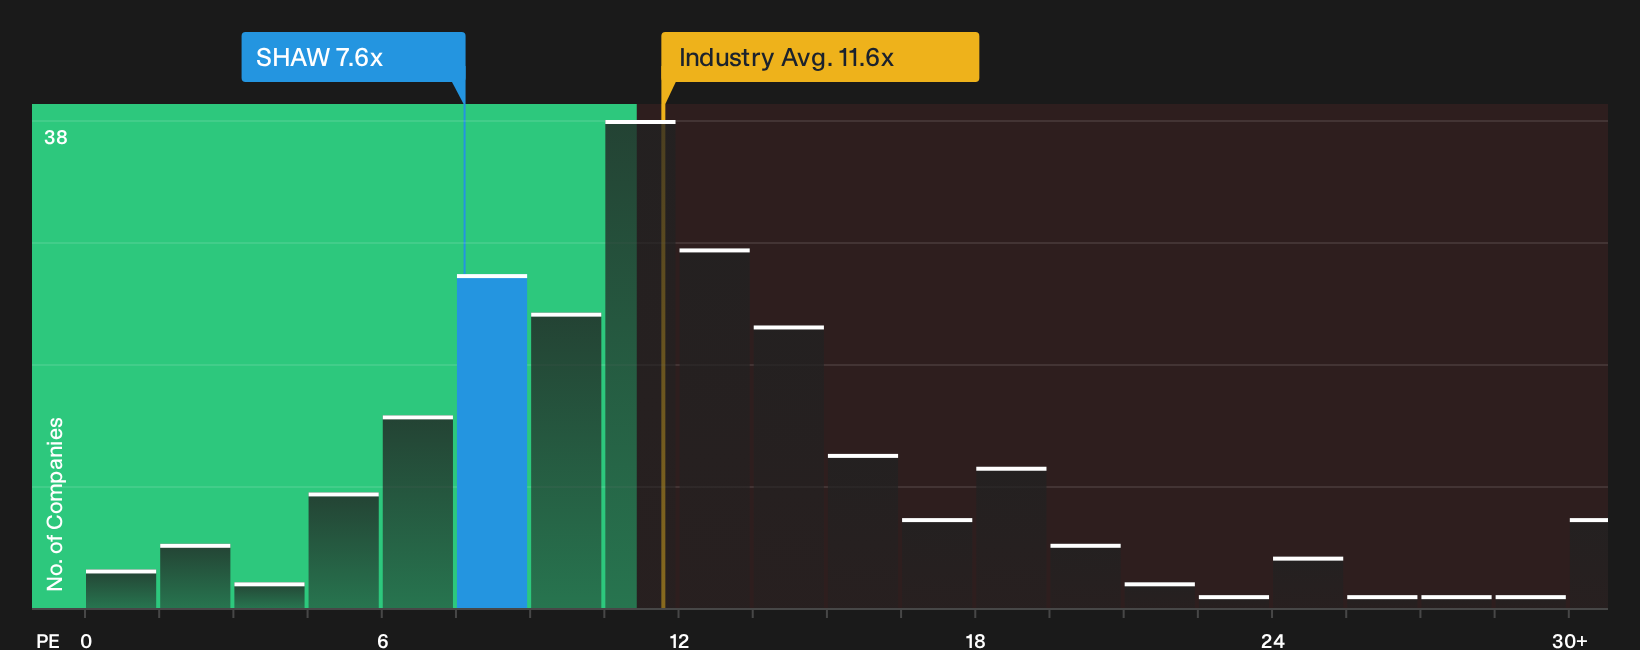
The P/E ratio works well for Shawbrook Group because earnings are the main driver of value for a lender built around interest income and fees. On this measure, the stock trades on about 7.6x, which is below both the wider Banks industry on roughly 11.1x and the peer set around 9.6x.
The in house fair P/E, which reflects Shawbrook Group's projected profitability, balance sheet profile and risk, points to a higher level than where the market currently prices the shares. That gap suggests the current multiple sits on the discounted side of what this framework would imply, so anyone assessing the recent sell off may see scope to question whether the earnings power is being underpriced. Explore the numbers behind Shawbrook Group's P/E valuation.
The Shawbrook Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where Shawbrook Group's valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today. Each narrative ties its number to a concrete view on how Shawbrook Group's profitability, efficiency and risk profile might evolve next, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on Shawbrook Group: 41% undervalued
"Years of technology and data investment of about £320m, and the current deployment of AI across underwriting, servicing and software development..."
Discover why this Narrative puts Shawbrook Group at 41% undervalued.
Shawbrook Group's valuation only makes sense if you know what could upset it
Price and earnings only tell part of the story for Shawbrook Group, because our broader review has surfaced specific pressure points that could matter a lot for anyone relying on those numbers. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com