
3 European Stocks Estimated To Be Trading At Discounts Of Up To 49.2%
The European stock market has recently experienced volatility, influenced by renewed Middle East tensions, a more hawkish stance from the European Central Bank, and mixed economic indicators across the eurozone. Despite these challenges, opportunities may exist for investors seeking undervalued stocks that could be trading at significant discounts. Identifying such stocks involves examining their intrinsic value relative to current market conditions and assessing whether they are positioned to withstand or benefit from prevailing economic trends.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTB (WSE:XTB) | PLN135.90 | PLN267.49 | 49.2% |
| Valmet Oyj (HLSE:VALMT) | €26.82 | €53.02 | 49.4% |
| PORR (WBAG:POS) | €30.35 | €60.22 | 49.6% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.89 | 49.4% |
| Lindab International (OM:LIAB) | SEK127.00 | SEK251.23 | 49.4% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.67 | €22.77 | 48.7% |
| ING Groep (ENXTAM:INGA) | €30.035 | €59.68 | 49.7% |
| Huuuge (WSE:HUG) | PLN23.45 | PLN45.98 | 49% |
| Grupa Pracuj (WSE:GPP) | PLN54.70 | PLN108.75 | 49.7% |
| Apator (WSE:APT) | PLN25.20 | PLN49.26 | 48.8% |
Let's take a closer look at a couple of our picks from the screened companies.
Embla Medical hf (CPSE:EMBLA)
Overview: Embla Medical hf, along with its subsidiaries, offers non-invasive orthopedic products across Europe, the Middle East, Africa, the Americas, and the Asia-Pacific with a market cap of DKK11.51 billion.
Operations: The company's revenue segments include Patient Care ($311.15 million), Prosthetics & Neuro Orthotics ($563.40 million), and Bracing and Supports including Compression Therapy (Phlebology) ($151.33 million).
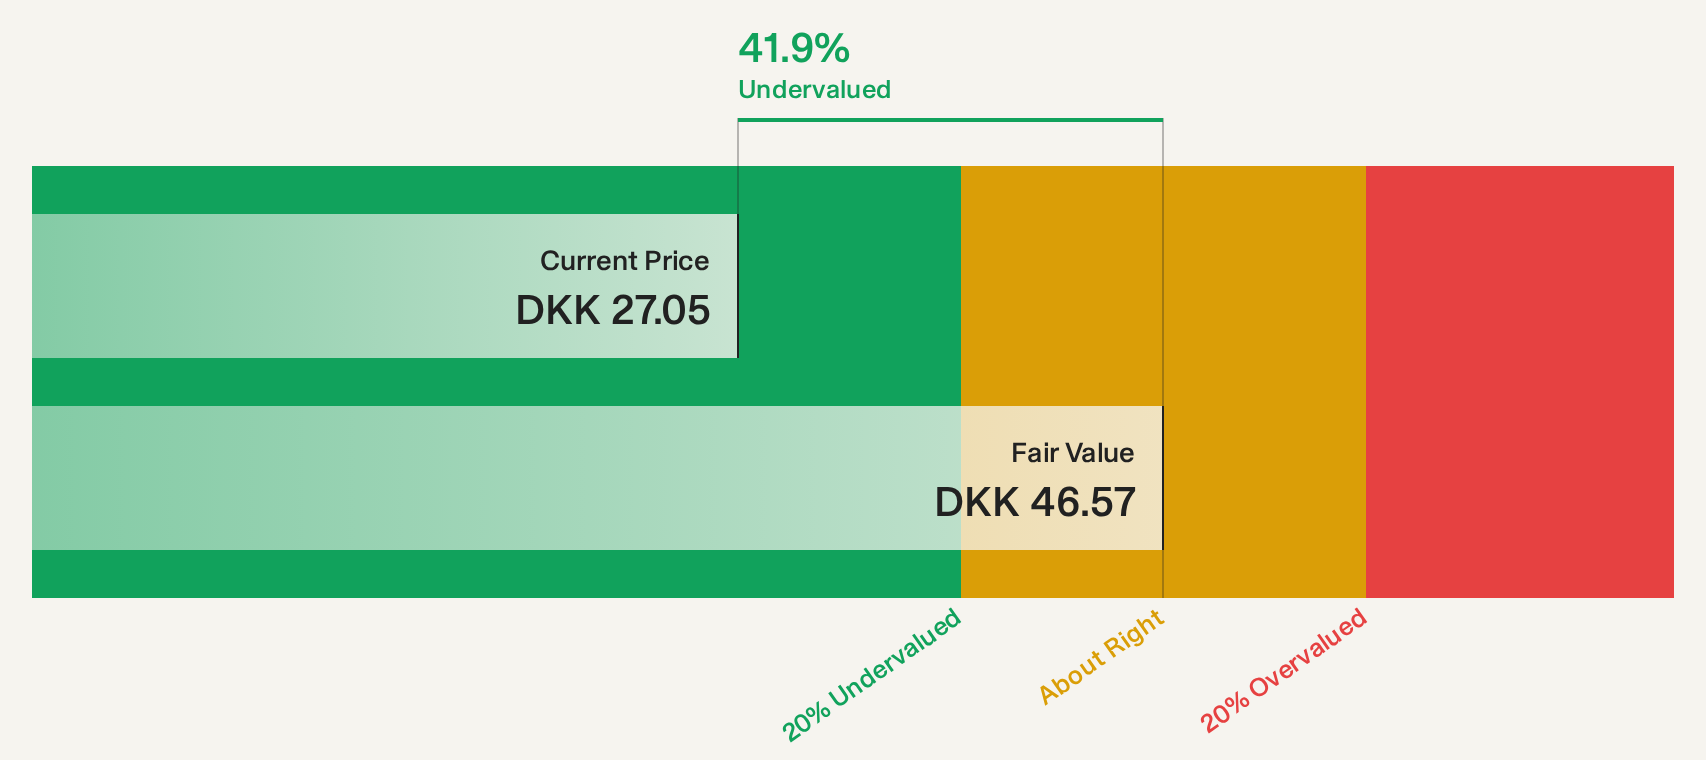
Estimated Discount To Fair Value: 37.5%
Embla Medical hf. is trading 37.5% below its estimated fair value, indicating it is significantly undervalued based on discounted cash flow analysis. Despite a moderate revenue growth forecast of 7.5% annually, which surpasses the Danish market average, Embla's earnings are expected to grow at a robust 11.6% per year, outpacing the market's growth rate of 7%. Recent share repurchase programs further enhance shareholder value by optimizing capital structure and potentially increasing future cash flows per share.
- In light of our recent growth report, it seems possible that Embla Medical hf's financial performance will exceed current levels.
- Click here and access our complete balance sheet health report to understand the dynamics of Embla Medical hf.
Vetoquinol (ENXTPA:VETO)
Overview: Vetoquinol SA is a veterinary pharmaceutical company that designs, develops, and sells veterinary drugs and non-medicinal products for cattle, pigs, dogs, and cats across Europe, the Americas, and the Asia Pacific region with a market cap of €872.82 million.
Operations: Vetoquinol's revenue is primarily derived from its Animal Health segment, which generated €527.34 million.
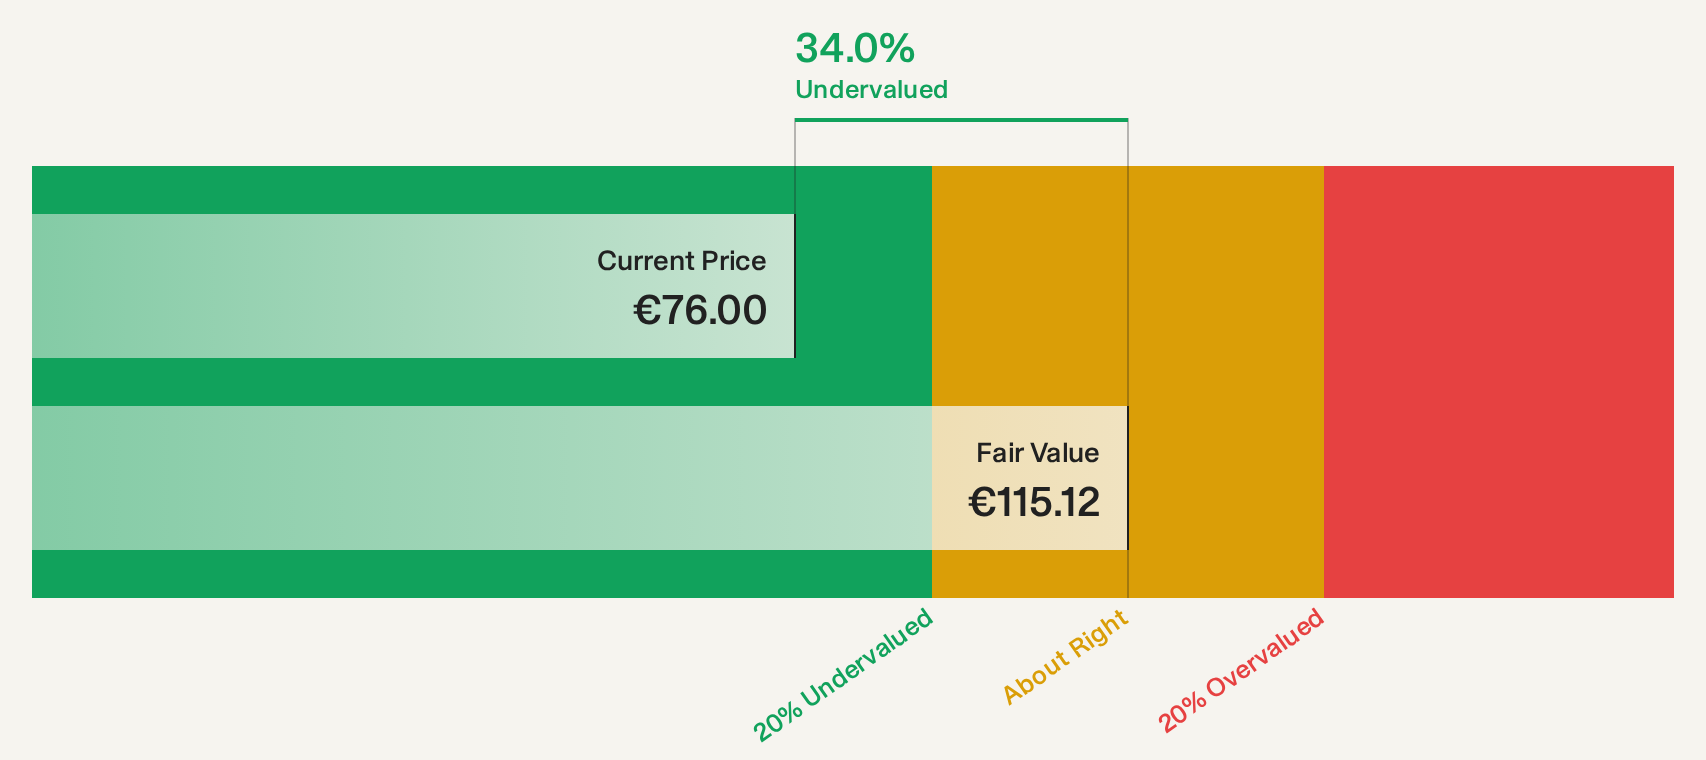
Estimated Discount To Fair Value: 34.8%
Vetoquinol is trading at €75.1, significantly below its future cash flow value of €115.12, highlighting its undervaluation potential. Despite a modest revenue growth forecast of 3.6% annually and earnings growth of 1.4%, both trailing the French market averages, the company has shown solid financial performance with recent net income rising to €30.55 million for the first half of 2026 from €25.08 million last year, enhancing its investment appeal based on cash flows.
- According our earnings growth report, there's an indication that Vetoquinol might be ready to expand.
- Unlock comprehensive insights into our analysis of Vetoquinol stock in this financial health report.
XTB (WSE:XTB)
Overview: XTB S.A. is a brokerage firm offering ETF, currency derivatives, commodities, indices, stocks, and bonds services across Central and Eastern Europe, Western Europe, Latin America, and the Middle East with a market cap of PLN15.98 billion.
Operations: XTB's revenue is primarily derived from its Retail Operations segment, which generated PLN3.00 billion, with an additional PLN64.12 million coming from Institutional Operations.
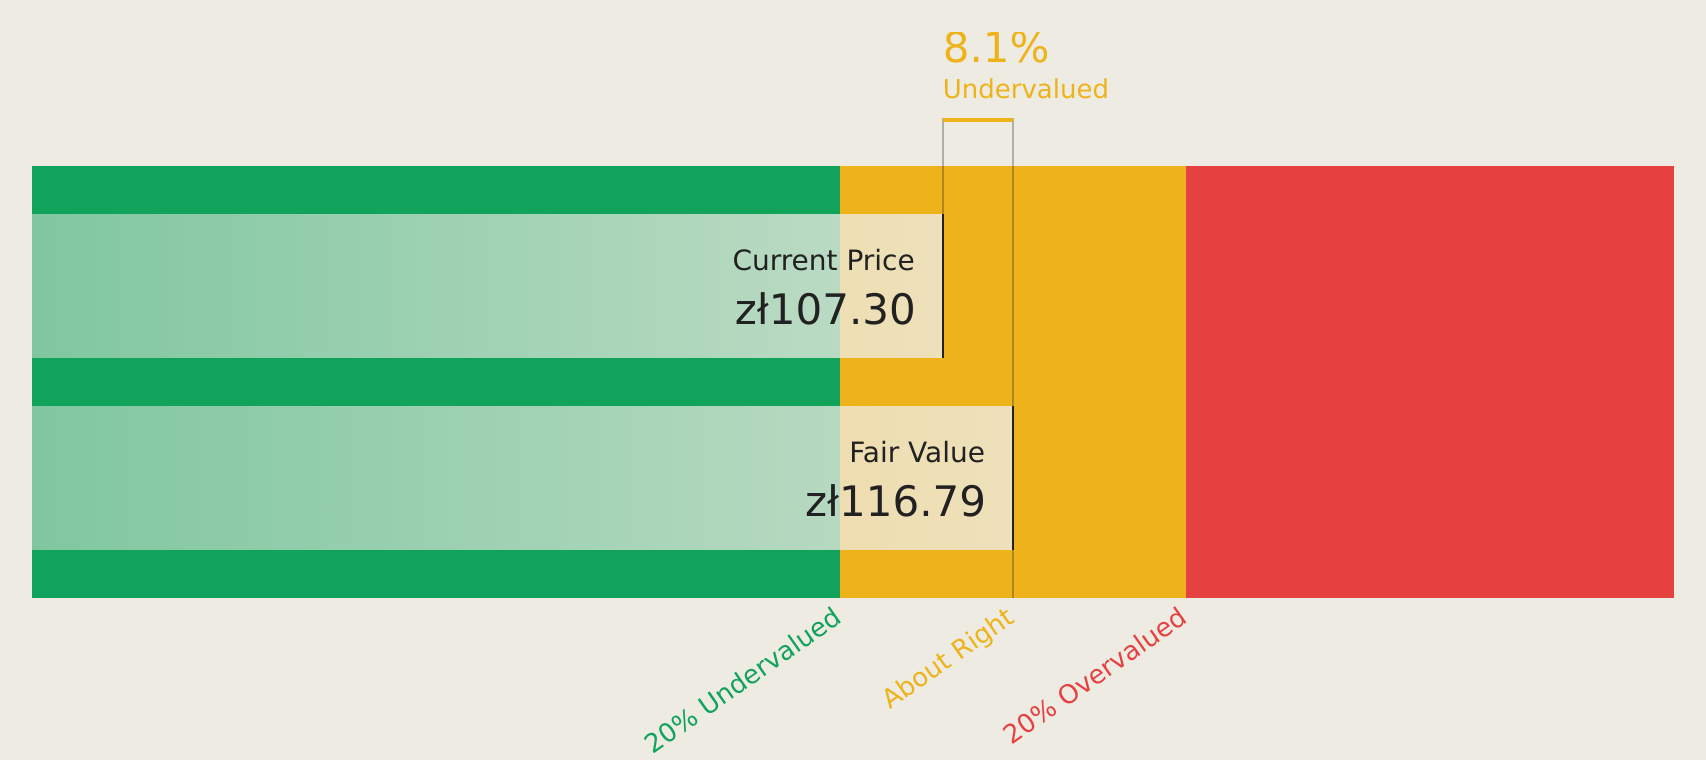
Estimated Discount To Fair Value: 49.2%
XTB is trading at PLN135.9, significantly below its estimated future cash flow value of PLN267.49, presenting an undervaluation opportunity. The company reported a substantial net income increase to PLN 1.03 billion for the first half of 2026 from PLN 410.05 million last year, despite earnings growth forecasts lagging behind the Polish market average at 6.7% annually. Revenue is expected to grow robustly by 14.1% per year, outpacing the broader market's growth rate.
- Our comprehensive growth report raises the possibility that XTB is poised for substantial financial growth.
- Navigate through the intricacies of XTB with our comprehensive financial health report here.
Summing It All Up
- Dive into all 68 of the Undervalued European Stocks Based On Cash Flows we have identified here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com