
China Tobacco International (HK) (SEHK:6055) Could Be 56% Below Fair Value Following Li Bin Appointment
China Tobacco International (HK) (SEHK:6055) has begun a new leadership chapter by appointing industry veteran Li Bin as chairman and non executive director, effective 30 September 2026.
Recent trading suggests some momentum returning to China Tobacco International (HK), with a 17.31% 90 day share price return and shorter term gains helping lift the stock to HK$23.72. However, the year to date share price return is still down 33.63% and the 1 year total shareholder return has declined 42.72%, even after a very large 3 year total shareholder return of about 14x and a 5 year total shareholder return of 43.31% that keep longer term holders well ahead overall.
Scan how China Tobacco International (HK) compares with other hand picked consumer and export focused plays by running your eye over the 620 high quality undiscovered gems in this corner of the market.
China Tobacco International (HK) has rebounded to HK$23.72, while still trading at a sizeable gap to both analyst targets and intrinsic models. Where does fair value really sit inside that spread?
Price-to-Earnings of 18.2x: Is it justified?
On a simple snapshot, China Tobacco International (HK) trades on a P/E of 18.2x, which leaves the stock looking expensive compared to both its fair ratio and its industry, even at the current HK$23.72 share price.
The P/E ratio compares what investors are paying today to the earnings the business generates per share. For a tobacco exporter and distributor like China Tobacco International (HK), this measure is often used as a shorthand for how the market is weighing the reliability of profits against growth expectations.
Internal fair value work suggests a P/E closer to 10.8x would line up with the company’s earnings profile. The present 18.2x multiple therefore implies investors are paying a much richer price than that reference level. Against the Asian Retail Distributors industry average of 16.9x, the stock also carries a premium, which points to the market assigning stronger expectations than both the sector and the fair ratio might support.
Explore the SWS fair ratio for China Tobacco International (HK).
Result: Price-to-Earnings of 18.2x (OVERVALUED)
Still, China Tobacco International (HK) faces potential pressure from tighter tobacco regulation and any slowdown in key import and export regions that drive its segment revenue mix.
Find out about the key risks to this China Tobacco International (HK) narrative.
Another View: DCF Points The Other Way
The multiple story around China Tobacco International (HK) paints the stock as expensive, yet the SWS DCF model tells a different tale. On that approach, HK$23.72 sits roughly 56% below an estimated cash flow value of HK$54.14, which raises a simple question: is the risk really in paying up today or in assuming those cash flows never materialise?
Look into how the SWS DCF model arrives at its fair value.
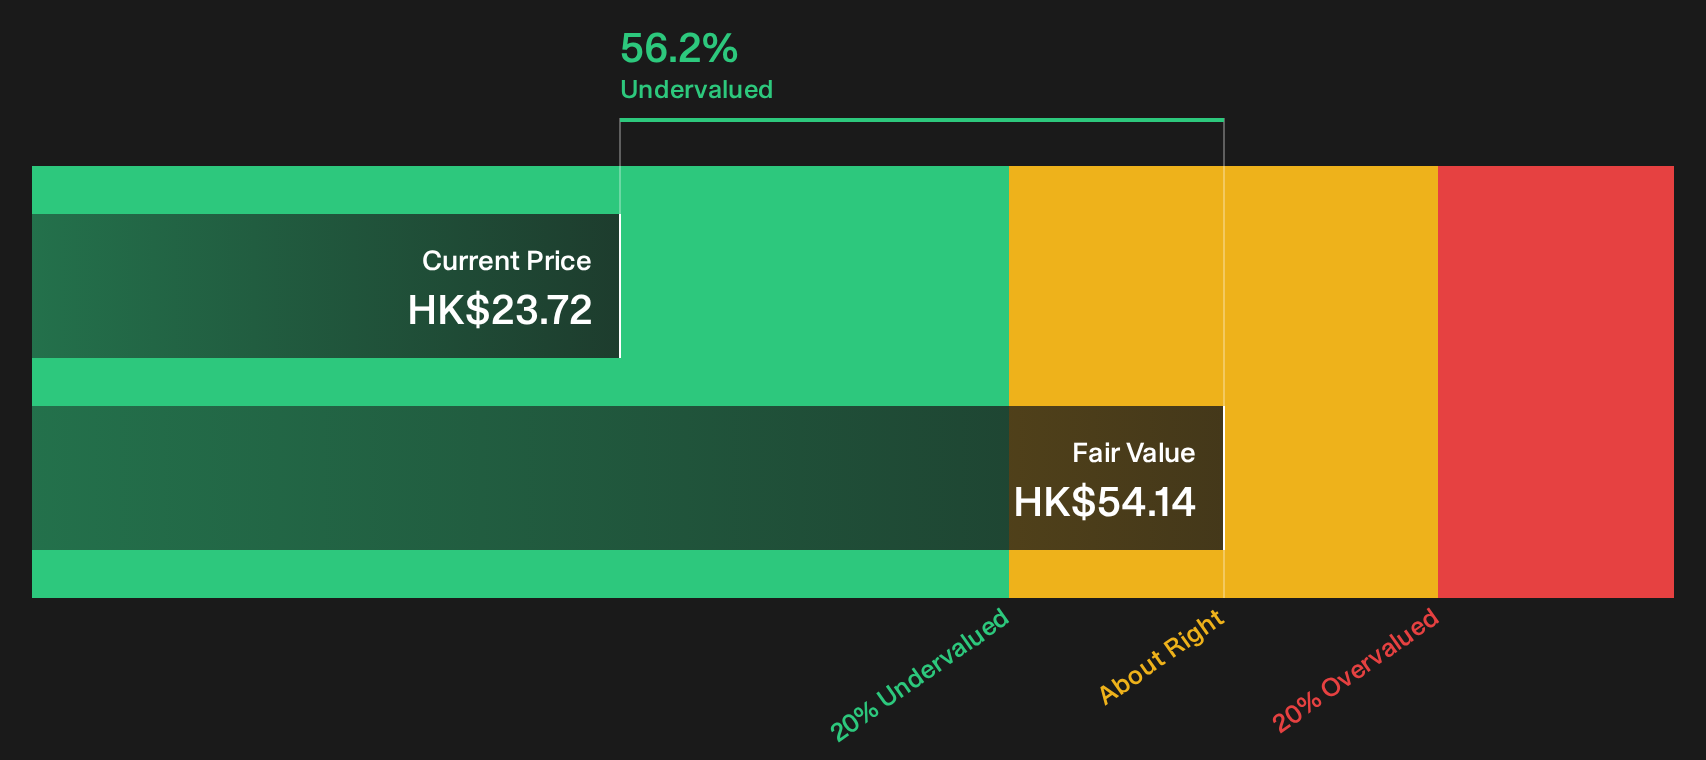
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Tobacco International (HK) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mixed signals around China Tobacco International (HK)? Move fast, review the same numbers, and test whether the optimism around its 3 key rewards
Looking for more investment ideas beyond China Tobacco International (HK)?
If China Tobacco International (HK) has sharpened your focus on pricing, cash flows and risk, do not stop here. A few targeted screens can surface other companies that better match your return goals and risk comfort in minutes.
- Spot opportunities that the crowd has not fully priced by reviewing a 620 high quality undiscovered gems that couples strong fundamentals with quieter market attention.
- Tilt your watchlist toward resilience by scanning a 227 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier historical risk profiles.
- Anchor your income ideas with quality by checking a 219 dividend fortresses built around higher yields paired with underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com