
Should Raised Guidance Require Action From Healthpeak Properties (DOC) Investors?
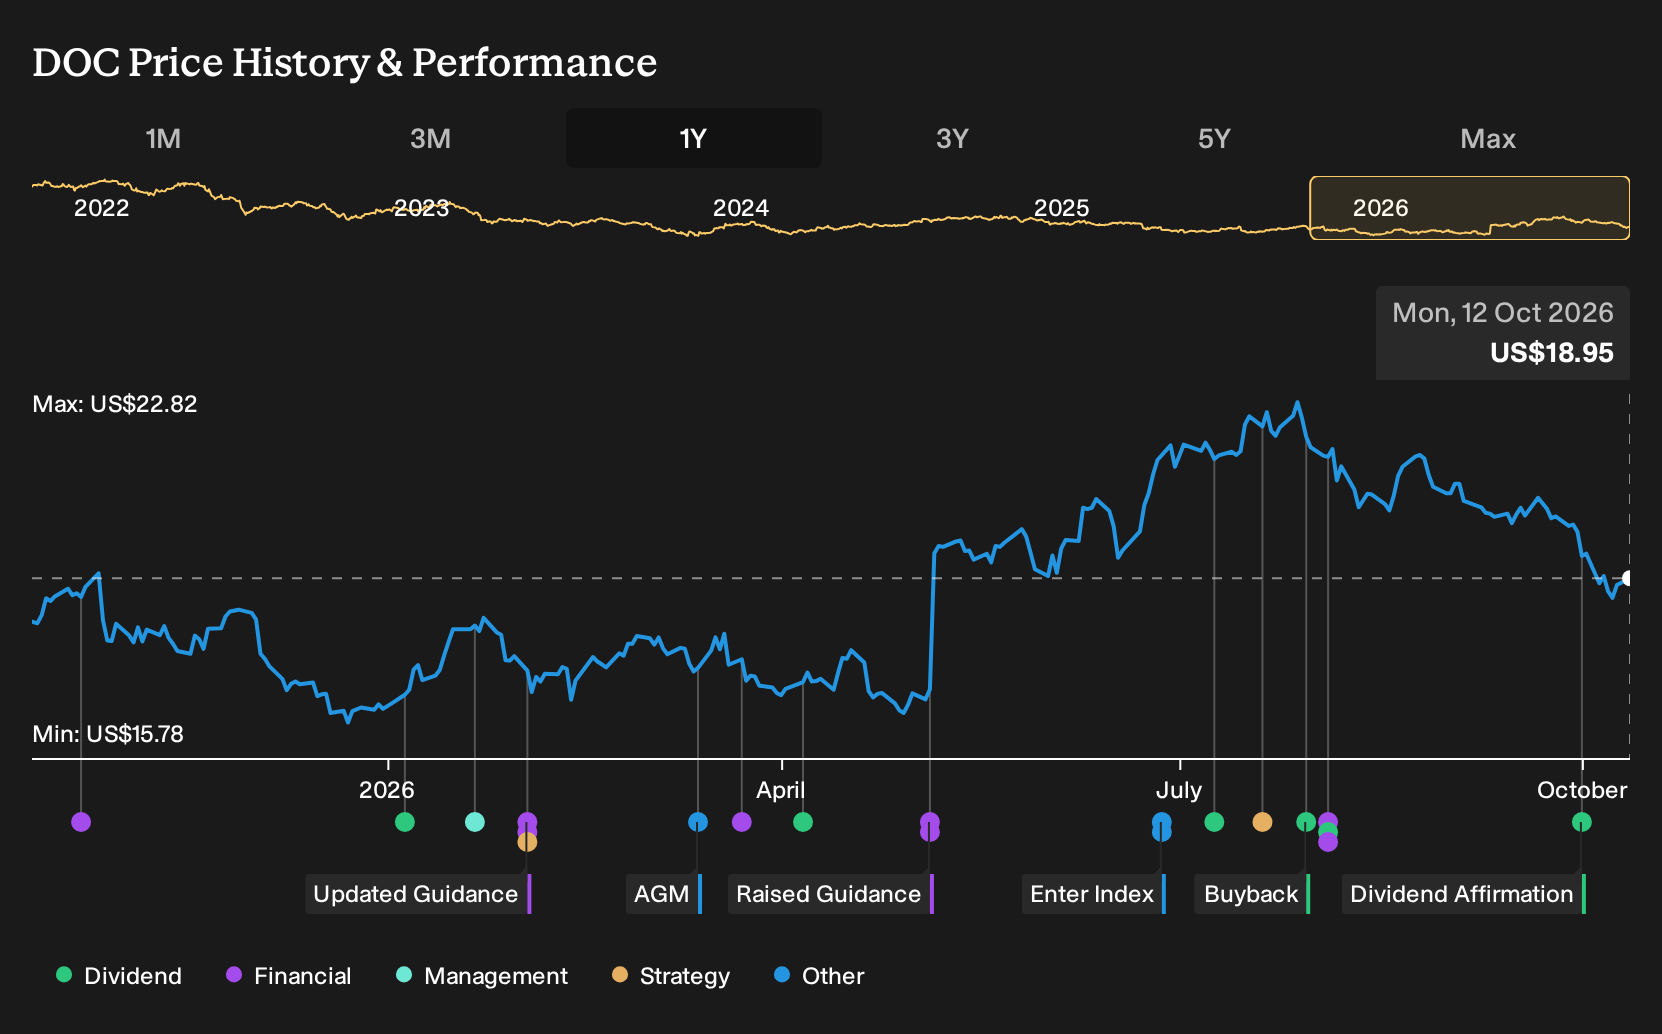
- Healthpeak Properties, Inc. declared a monthly common stock cash dividend of $0.10167 per share for the fourth quarter of 2026, with record dates in October, November and December and corresponding payment dates later each month, which reflects an annualized dividend amount of $1.22 per share.
- Management backed this payout with raised full-year 2026 guidance after a solid second quarter and an improved 72% dividend payout ratio supported by higher AFFO, even as the balance sheet carries pressure from a relatively low 1.5x interest coverage ratio and ongoing debt considerations.
- We will examine how Healthpeak Properties' investment narrative is shaped by the raised 2026 guidance alongside the reaffirmed monthly dividend cadence.
Compare Healthpeak Properties' 6.7% monthly dividend yield with other income ideas by scanning our hand-picked 8 dividend fortresses, which may suit a similar cash flow mindset.
Healthpeak Properties Investment Narrative Recap
To own Healthpeak Properties, you need to buy into a fairly simple story. The REIT leans on steady demand for outpatient medical buildings, life science labs and senior housing, with demographic trends and outpatient surgery growth as the key drivers. The raised 2026 FFO as Adjusted guidance supports that operating thesis and is consistent with the decision to keep a monthly dividend cadence.
The near term swing factor is execution in labs and medical office leasing, as well as keeping portfolio occupancy resilient while capital markets remain choppy. The biggest current pressure point is financial, not operational. A 1.5x interest coverage ratio leaves less room if refinancing costs stay elevated or if tenant issues require heavier capex.
The October 1 dividend declaration for the fourth quarter looks most relevant here because it indicates that Healthpeak Properties is still prioritizing a regular cash return alongside its operating plan. Management is signaling that a 6.7% yield and a US$1.22 annualized payout remain aligned with current AFFO and the 72% dividend payout ratio reported for fiscal 2025.
That said, the dividend sits on top of a balance sheet where earnings-based coverage of interest is already tight and analysts see some pressure on AFFO in 2026. For investors, the key question is whether the lab acquisition strategy and outpatient demand can offset higher financing costs and any biotech tenant stress sufficiently to keep that monthly dividend compatible with long term reinvestment needs.
Healthpeak Properties' current analyst story points to US$3.5b in revenue and US$148.5m in earnings by 2029, based on assumed yearly revenue growth of 6.3% and an earnings decline of about US$94m from US$242.7m today.
Uncover why Healthpeak Properties' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Healthpeak Properties focuses on refinancing risk rather than occupancy. The most bearish analysts were expecting revenue of about US$3.3b and earnings of roughly US$42.3m by 2029, far below consensus. That paints a sharply more cautious earnings story. Both narratives were built before this dividend affirmation, so you may see them shift.
Explore 4 other Healthpeak Properties fair value estimates, including one that suggests it could be worth just $21.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Healthpeak Properties research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Healthpeak Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Healthpeak Properties' overall financial health at a glance.
Looking for more investment ideas beyond Healthpeak Properties?
If Healthpeak Properties has your attention but you want a broader watchlist, consider using this moment to widen your opportunity set with a few focused stock screens that match different risk and income preferences.
- If capital preservation sits high on your list, start with companies that pair steadier financial profiles with measured risk using our 31 resilient stocks with low risk scores.
- If you prefer cash flow today, focus on income opportunities that prioritize stronger yields with our hand picked 8 dividend fortresses.
- If you want potential upside from businesses that are not yet widely followed, scan the 20 high quality undiscovered gems and see which fundamentals appeal most to you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com