
Safestore Holdings (LSE:SAFE) After The Sell Off Is The Valuation Case Changing
Safestore Holdings (LSE:SAFE) has come back into focus after a share price decline of about 7% over the past month and roughly 16% over the past 3 months, which has sharpened questions around valuation and business resilience.
That near term weakness follows a much tougher stretch for Safestore Holdings, with the share price down about 31% year to date and the 1 year total shareholder return declining roughly 27%. This signals fading momentum as investors reassess both growth prospects and risk.
Contrast Safestore Holdings' slide with a curated set of resilient real estate and income plays by scanning our 1 dividend fortresses, which have held up better through recent volatility.
Safestore Holdings now trades well below recent levels after a steep slide, which raises a practical choice for investors. Is this enough of a reset to justify stepping in now, or is patience on price still worth more?
Preferred P/E of 16.8x: Is it justified?
On conventional metrics, Safestore Holdings does not look cheap. The shares trade on a P/E of 16.8x, while the stock has already sold off sharply over the past year, which puts the focus squarely on whether earnings expectations genuinely support that richer label compared to peers.
The P/E multiple measures how much investors are currently willing to pay for £1 of earnings. For a self storage REIT such as Safestore Holdings, that figure effectively reflects what the market is willing to pay for a mix of income, future cash flow potential and perceived resilience of the storage portfolio across the UK and continental Europe.
Here the market is attaching a clear premium. Safestore Holdings trades on 16.8x earnings compared with a peer average of 10.6x and a global specialized REITs average of 15.2x. The company also scores as expensive against an estimated fair P/E of 15.9x, suggesting the current ratio sits above a level the market could move towards if sentiment cools.
Explore the SWS fair ratio for Safestore Holdings.
Result: Price-to-Earnings of 16.8x (OVERVALUED).
Still, the premium around Safestore Holdings could unwind quickly if self storage demand softens, or if interest costs stay higher for longer and pressure valuations.
Find out about the key risks to this Safestore Holdings narrative.
Another View: DCF Points the Other Way
There is a sharp contrast once you shift from the P/E lens to the SWS DCF model. On that framework, Safestore Holdings at about £5.01 is trading roughly 54.5% below an estimated future cash flow value of £11, which frames the recent sell off as a possible mispricing rather than excess.
Our DCF model pushes you to ask a different question. Is the earnings based premium really the issue, or is the bigger call whether you trust those long term cash flow assumptions enough to lean into a wide gap like this Look into how the SWS DCF model arrives at its fair value.
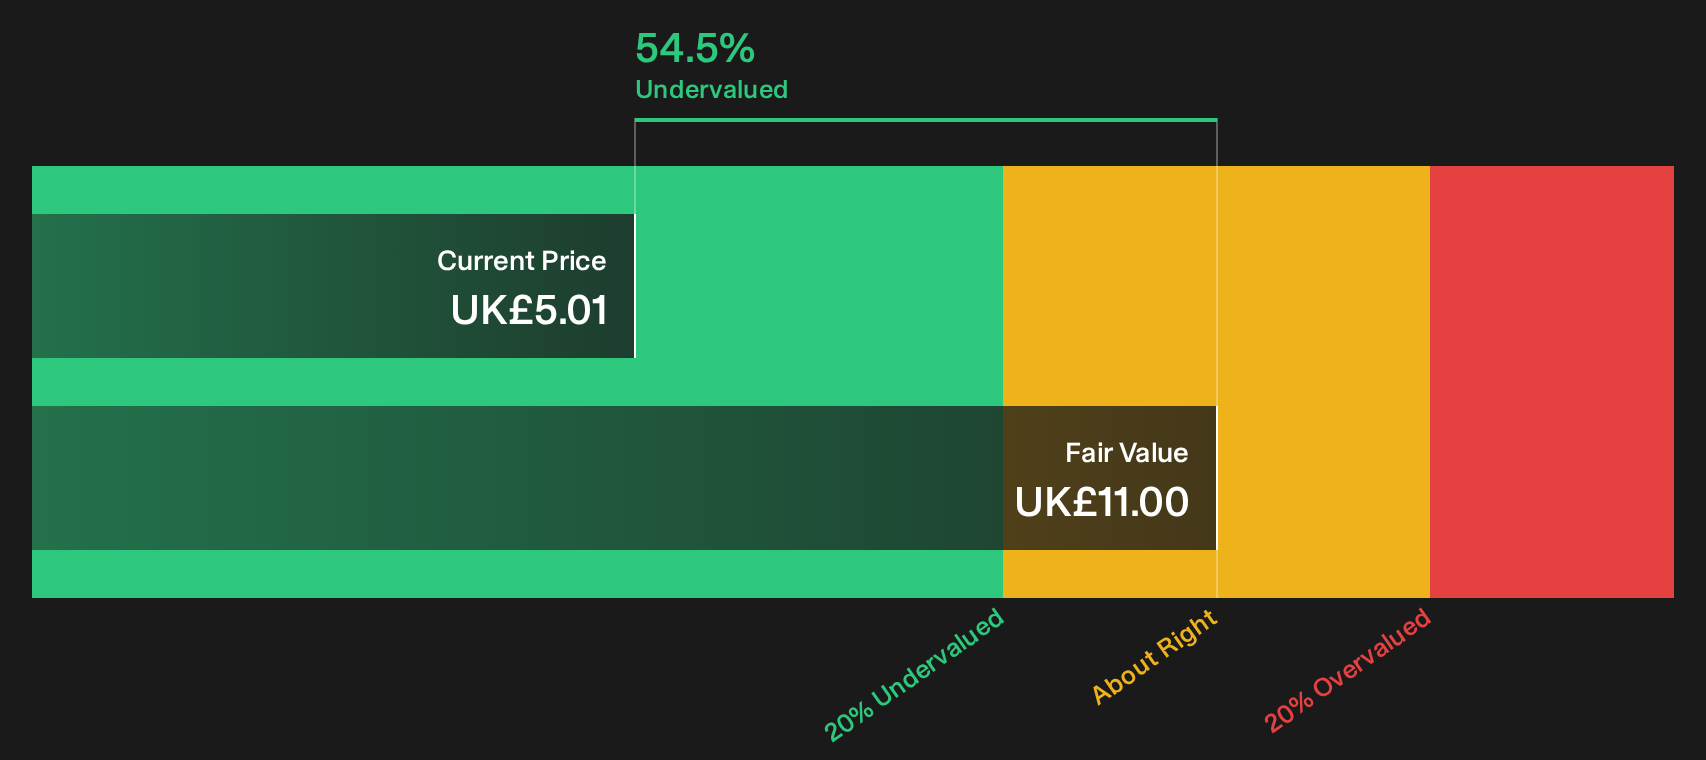
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Safestore Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Safestore Holdings' value case. That is exactly why you might want to move quickly and inspect the underlying numbers, weigh both the concerns and the upside, then judge the 3 key rewards and 3 important warning signs
Looking for more Safestore Holdings sized investment ideas?
If Safestore Holdings has you rethinking where to put fresh capital, use this moment to widen your watchlist with a few focused stock shortlists.
- Target resilient value by checking companies that pair quality fundamentals with subdued valuations through the 7 high quality undervalued stocks.
- Strengthen portfolio stability by scanning a list of solid balance sheet and fundamentals (9 results) that can help cushion future shocks across different market conditions.
- Get ahead of the crowd by reviewing 5 high quality undiscovered gems before wider attention starts to price in their potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com