
Here's What to Expect From Republic Services’ Next Earnings Report
Republic Services, Inc. (RSG) is a leading environmental services provider focused on waste management and recycling. With a market cap of nearly $66.4 billion, its operations span the collection, processing, transportation, and disposal of residential, commercial, industrial, and hazardous waste, complemented by landfill management, recycled material sales, organic waste treatment, and container rentals.
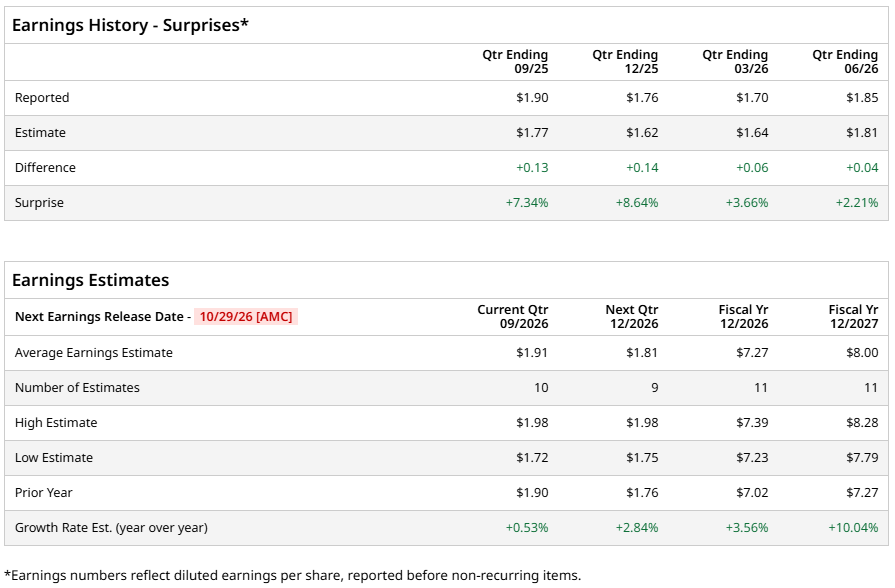
Headquartered in Phoenix, Arizona, the company is scheduled to report its Q3 FY2026 financial results after the market closes on Thursday, Oct. 29. Analysts expect diluted EPS of $1.91, edging past the $1.90 recorded in the year-ago quarter. Republic Services has also beaten earnings estimates in each of the past four quarters, giving a solid track record to consider.
Looking further ahead, Wall Street projects diluted EPS of $7.27 for full-year FY2026, translating into year-over-year (YOY) growth of 3.6%. Expectations strengthen in FY2027, with the bottom line forecasted to reach $8, representing a 10% increase from the preceding year.
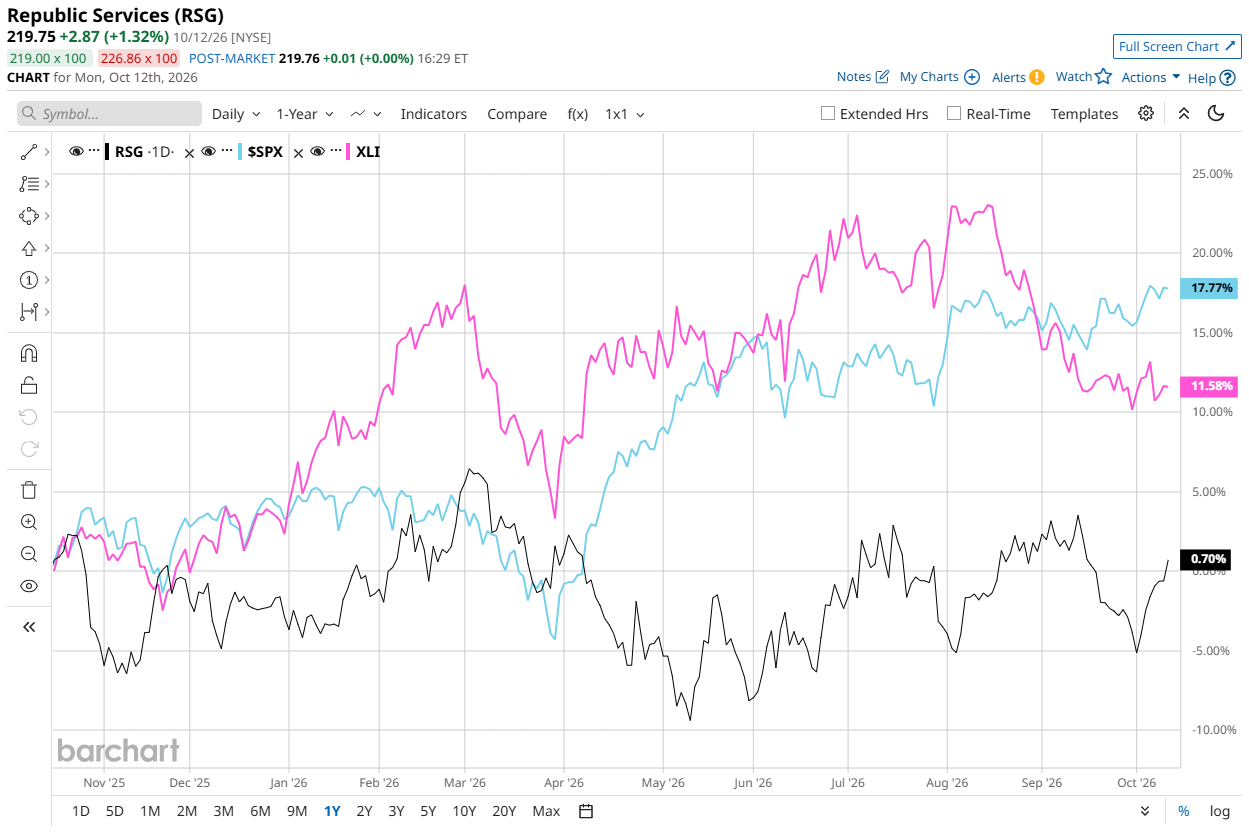
Despite its consistent earnings performance, Republic Services’ shares have declined 2.4% over the past 52 weeks, trailing the S&P 500 Index ($SPX), which climbed 19.2% in the same stretch. The picture is somewhat brighter in 2026, with the stock gaining 3.7%, although it remains behind the benchmark’s jump of 14.1%.
The broader industrial sector has delivered stronger returns as well, with the State Street Industrial Select Sector SPDR ETF (XLI) rising 12.8% over the past 52 weeks and adding 9% in 2026.
Recent trading has reflected a tug-of-war between the company’s pricing strength and mounting operating pressures. Q2 FY2026 revenue grew 4.6% YOY, but volumes slipped 1.6%, while elevated fuel, labor, and transportation expenses weighed on margins. Softer recycling commodity prices added another hurdle. However, earnings growth and improved guidance helped steady investor sentiment.
Adjusted EPS increased 4.5% YOY. With pricing gains outpacing cost inflation, Republic Services also raised its 2026 outlook, lifting its original revenue guidance to a range of $17.2 billion to $17.3 billion. Its guidance for adjusted diluted EPS was also revised upward to $7.23 to $7.28.
Against this backdrop, Wall Street maintains an overall “Moderate Buy” rating on RSG stock. Of the 26 analysts covering the name, 12 recommend “Strong Buy,” two assign “Moderate Buy,” and the remaining 12 maintain “Hold” ratings.
To that end, the average price target stands at $248.22, suggesting potential upside of 13%, while the Street-High target of $281 points to a gain of 27.9% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.