
How Investors May Respond To DoorDash (DASH) Deliveroo Integration Questions
- DoorDash rolled out DashOS for restaurants, new AI tools for Dashers, a corporate ordering connector, expanded retail partnerships, and a DoorDash Air drone system, all aimed at tying together ordering, loyalty, delivery modes, and workplace use on a single platform.
- The push to link marketplace orders, direct channels, retail partners, and corporate agents into one data and fulfillment spine signals DoorDash’s attempt to make its logistics and software stack more valuable than any single delivery product.
- We will look at how DoorDash’s broader logistics and software ambitions interact with these AI driven tools and platform expansions.
Scan how DoorDash’s platform push compares with other delivery and retail logistics plays by zeroing in on 92 AI infrastructure stocks that could be building similar data and fulfillment rails.
DoorDash Investment Narrative Recap
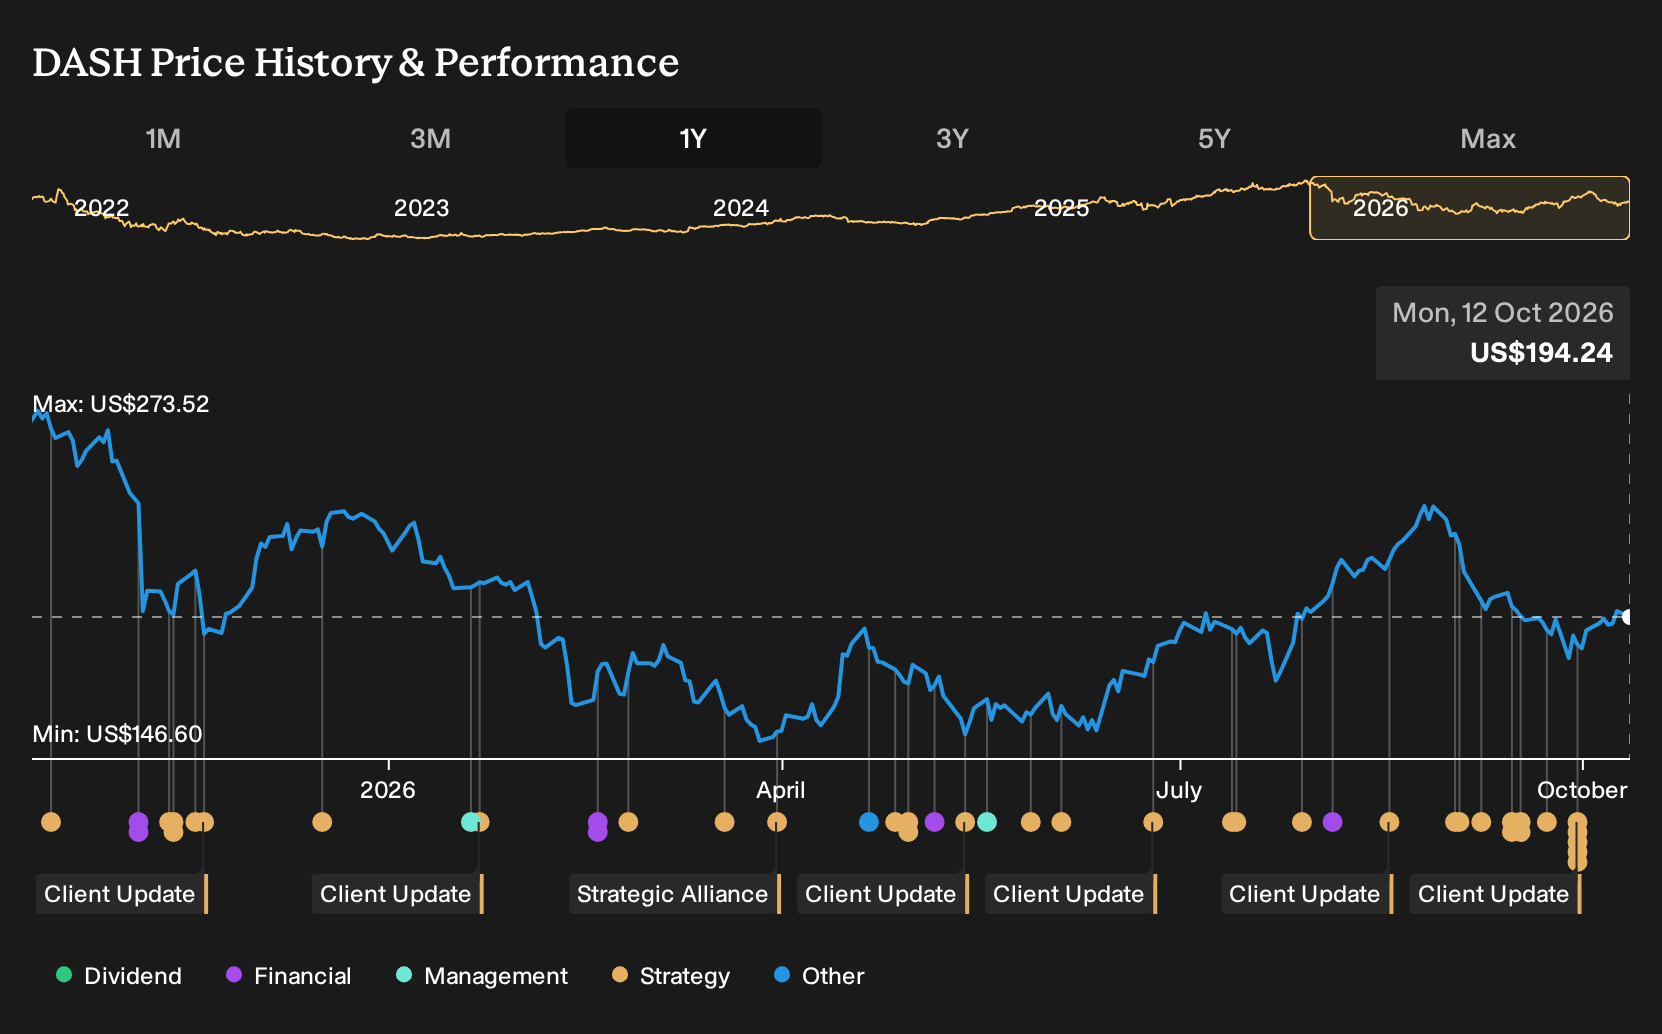
Owning DoorDash means believing the platform can turn strong revenue momentum and heavy product investment into durable earnings, even with the share price down 13.2% in 2026. In the near term, the key question is whether grocery, retail, Deliveroo integration and subscriptions can keep pulling more orders and higher margin services onto a single operating spine.
The biggest risk right now is cost pressure from regulation and Dasher support programs, occurring at the same time that management is spending on AI, autonomy and international expansion. September’s product flurry supports long term positioning but does not clearly change short term sensitivity to legal outcomes, fuel rewards and affordability in online grocery.
Among the announcements, DashOS looks most relevant to the current thesis around higher margin software, ads and subscriptions. DoorDash is trying to connect marketplace demand, direct ordering, loyalty and reservations into one system that lets restaurants act on their own customer data without replacing existing point of sale tools.
If DashOS gains traction, it could support several existing catalysts at once. Better visibility into guest behavior can support targeted promotions, more effective advertising for merchants and potentially stickier DashPass-style memberships. Execution risk is significant, because adoption depends on operators accepting deeper integration while DoorDash already faces scrutiny on costs and pricing.
DoorDash's narrative projects US$28.0b revenue and US$3.8b earnings by 2029. That path assumes 20.8% yearly revenue growth and an earnings increase of about US$3.0b from US$841.0m today.
Uncover why DoorDash's fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view zooms in on autonomy as the real swing factor for DoorDash. The most optimistic analysts were already penciling in US$31.9b of revenue and US$5.4b of earnings by 2029, before DashOS and DoorDash Air entered the picture. It is possible that this new AI and drone initiative could influence those forecasts, either reinforcing or challenging them, so it may be useful to weigh several narratives before forming a view on the stock.
Explore 7 other DoorDash fair value estimates, including one that suggests as much as 127% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DoorDash research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DoorDash. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DoorDash's overall financial health at a glance.
Looking For More Investment Ideas Beyond DoorDash?
Once you have a view on DoorDash, it can help to line it up against other opportunities so you can decide where your next dollar of risk really belongs.
- For investors who want potential upside but still care about financial strength, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If you prefer opportunities that the market may be underpricing based on fundamentals, scan through a 29 high quality undervalued stocks that might fit your return targets.
- Those who lean toward stability and income can focus on cash returns by reviewing a curated 8 dividend fortresses that already meet a 5%+ yield hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com