
Learn Why The Bull Case For BAE Systems Stock Could Change Following New Defense Systems Launch
- BAE Systems has recently unveiled its MDACS artillery system and HPM directed energy weapon for counter drone and missile defence, alongside fresh U.S. contracts for F 35 electronic warfare suites, amphibious vehicle recovery variants and M Code GPS upgrades.
- The mix of advanced counter UAS technology, secure microelectronics collaboration and long dated amphibious and aviation contracts points to BAE Systems focusing further on high complexity, higher value defence electronics and systems integration work with extended production visibility.
- We will now look at how BAE Systems' investment narrative could be influenced by its new counter drone technologies and contract wins.
BAE Systems Investment Narrative Recap
To own BAE Systems you need to believe that high complexity defense electronics, secure microelectronics and long visibility platforms can keep driving the business, even as ESG pressure and political risk around defense budgets linger in the background. The key near term swing factor remains how efficiently that £75b backlog converts into revenue and cash, not any single product reveal.
The recent MDACS and HPM news mainly reinforces the story rather than rewriting it. It points to more exposure to drones, munitions and electronic warfare, but capacity constraints, supply chain strain and reliance on a few large government customers still look like the biggest operational risks in the short run.
The F-35 electronic warfare contract for Lots 20 to 22, plus retrofit work, feels closest to the MDACS and HPM announcement from an investor angle. It underlines that BAE Systems is not just pitching new counter drone concepts. It is already embedded on a flagship combat aircraft program that needs high performance electronic protection today.
For catalysts, that F-35 win matters because it leans into the same thesis as the new C-UAS systems. More content in electronic warfare, a long production tail and modernization of earlier jets all support the Electronics segment, where execution, automation and supply chain resilience will decide how much of the reported demand turns into margins and cash generation.
BAE Systems' narrative projects £38.7b revenue and £3.0b earnings by 2029. This assumes 10.9% yearly revenue growth and an earnings increase of about £0.9b from £2.1b in the current period.
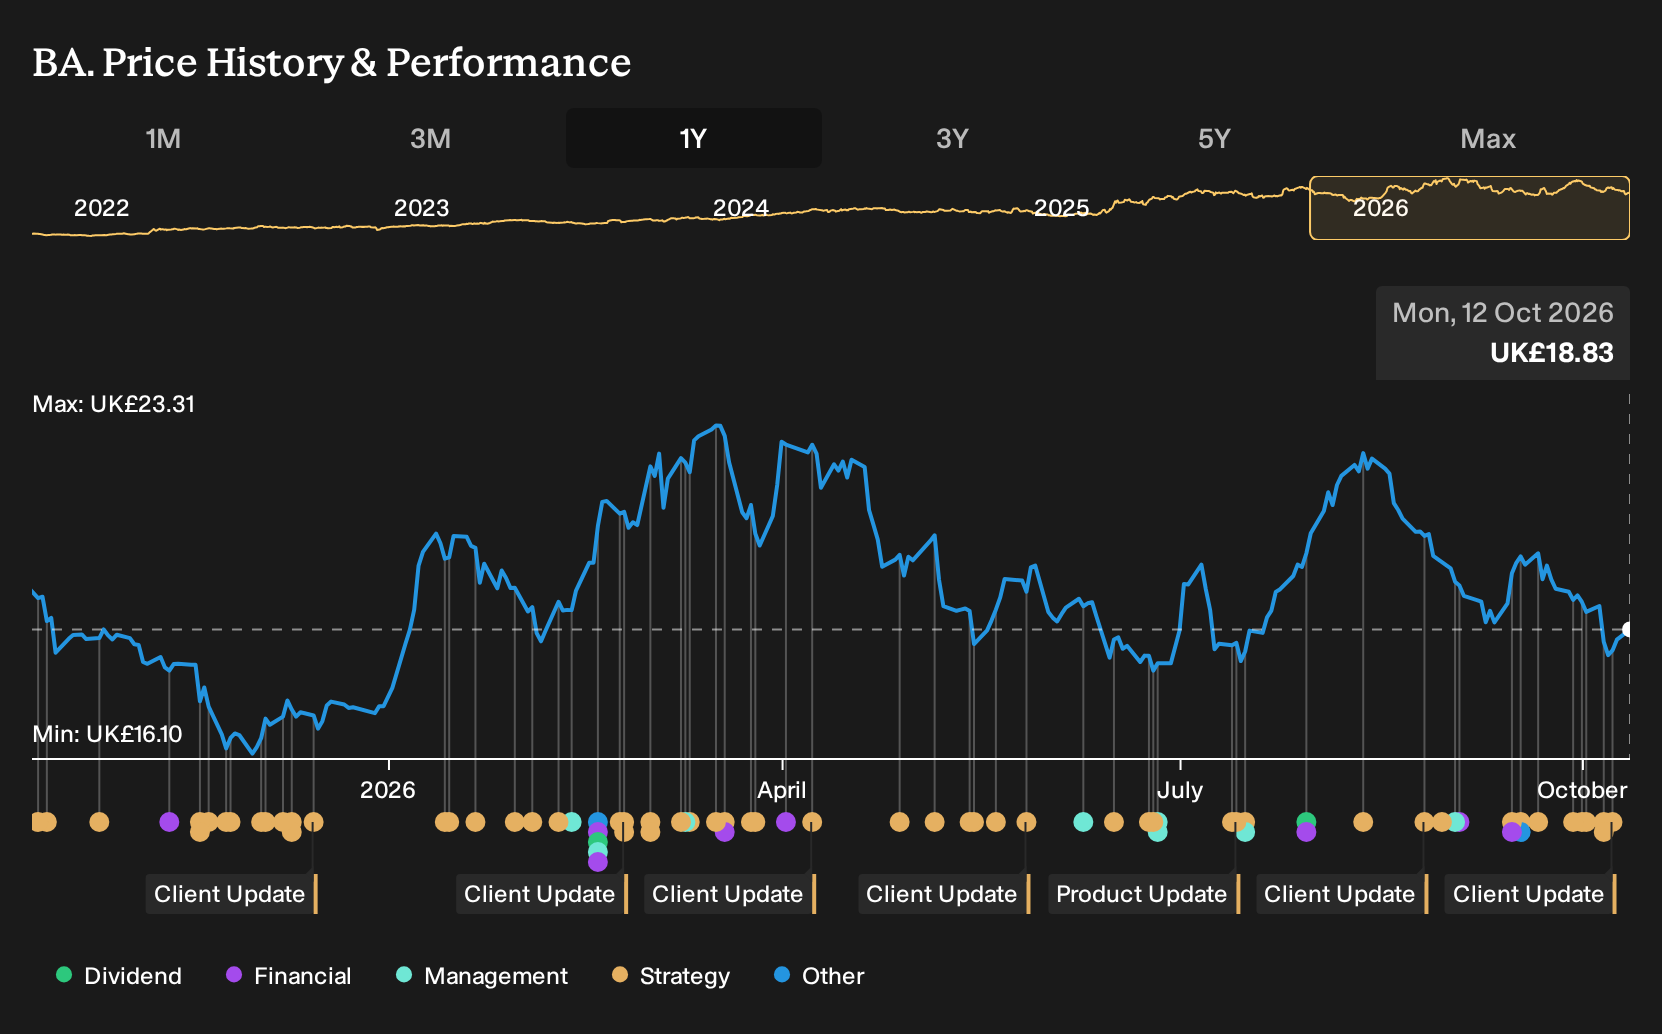
Uncover how BAE Systems' fair value indicates a 23% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view zooms in on valuation risk rather than technology upside. The most cautious BAE Systems analysts were working off roughly £39.2b of 2029 revenue and £3.0b of earnings, paired with a lower 23.8x P/E and a price target near £18.53. That is a much cooler story on execution. These pre news forecasts could shift if MDACS and HPM reshape expectations.
Explore 4 other BAE Systems fair value estimates, including one that suggests it could be worth just £23.22!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BAE Systems research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for BAE Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BAE Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond BAE Systems?
If the BAE Systems story has sharpened your view on defense and advanced electronics, it can help to widen the lens and see how other businesses stack up on quality, value and resilience using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, check out a curated set of 7 high quality undervalued stocks, which pair strong fundamentals with more modest pricing.
- If capital preservation and smoother portfolio swings matter most to you, focus on companies from our 4 resilient stocks with low risk scores to see which businesses carry lower risk scores.
- When balance sheet strength is non negotiable, scan the list of solid balance sheet and fundamentals (9 results) to find firms with cleaner debt profiles and sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com