
Weyerhaeuser’s Q3 2026 Earnings: What to Expect
With a market capitalization of $13.8 billion, Weyerhaeuser Company (WY) is one of North America’s largest private timberland owners and wood products manufacturers. Headquartered in Seattle, Washington, the company manages millions of acres of timberland and produces lumber, engineered wood products, and building materials used in residential and commercial construction. It operates through three segments: Timberlands; Real Estate, Energy & Natural Resources; and Wood Products.
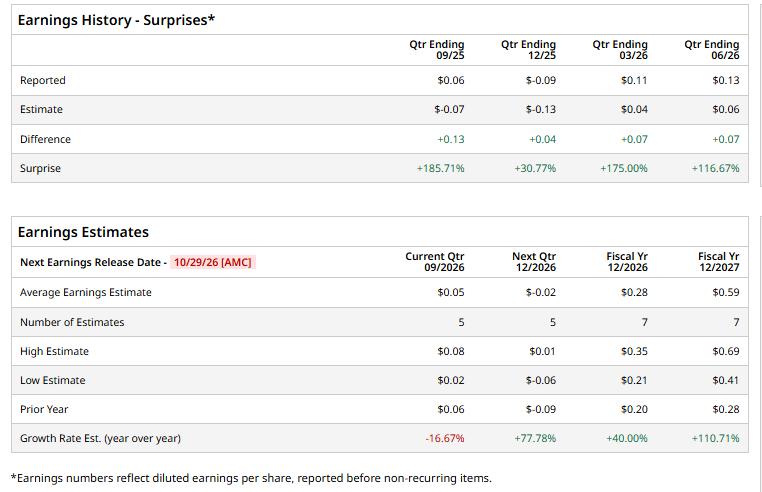
WY is expected to release its Q3 2026 earnings after the market closes on Thursday, Oct. 29. Ahead of the event, analysts expect the company’s FFO to be $0.05 on a diluted basis, down 16.7% from $0.06 in the year-ago quarter. The company has exceeded Wall Street’s FFO estimates in each of its last four quarters, which is impressive.
For fiscal 2026, analysts project the company’s FFO to be $0.28, up 40% from $0.20 in fiscal 2025. Moreover, its EPS is expected to rise by 110.7% year over year to $0.59 in fiscal 2027.
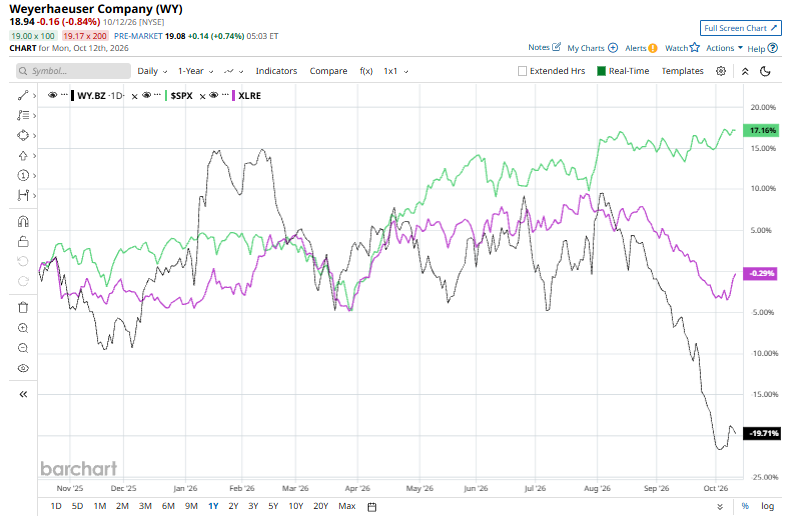
WY stock has declined 20.9% over the past 52 weeks, lagging behind the S&P 500 Index’s ($SPX) 19.2% rise and the State Street Real Estate Select Sector SPDR ETF’s (XLRE) 3.1% rise during the same time frame.
On Oct. 8, Weyerhaeuser shares popped 3.3% after the company announced a strategic partnership with TimberHP to expand the distribution of wood fiber insulation products across the U.S. Under the agreement, Weyerhaeuser will hold U.S. commercialization and distribution rights for TimberHP’s TimberBatt and TimberBoard products through the lumber and building materials channel.
The partnership will leverage Weyerhaeuser’s extensive distribution network, logistics capabilities, and customer relationships to expand access to sustainable, energy-efficient building materials. The companies will also collaborate on customer education, technical support, and potential development of new wood-based building products.
Analysts are moderately bullish on WY, with a “Moderate Buy” rating overall. Among the 13 analysts covering the stock, eight recommend a “Strong Buy,” one suggests a “Moderate Buy,” and the remaining four advise “Hold.” WYI’s average analyst price target is $27.42, indicating an upside of 44.8% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.