
Will Core Business Stumbles Change Dover (DOV) Stock Narrative
- Dover highlighted new convenience retail and fueling technologies at the NACS Show and PEI Convention in Las Vegas, including energy saving cooler doors, compact CO2 refrigeration systems, EV fast chargers and cloud based site management tools.
- The product push into small format refrigeration, forecourt digitization and EV charging comes as Dover faces pressure from weak organic revenue, modest EPS progress and declining returns on capital.
- This analysis examines how Dover's underperforming core operations shape the investment narrative around its push into energy saving retail technologies.
Dover Investment Narrative Recap
For Dover, the investment case hinges on the belief that slower-growing legacy units can be reshaped by higher-value refrigeration, fueling software and clean energy exposure. The immediate swing factor remains execution. Plant consolidation issues and modest organic progress leave little room for further stumbles before investors question the payoff from ongoing capital projects.
The NACS and PEI product push helps the story on mix but does not resolve near-term bottlenecks by itself. The biggest risk still sits with operational delivery in refrigeration and other capacity expansions. Any fresh delays or cost overruns could weigh on earnings progress and limit how the market values that growth pipeline.
The most interesting piece of this NACS lineup for shareholders is the Wayne PWR DC fast charging platform. It places Dover directly at the intersection of retail fueling, electrification and software-driven site management, which already sits alongside its broader clean energy and fueling portfolio and existing SaaS-based forecourt tools.
For catalysts, Wayne PWR ties hardware to remote monitoring and data, which fits neatly with Dover’s recurring software ambitions in fueling platforms. Real progress here relies on reliable uptime, tight integration with systems such as SiteIQ and DX Fleet, and disciplined capital allocation so that slower organic growth elsewhere does not dilute returns from this newer infrastructure push.
Dover's narrative projects US$9.8b revenue and US$1.5b earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$0.4b from US$1.1b today.
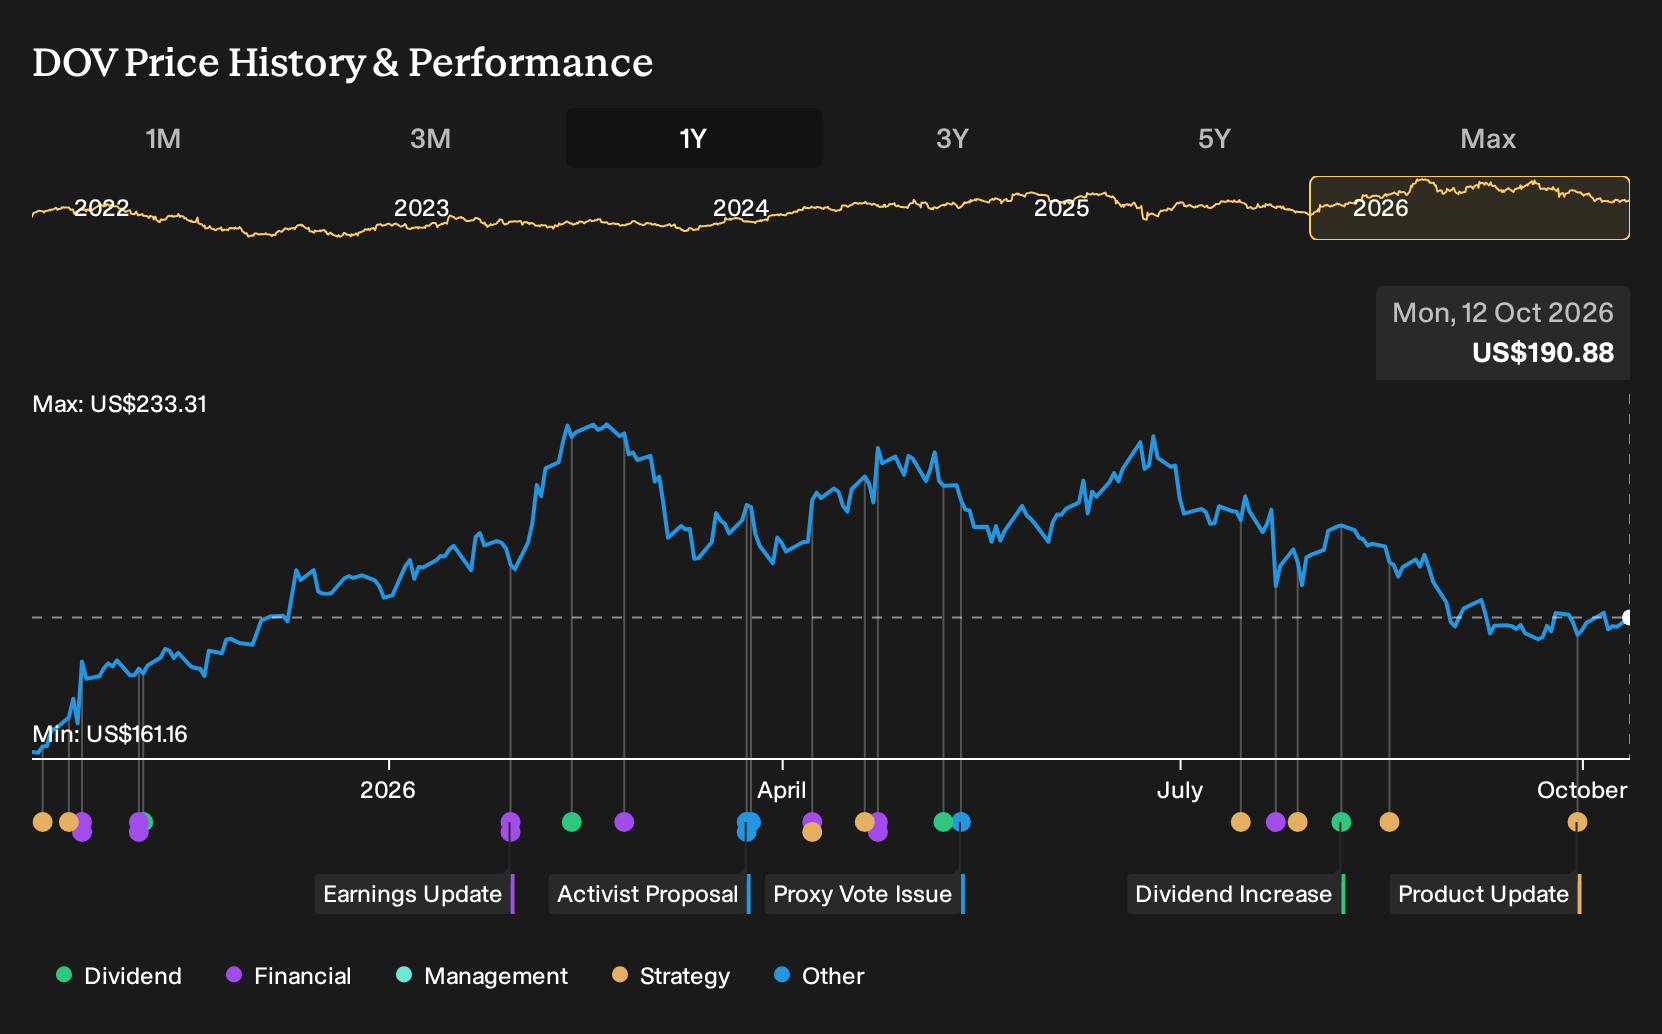
Discover how Dover's fair value indicates a 28% potential upside to its current price that could close earlier than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$243.02 and US$243.79, yet the small sample underlines how opinions on Dover can still differ. This is reflected in concerns about weak organic progress and P/E compression, contrasted with long term positions in data center cooling, clean energy components and higher margin software. Expect wide debates and consider several alternative viewpoints before forming a view.
Explore another Dover fair value estimate, including one that suggests as much as 28% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dover research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Dover. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dover's overall financial health at a glance.
Looking For More Ideas Beyond Dover?
If the Dover story has sharpened your view on quality, cash flow and capital discipline, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- If you prefer businesses that trade below what their fundamentals might justify and want a shortlist built around that lens, take a look at the 29 high quality undervalued stocks.
- If resilience matters more to you than excitement and you want candidates with more robust risk profiles, start with the 31 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and underlying financial quality, filter for companies through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com