
3 Indian Growth Stocks With ROE Above 22%
India is pushing hard on new free trade deals that could lift the country’s GDP by an estimated $140b over the next decade, and that kind of opening up tends to reward homegrown businesses that are already scaling fast. When growth and policy momentum line up, investors often regret sitting on the sidelines. This article highlights three fast expanding Indian stocks where insiders still own a meaningful chunk.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the absolute best, these 40 high growth high conviction stocks are the cream of the crop.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical business that develops and manufactures differentiated drug formulations using its proprietary RubiReten and RubiSRL delivery platforms.
Operations: Rubicon Research generates ₹19,358 million in revenue from pharmaceutical products including generics, speciality formulations, APIs and related services.
Market Cap: ₹255 billion
Rubicon Research fits this fast growing, high insider ownership theme through its focus on proprietary drug delivery platforms that aim to create harder to copy formulations and deeper partnerships with global pharma customers.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
The real swing factor for Rubicon Research is how one evolving pressure ultimately shapes pricing strength in those higher value therapies.
That pressure point is exactly what the full narrative for Rubicon Research unpacks, including where pricing power could accelerate or stall as Rubicon Research leans on its proprietary platforms.

Atlanta Electricals (NSEI:ATLANTAELE)
Overview: Atlanta Electricals manufactures power and special duty transformers for transmission, infrastructure and industrial projects across India, with high insider ownership aligning management closely with long term growth.
Operations: Atlanta Electricals generates ₹20,027 million in revenue from manufacturing power and special duty transformers, entirely from customers within India.
Market Cap: ₹141.95 billion
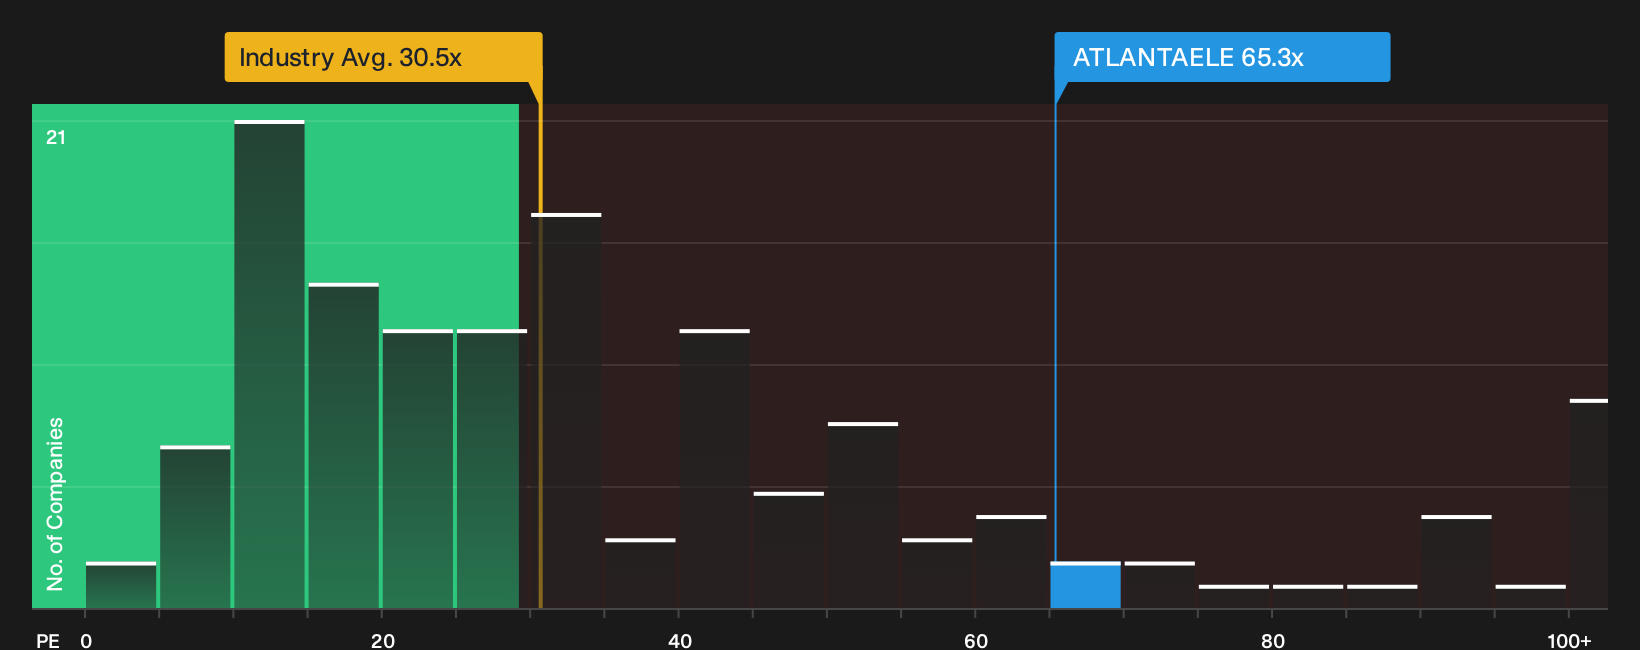
Atlanta Electricals plugs directly into India’s grid and renewable build out, with earnings up 74.1% over the past year and revenue forecast to rise 23.2% annually. The shares are trading on a 65.3x P/E that may depend on how an unseen pressure on future margins and order flow ultimately develops.
That margin question is exactly what the analysis report for Atlanta Electricals unpacks so you can see whether Atlanta Electricals’ rich P/E is stretching ahead of its fundamentals.
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects runs turnkey EPC power transmission and distribution projects, giving direct exposure to high voltage grid expansion and electrification.
Operations: Bajel Projects generates ₹27,508 million in revenue from power transmission and power distribution EPC work and related structures.
Market Cap: ₹18.08 billion
Bajel Projects aligns with a fast-growth, high insider ownership theme, with earnings forecast to rise 57.67% a year and revenue expected to climb 27% annually, relative to the broader Indian market. That level of grid build-out exposure comes with an 82x P/E and significant borrowing, so outcomes depend heavily on how pressure on future project profitability is resolved.
That kind of leverage makes Bajel Projects a classic high risk, high reward setup, so check the analysis report for Bajel Projects to see what could shift the story next

Curious About What You Might Be Missing Next
Fresh opportunities rarely stay quiet for long. Strong businesses can reach breakout momentum before most investors even notice. Review these ideas while they are still under the radar and consider them before they attract wider attention.
- Identify cash generative compounders early by running the 181 high quality undervalued stocks so you are not reacting to quality stocks only after they have already moved.
- Evaluate the next infrastructure and electrification cycle by reviewing the 43 power grid technology and infrastructure stocks before these grid focused businesses become more widely followed.
- Monitor potential payout opportunities by scanning the 217 dividend fortresses while yields, prices and fundamentals still appear aligned for interested investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com