
Alstom (ENXTPA:ALO) Lands A €350 Million Train Order, Is The Discount Warranted?
Alstom (ENXTPA:ALO) is back in focus after Västtrafik exercised an option for 35 additional Avelia Stream Nordic X80 trains, a roughly €350 million order that extends the company’s existing regional fleet program.
The new Swedish contract lands at a time when Alstom’s share price has edged up in recent weeks, with a 7 day share price return of 3.01% and a 90 day gain of 4.33%. However, the stock is still down 38.07% year to date and the 1 year total shareholder return has fallen 28.27%. This leaves the recent contract win sitting against a backdrop of longer term share price pressure, but with a positive 3 year total shareholder return of 32.31% that highlights how quickly sentiment around the business can shift when confidence improves.
Scan other rail and infrastructure plays that are moving on contract wins and long-term service deals with our curated 43 power grid technology and infrastructure stocks
For Alstom, this Swedish order sits between two stories: one about contract momentum and another about bruised sentiment. Which of those is actually driving what you are paying for the shares today?
Most Popular Narrative: 23% Undervalued
On the most followed view, Alstom’s fair value of €20.7 sits well above the last close at €15.91. This puts the latest Swedish order into a broader story about backlog quality, execution risk and what investors are currently willing to pay for that mix.
The current valuation implies the market is treating Alstom’s record €104b backlog, improved embedded gross margin and reduced net financial debt of about €400m as carrying meaningful execution and cash flow risk. Some investors may view this as indicating that the shares are undervalued.
See why 28 investors see Alstom as 23% undervalued.
Result: Fair Value of €20.7 (UNDERVALUED)
Still, Alstom’s rolling stock execution problems and the €600m to €700m free cash flow shortfall could quickly reshape how investors interpret that 23% discount.
Find out about the key risks to this Alstom narrative.
Another View: What Alstom’s P/E Is Really Pricing In
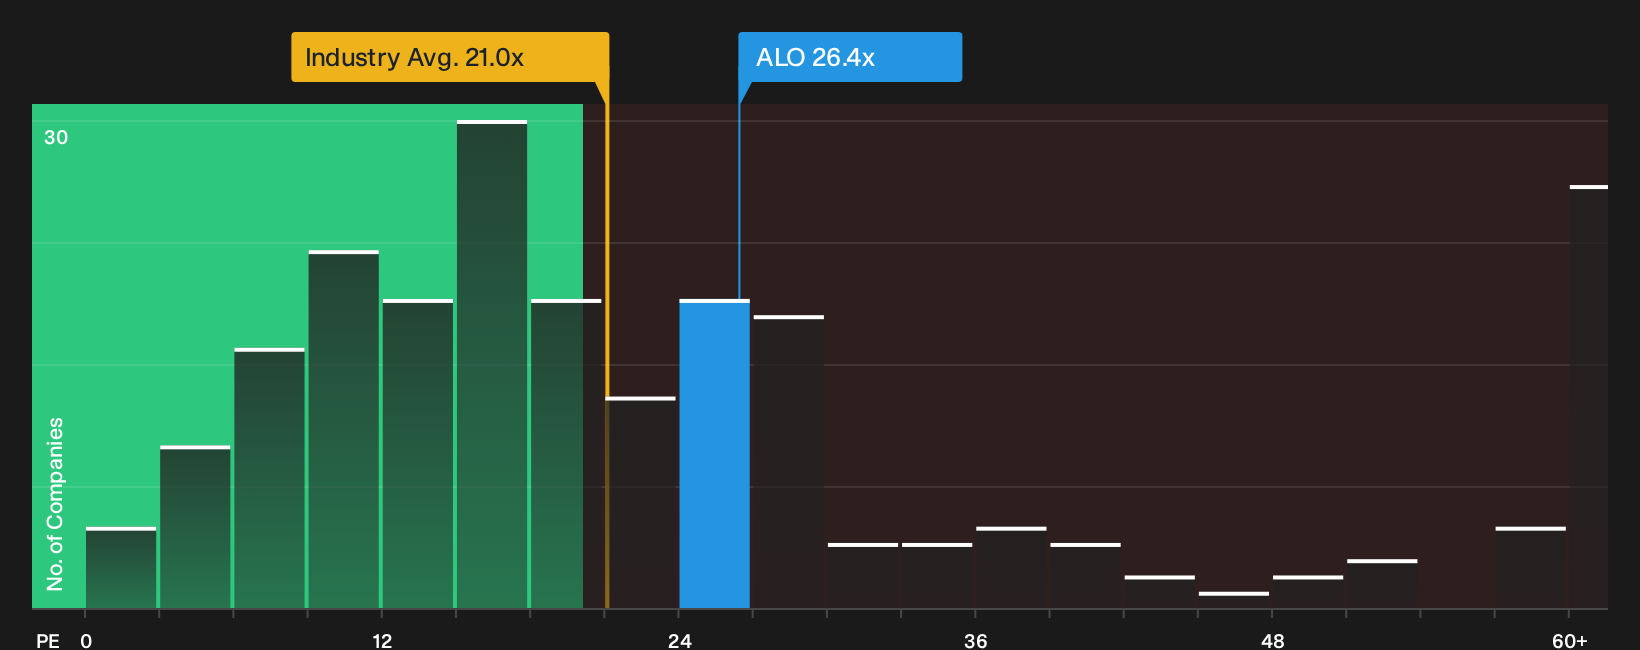
The fair value story painted by the €20.7 target runs into a very different message once you look at Alstom through its P/E ratio. The shares trade on 26.4x earnings, which is higher than both the European Machinery industry on 21x and peers on 15.9x, even though the fair ratio is 31.6x. That mix of richer pricing versus rivals but a discount to the fair ratio leaves a simple question for investors. Is this a mispriced opportunity or just extra valuation risk for a business still working through execution and cash flow issues?
For a closer look at how this P/E gap could close from here, including what it might mean if the market moves toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on whether Alstom is a recovery story or a value trap. Act promptly, review the numbers, and weigh both the concerns and the optimism captured in our 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Alstom?
If Alstom has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with other ideas that match your investing style.
- Target potential mispricings by scanning companies that look attractively valued on both quality and price through the 181 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature resilient balance sheets and higher yields using the 217 dividend fortresses.
- Reduce portfolio stress by filtering for companies with sturdier fundamentals and lower risk profiles with the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com