
What to Expect From Amazon.com’s Q3 2026 Earnings Report
Seattle, Washington-based Amazon.com, Inc. (AMZN) is a global technology and e-commerce company offering online shopping, cloud computing, streaming entertainment, AI services, advertising, healthcare, and consumer electronics. With a market capitalization of $2.8 trillion, Amazon serves millions of customers worldwide through its broad range of products and services and its extensive global operations network.
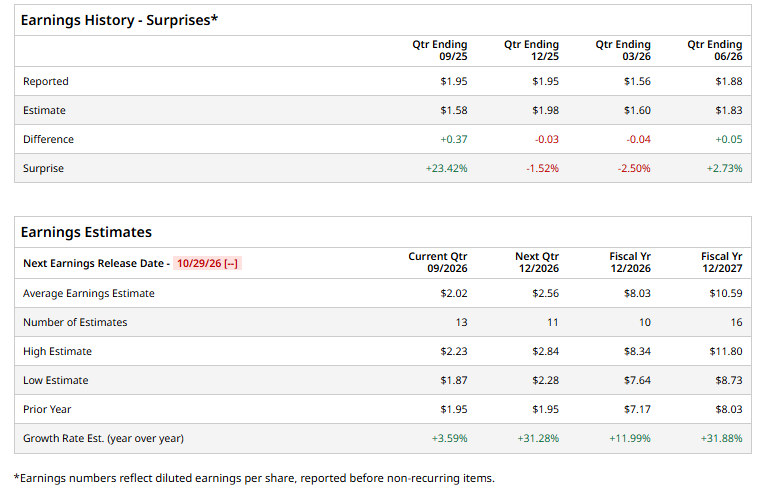
AMZN is set to report its Q3 earnings soon. Ahead of the release, analysts expect the company to report diluted EPS of $2.02, up 3.6% from $1.95 in the year-ago quarter. However, AMZN has exceeded Wall Street’s EPS estimates in only two of the past four quarters, missing estimates in the other two.
For fiscal 2026, analysts expect the company to report EPS of $8.03, up 12% from $7.17 in fiscal 2025. Moreover, AMZN’s EPS is projected to increase 31.9% year over year to $10.59 in fiscal 2027.
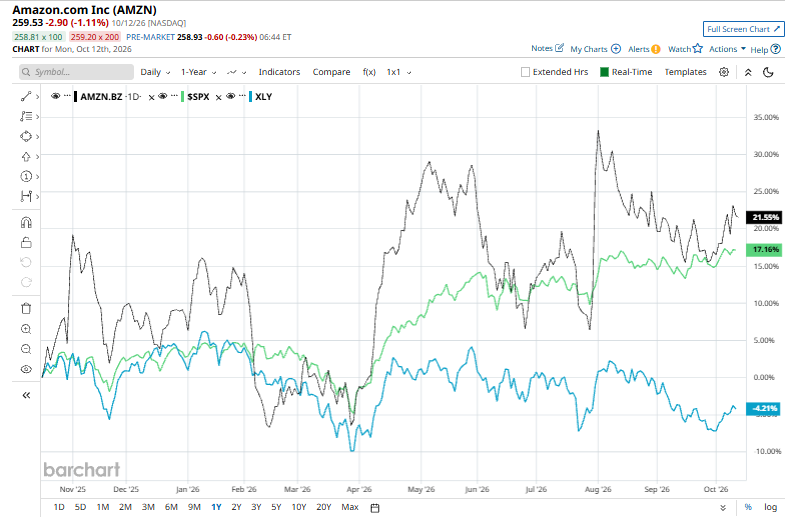
AMZN stock has climbed 20% over the past 52 weeks, outperforming both the S&P 500 Index ($SPX), which advanced 19.2%, and the State Street Consumer Discretionary Select Sector SPDR ETF (XLY), which declined 1.8% over the same period.
Amazon’s outperformance has been driven by its highly profitable AWS segment, which has fueled revenue growth, and operating leverage from previous infrastructure investments, which has supported strong EPS growth over several years. On September 30, Amazon shares rose 1% following the announcement of a multiyear, $1 billion-plus agreement with Synopsys, Inc. (SNPS) to accelerate custom chip development. The deal could help Amazon reduce its reliance on NVIDIA, lower computing costs, and improve AWS profitability over time, strengthening its competitive position in the AI and cloud computing markets.
Analysts remain bullish on AMZN, with the stock carrying a consensus “Strong Buy” rating. Of the 56 analysts covering the stock, 47 recommend a “Strong Buy,” six rate it a “Moderate Buy,” and three suggest a “Hold.” Meanwhile, the average price target of $328.91 implies potential upside of 26.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.