
Mitie Group (LSE:MTO) In Focus As Hedge Funds Circle While Valuation Debate Widens
Mitie Group (LSE:MTO) is back in focus after several hedge funds, including Millennium International Management, Qube Research & Technologies and Balyasny Asset Management, disclosed sizeable derivatives positions and interests under the UK Takeover Code.
Mitie Group’s share price has quietly tracked higher, with a 90 day share price return of 40.68% and a year to date share price return of 27.64%. The 5 year total shareholder return of 271.39% sits in the background as hedge funds build derivatives exposure and debate grows around a P/E of about 32.4x versus a Commercial Services average of 15.9x.
Compare Mitie Group’s hedge fund attention and rich P/E with other potential high-expectation plays using our curated list of 5 high quality undiscovered gems across the market.
Mitie Group now trades slightly above analyst targets yet sits at a steep discount to some fair value estimates. Is the recent surge a sign that caution is misplaced, or that optimism is running ahead of itself?
Most Popular Narrative: 3% Overvalued
Mitie Group’s most followed valuation narrative sets fair value at £2.04 compared with a last close of £2.11, which puts current enthusiasm slightly ahead of that estimate while still anchoring expectations in detailed earnings and margin assumptions.
The implementation of a facilities transformation 3-year plan is expected to drive growth, with a goal of moving from facilities management to technology-led and data-rich facilities transformation. This focus aims to improve revenue growth by transforming the built environment and enhancing client services.
See why 37 investors see Mitie Group as 3% overvalued.
Result: Fair Value of £2.04 (OVERVALUED)
Still, Mitie Group’s reliance on acquisitions, along with its exposure to inflation and national insurance costs, could quickly challenge the upbeat valuation narrative if execution slips.
Find out about the key risks to this Mitie Group narrative.
Another View: SWS DCF Points To Deep Value
The market is pricing Mitie Group on a P/E of 32.4x, which screens as expensive against peers. Our DCF model tells a very different story. On that approach, the shares are assessed as trading well below an estimated future cash flow value of £6.32, raising the question of which signal you trust more.
Look into how the SWS DCF model arrives at its fair value.
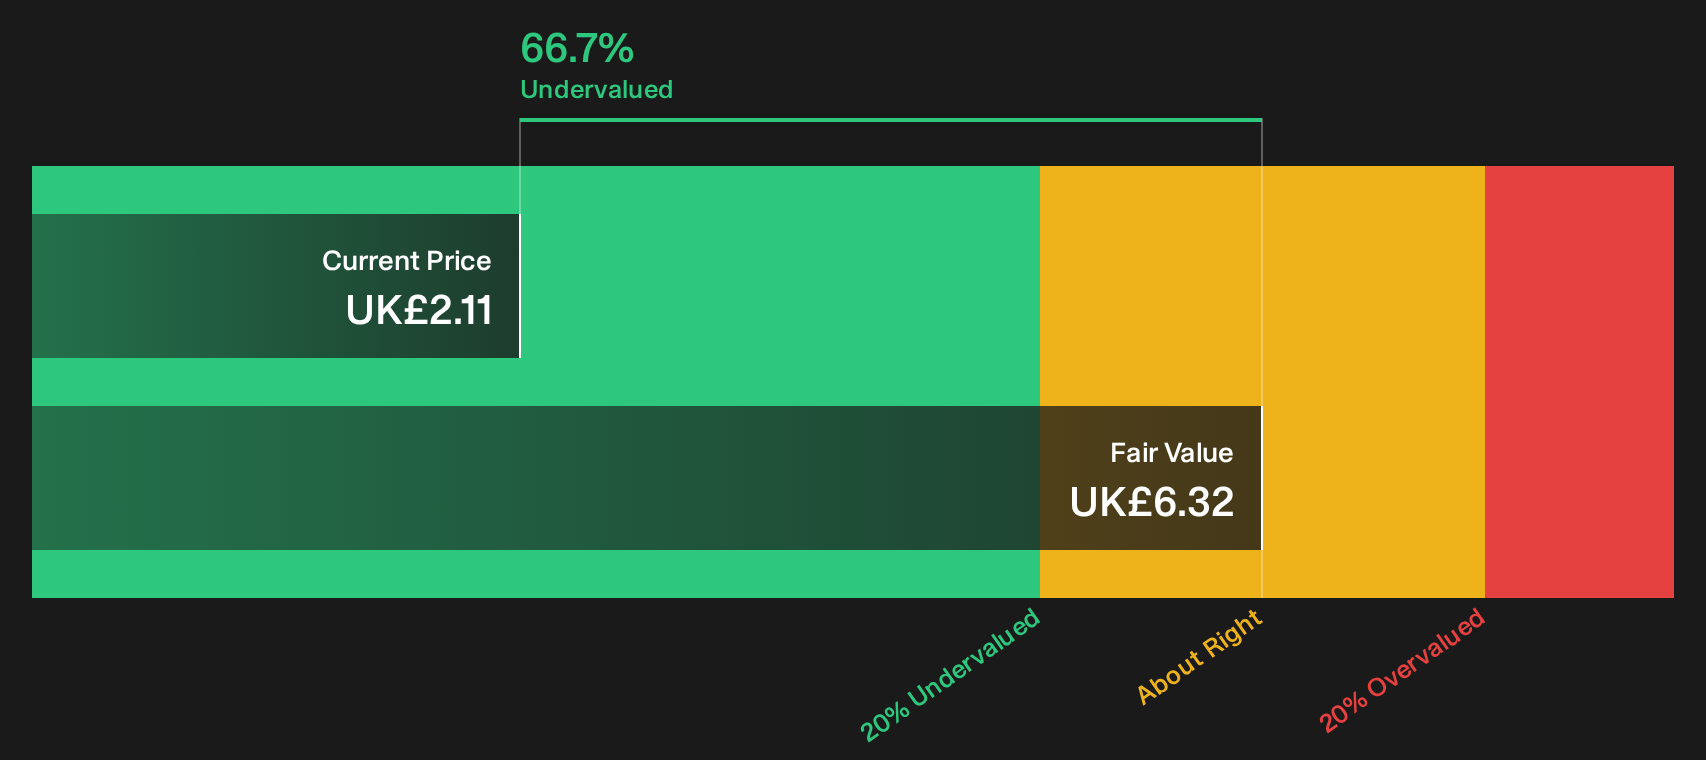
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitie Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Mitie Group, with both warning flags and upside potential, leave the verdict wide open. Move quickly and pressure test the data yourself by weighing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Mitie Group?
Do not stop at one stock. Use the Simply Wall Street Screener to spot fresh ideas across different styles before the next move leaves you on the sidelines.
- Target quality at a discount by scanning for resilient companies using the 7 high quality undervalued stocks.
- Prioritise reliability and capital strength with a list of solid balance sheet and fundamentals (9 results) that filters for sturdier fundamentals.
- Dial down potential volatility and focus on capital preservation through a 4 resilient stocks with low risk scores tailored for more cautious positioning.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com