
Ichor Holdings (ICHR) Stock May Still Look Like A Bargain On Sales
Ichor Holdings has delivered a powerful year to date rally, and that kind of climb naturally prompts a question about what investors are paying for its sales today. With the share price moving far ahead of where it started the year, the issue is whether the current valuation still lines up with the revenue the business is generating.
- The stock is up about 166.4% year to date, which puts real pressure on investors to judge if that move is fully backed by Ichor Holdings' sales base.
- The company’s role supplying equipment and subsystems to chip manufacturers can shape how reliably it converts demand in the semiconductor supply chain into revenue. This matters a lot when you value the shares on sales.
- The analysts covering Ichor Holdings have run their own numbers. See what analysts think Ichor Holdings's shares could be worth.
The issue now is whether the current Ichor Holdings share price near US$54.38 is appropriately supported by its sales when compared with the Fair Ratio benchmark.
If you are considering whether Ichor Holdings' rally is justified by its sales, it can help to compare it with other businesses screened for valuation strength such as 29 high quality undervalued stocks
Is Ichor Holdings a Bargain on Sales?
P/S fits Ichor Holdings because the market often values semiconductor suppliers most cleanly on revenue rather than near term earnings swings.
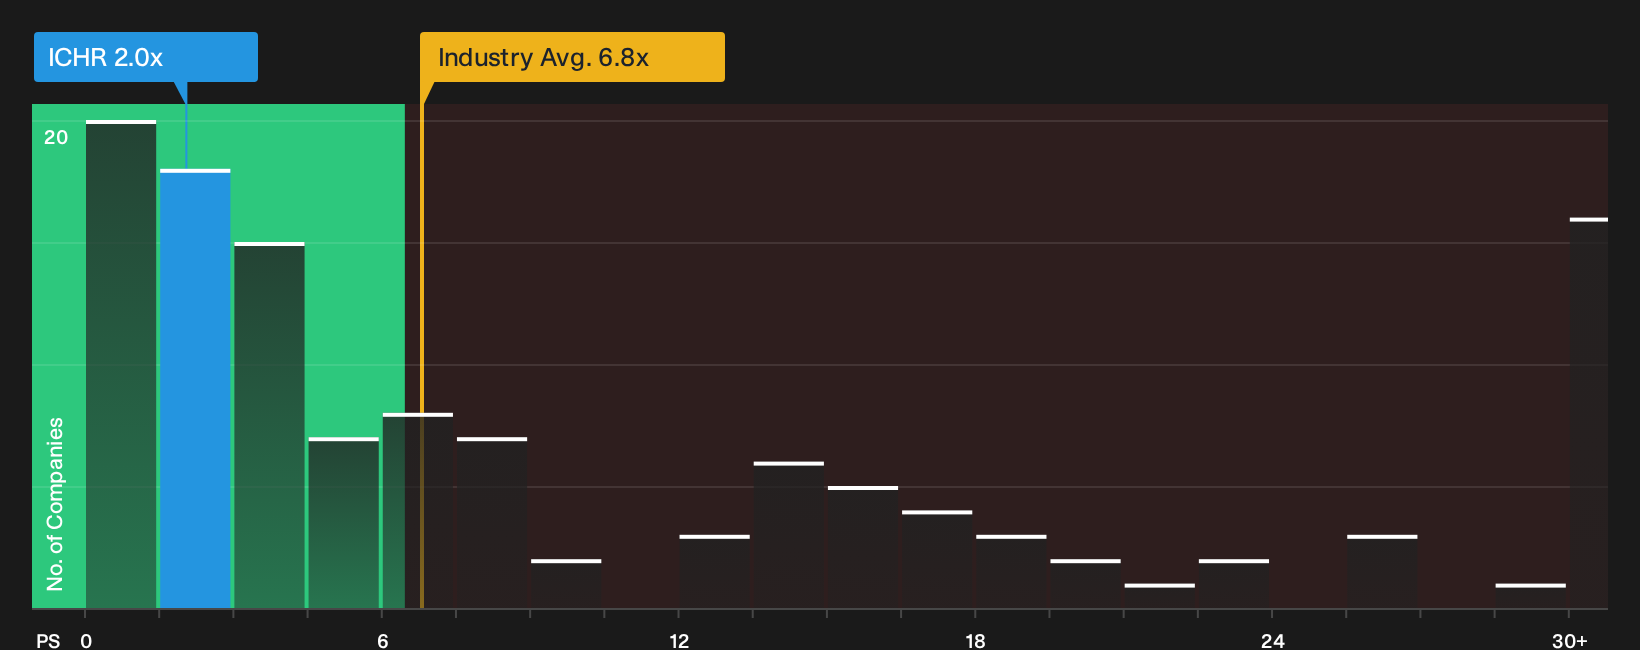
The shares trade on a P/S of about 2.0x, against a semiconductor industry average around 6.8x and a peer group near 4.2x. On this framework, the stock changes hands at a discount to both broad sector pricing and closer listed comparables.
The Fair Ratio, which adjusts the P/S multiple for Ichor Holdings' own scale, margins and risk profile, also sits above the current 2.0x level. That gap suggests investors are paying less per dollar of sales than this tailored benchmark implies might be typical for the business, so the market is pricing in some caution on its future revenue quality and execution. Explore the numbers behind Ichor Holdings's P/S valuation.
The Ichor Holdings Narrative: What Would Justify Today's Price?
Ichor Holdings' Simply Wall St Narratives pick up where this valuation puzzle leaves off. They spell out which paths for future growth, margins and earnings would need to play out for the current share price to look meaningfully high or low. Instead of stopping at a single ratio or model output, they unpack the business assumptions that number rests on so you can judge, over time, whether reality is tracking that script on the Community page.
One of the top community narratives on Ichor Holdings: 32% undervalued
"Persistent labor issues and delayed production capacity are limiting near-term revenue and margin improvement despite strong long-term industry drivers."
Discover why this Narrative puts Ichor Holdings at 32% undervalued.
One more piece of Ichor Holdings' story that deserves your attention
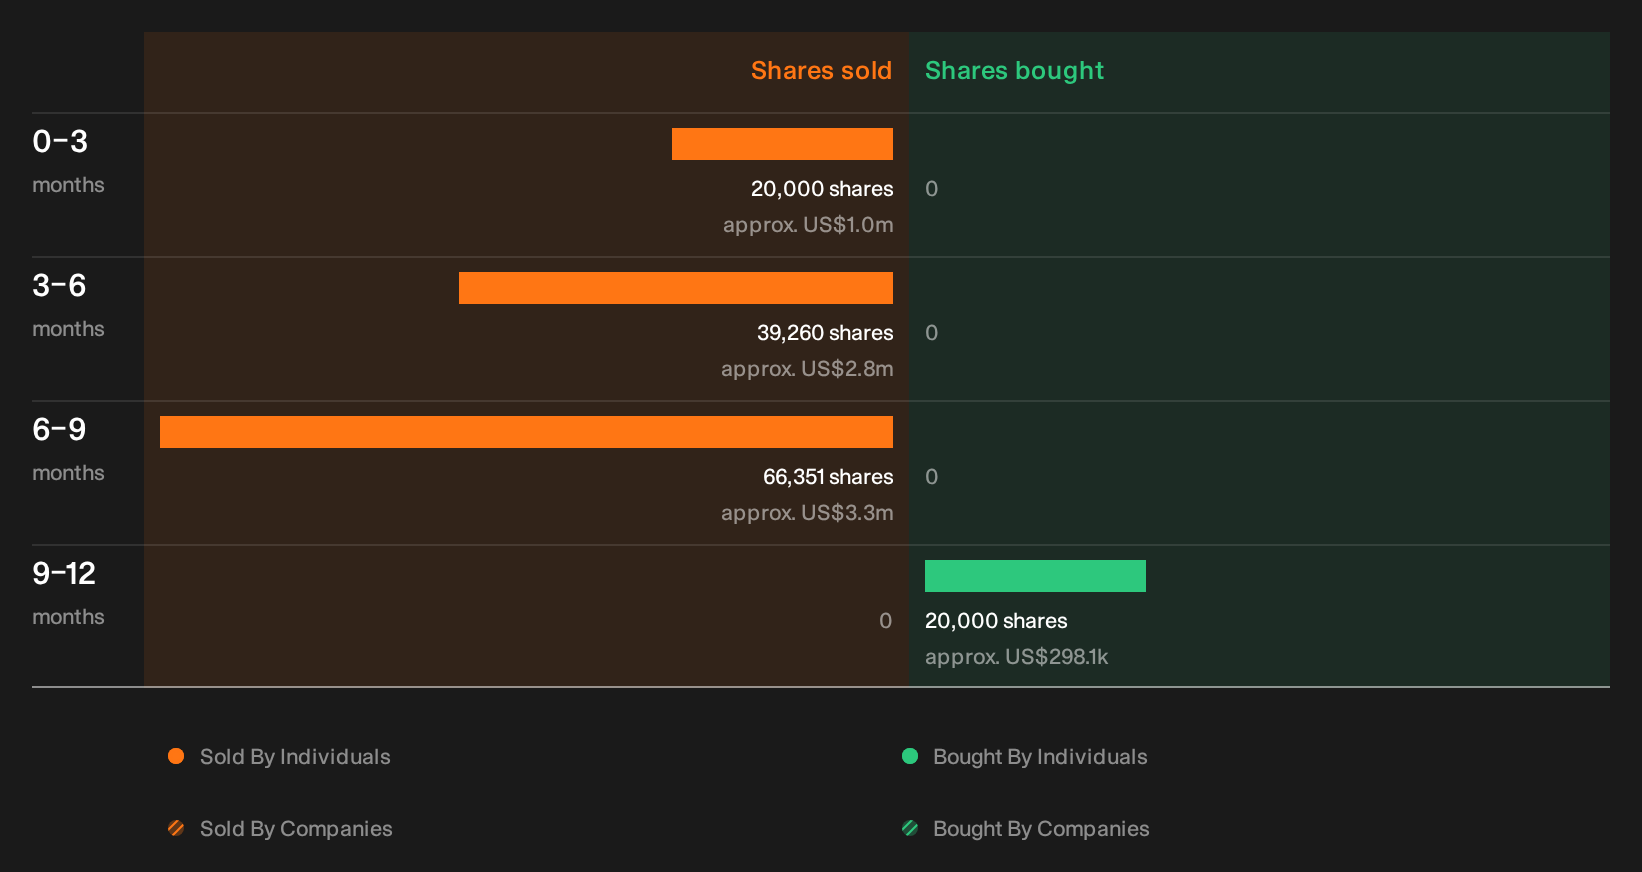
Price and sales only tell part of the picture for Ichor Holdings, because recent trading disclosures show insiders have been cashing out and the who, how much and why are all still for you to unpack. See the recent insider selling flagged for Ichor Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com