
3 TSX Growth Stocks With High Insider Ownership And 79% Earnings Growth
As the Canadian market continues to ride the wave of a resilient bull market, supported by strong economic growth and rising corporate profits, investors are keenly observing how factors like AI-driven growth and interest rate dynamics shape future opportunities. In this environment, growth companies with high insider ownership can be particularly appealing as they often demonstrate strong alignment between management and shareholders, potentially driving robust earnings performance.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 33.7% |
| Obsidian Energy (TSX:OBE) | 11.2% | 74.4% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32.1% |
| Electrovaya (TSX:ELVA) | 34.9% | 41.2% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.6% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
| Abcourt Mines (TSXV:ABI) | 33.2% | 46.5% |
Below we spotlight a couple of our favorites from our exclusive screener.
Aritzia (TSX:ATZ)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Aritzia Inc., along with its subsidiaries, designs, develops, and sells apparel and accessories for women in the United States and Canada, with a market cap of CA$16.63 billion.
Operations: The company's revenue is primarily derived from its apparel segment, which generated CA$4.35 billion.
Insider Ownership: 16.4%
Earnings Growth Forecast: 13.7% p.a.
Aritzia's strong growth trajectory is underscored by its earnings and revenue forecasts, which are expected to outpace the Canadian market. Recent financial results highlight significant year-over-year increases in sales and net income. Despite limited insider buying recently, insider ownership remains high, indicating confidence in the company's future prospects. The company has also been actively repurchasing shares, enhancing shareholder value. New board member Valérie Hermann brings extensive fashion industry expertise to Aritzia's leadership team.
- Get an in-depth perspective on Aritzia's performance by reading our analyst estimates report here.
- The analysis detailed in our Aritzia valuation report hints at an deflated share price compared to its estimated value.
Cardinal Energy (TSX:CJ)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Cardinal Energy Ltd. is involved in acquiring, exploring, developing, optimizing, and producing petroleum and natural gas across Alberta, British Columbia, and Saskatchewan in Canada with a market cap of CA$2.31 billion.
Operations: The company's revenue segment is derived from Oil & Gas - Exploration & Production, amounting to CA$550.01 million.
Insider Ownership: 22.3%
Earnings Growth Forecast: 32.7% p.a.
Cardinal Energy is poised for growth with its earnings projected to expand significantly, outpacing the broader Canadian market. The recent decision to expand the Reford 2 SAGD project highlights strategic investments in capacity growth, aiming for enhanced capital efficiency. Despite limited insider trading activity recently, insider ownership remains strong, reflecting confidence in future prospects. However, profit margins have declined compared to last year and dividends are not well covered by earnings or free cash flows.
- Click to explore a detailed breakdown of our findings in Cardinal Energy's earnings growth report.
- Our valuation report here indicates Cardinal Energy may be overvalued.

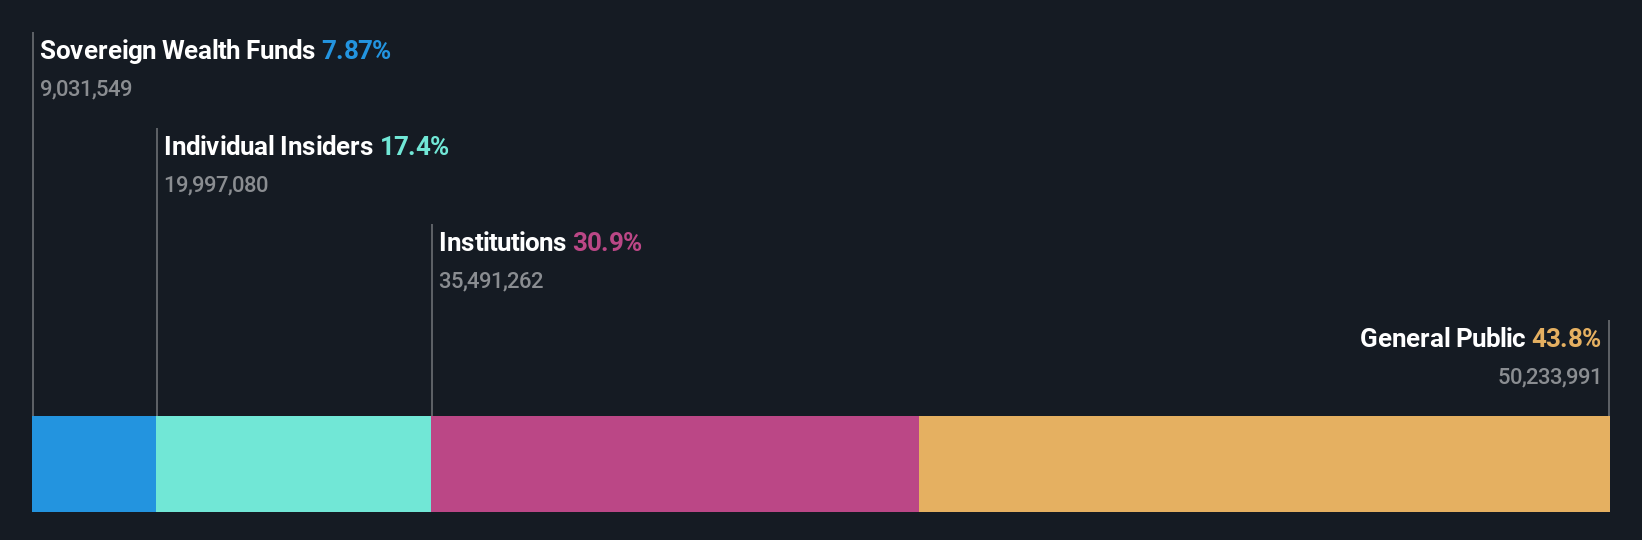
Meridian Mining (TSX:MNO)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Meridian Mining Plc focuses on the acquisition, exploration, and development of mineral properties in Brazil and has a market cap of CA$1.16 billion.
Operations: Meridian Mining's revenue segments are not provided in the available text.
Insider Ownership: 16.2%
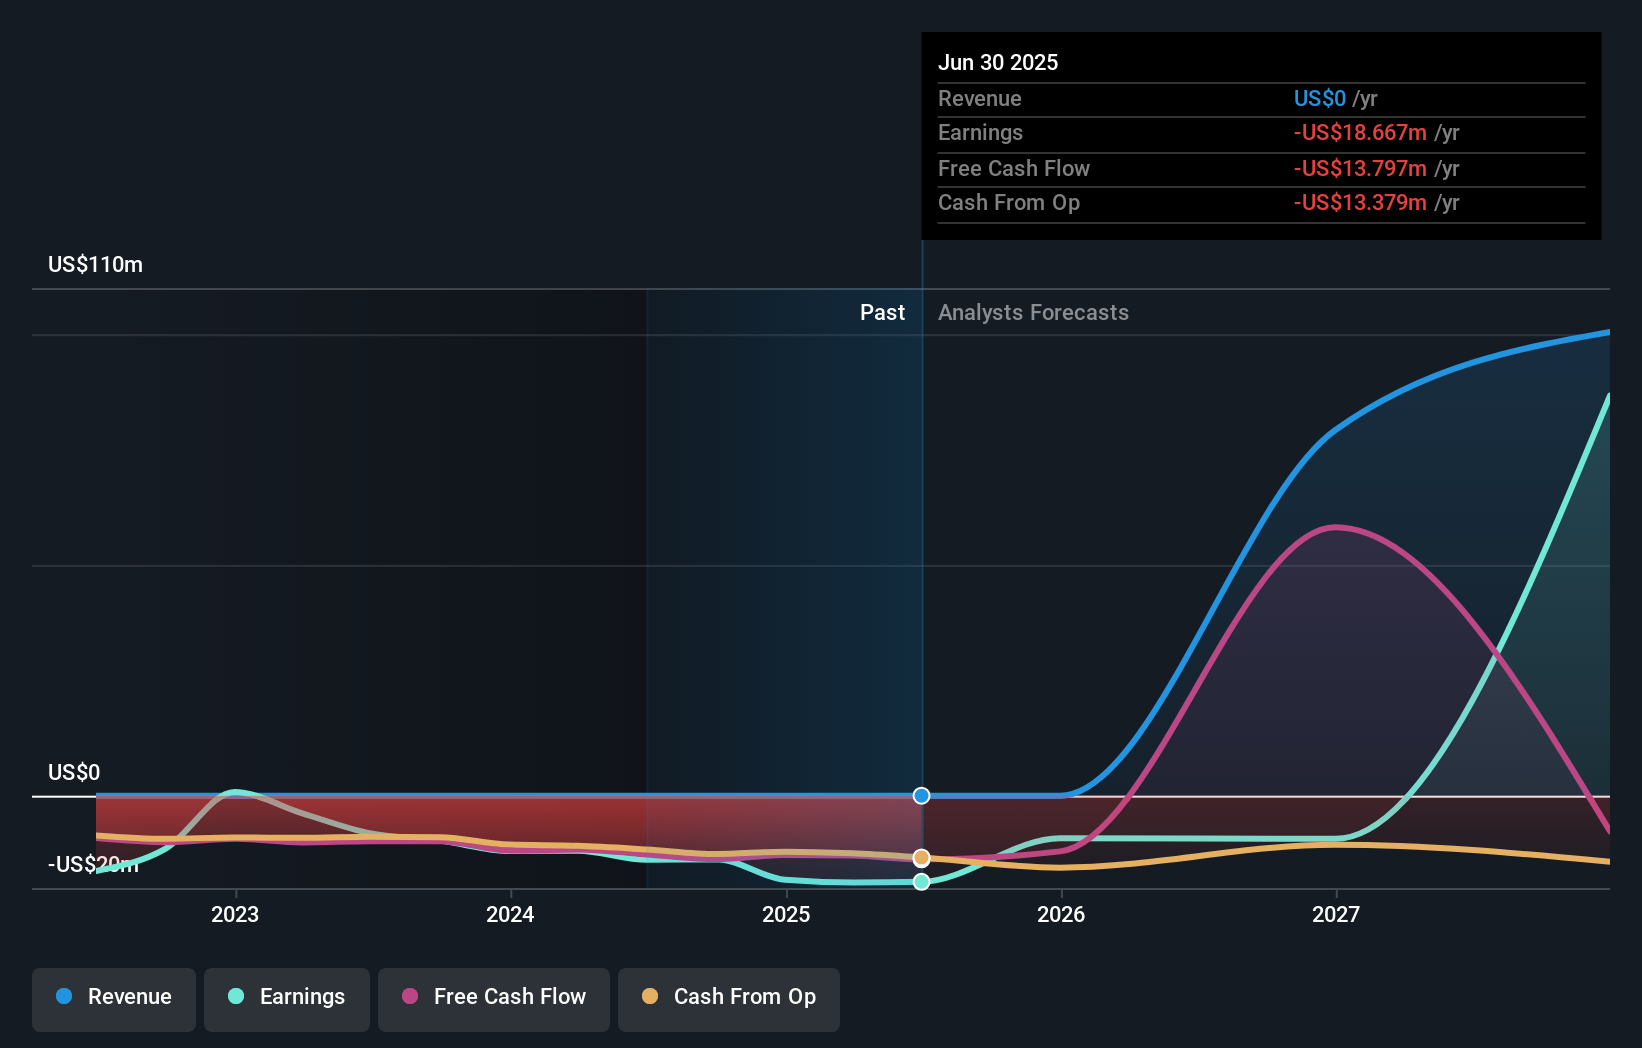
Earnings Growth Forecast: 79.1% p.a.
Meridian Mining is on a growth trajectory with earnings expected to grow significantly over the next three years, driven by strategic developments at its Cabaçal project. The company recently completed a Definitive Feasibility Study for Cabaçal, indicating promising potential in gold-copper-silver production. Despite past shareholder dilution and current losses, Meridian's addition to major indices like FTSE 350 reflects market confidence. High insider ownership suggests belief in long-term value creation despite current revenue challenges.
- Click here and access our complete growth analysis report to understand the dynamics of Meridian Mining.
- Insights from our recent valuation report point to the potential overvaluation of Meridian Mining shares in the market.
Seize The Opportunity
- Dive into all 52 of the Fast Growing TSX Companies With High Insider Ownership we have identified here.
- Contemplating Other Strategies? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com