
Illumina Earnings Preview: What to Expect
San Diego, California-based Illumina, Inc. (ILMN) provides sequencing- and array-based solutions for genetic and genomic analysis. Valued at $41.8 billion by market cap, the company also provides a comprehensive line of products and services that currently serve the sequencing, genotyping and gene expression markets for genomic research centers, pharmaceutical companies, academic institutions and biotechnology companies. The global leader in genomics is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Thursday, Oct. 29.
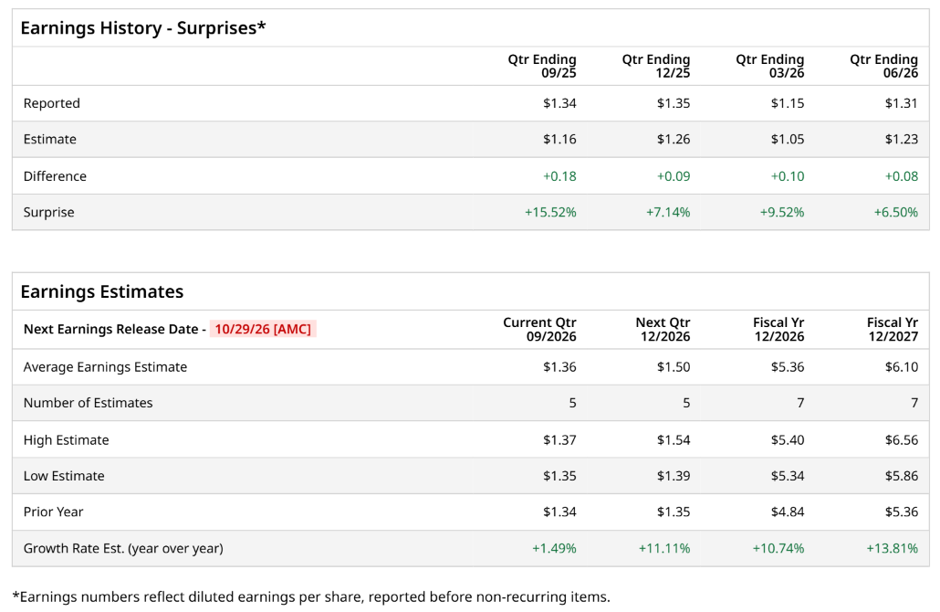
Ahead of the event, analysts expect Illumina to report a profit of $1.36 per share on a diluted basis, up 1.5% from $1.34 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Illumina to report EPS of $5.36, up 10.7% from $4.84 in fiscal 2025. Its EPS is expected to rise 13.8% year over year to $6.10 in fiscal 2027.
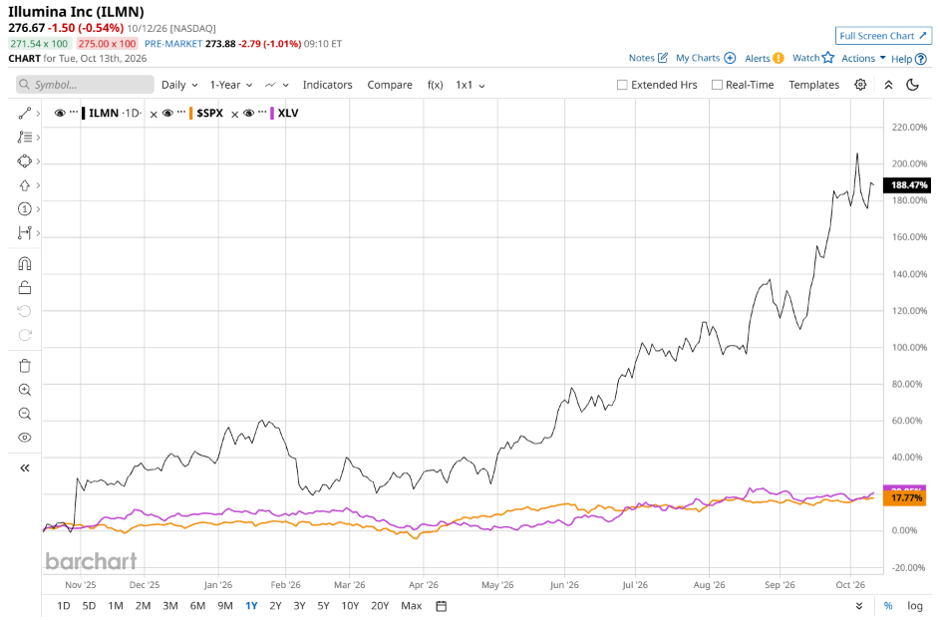
ILMN stock has significantly outperformed the S&P 500 Index’s ($SPX) 19.2% gains over the past 52 weeks, with shares up 190.3% during this period. Similarly, it remarkably outperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 20.9% returns over the same time frame.
Illumina's solid outperformance was primarily driven by robust execution and high demand within its core clinical sequencing market representing roughly 65% of consumables revenue, spurred by strong adoption of the NovaSeq X platform and significant U.S.-Canada growth. Beyond core sequencing, the company expanded its footprint through multi-omics initiatives, including the rollout of StrataMap Spatial, proteomics traction via SomaLogic, and data-focused offerings like BioInsight. Despite rising input costs such as freight and memory, disciplined expense management allowed margins to beat expectations, reinforcing an upward revision to full-year revenue and EPS guidance.
Analysts’ consensus opinion on ILMN stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 21 analysts covering the stock, 10 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” seven give a “Hold,” one recommends a “Moderate Sell,” and two advocate a “Strong Sell.” While ILMN currently trades above its mean price target of $234.43, the Street-high price target of $310 suggests an upside potential of 12%.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.