
AZZ (AZZ) Dividend Affirmation Puts Its Undervalued Narrative To The Test
AZZ (AZZ) just paired a fresh dividend affirmation with an upcoming earnings release, giving investors two near term dates to watch. The board approved a $0.24 quarterly cash payout for fiscal Q2 2027.
AZZ shares closed at $137.76, with a 1-day share price return of 0.66% and a year to date share price gain of 25.53%. The 1-year total shareholder return of 37.24%, along with very strong 3-year and 5-year total shareholder returns, indicates that longer term momentum has been much stronger than the recent 90-day share price pullback of 8.15%.
Scan other infrastructure and coatings players showing similar momentum by reviewing the hand picked 43 power grid technology and infrastructure stocks alongside AZZ ahead of tomorrow's earnings update.
After a sharp multi year run and a recent pullback, AZZ now sits between strong trailing returns and pre earnings uncertainty. Is this a reasonable moment to step in, or does patience offer a better entry on valuation grounds?
Most Popular Narrative: 16% Undervalued
Against AZZ's last close of $137.76, the most followed narrative pegs fair value at $164.00, so the gap between price and thesis is already clear and puts execution risk under the spotlight.
The Washington, Missouri Precoat Metals facility is moving toward targeted utilization with its anchor container customer, and management is starting to commercialize the remaining capacity, which could add incremental revenue and improve segment margins as fixed costs are spread over higher volumes.
Capacity expansions within the existing Metal Coatings footprint, such as the new large kettle in North Texas and added secondary services like ground line coating and spin kettles, are timed to areas with strong project activity and are framed as low risk, high return investments that can lift segment sales and EBITDA once fully ramped.
See why 5 investors see AZZ as 16% undervalued.
Result: Fair Value of $164.00 (UNDERVALUED)
Still, AZZ faces weather-related risks that can disrupt production, as well as cost inflation on materials and chemicals. If pricing fails to keep pace, these factors could pressure margins and earnings.
Find out about the key risks to this AZZ narrative.
Another View: AZZ On Earnings Multiples
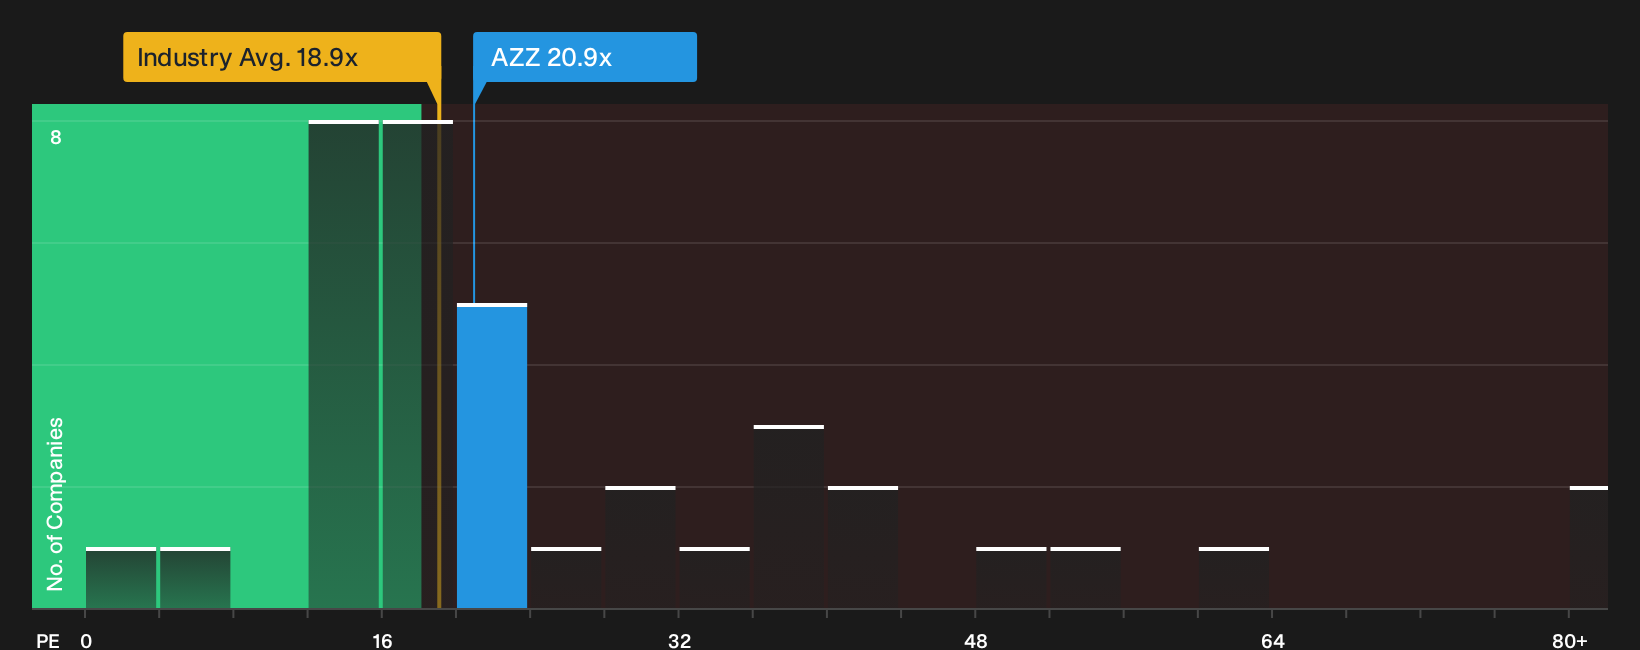
The narrative fair value for AZZ sits at $164.00, yet its current P/E of 20.9x tells a more cautious story. That ratio is higher than the US Building industry at 19.1x, and also above AZZ's own fair ratio of 17x. This suggests limited room for error if sentiment cools.
Peer companies on average trade at a higher 40.1x P/E, so AZZ does not appear stretched relative to its immediate comparison set. The gap between 20.9x today and a 17x fair ratio still leaves valuation risk if earnings underwhelm, which raises the question of how much confidence investors have in the current earnings narrative over the next few years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed on AZZ after all that, or already leaning one way? Act while the data is fresh and weigh both sides through 1 key reward and 1 important warning sign.
Looking for more AZZ sized investment ideas?
If AZZ has your attention, do not stop here. Broaden your watchlist now so you are not scrambling after the next big move appears.
- Target resilient compounding potential by scanning companies with steady fundamentals using the 31 resilient stocks with low risk scores.
- Spot potential bargains early by reviewing the 29 high quality undervalued stocks before fresh money chases the same opportunities.
- Strengthen your income playbook by tracking reliable payers and balance sheets through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com