
Merck (MRK) Stock Could Be A Bargain As Its 120% Run Continues
Merck has had a powerful multiyear run, and with oncology news still coming thick and fast, the real issue for you now is whether the current share price lines up with the cash the business can generate. The Discounted Cash Flow (DCF) lens helps frame that question around Merck's ability to convert its drug portfolio and pipeline into long term cash streams.
- Over the last 5 years Merck has delivered a 119.7% share price gain, which puts a lot of past optimism and current expectations into play when you ask what its cash flows are really worth today.
- Fresh oncology data, new targeted therapies like WELIREG and tulisokibart, and ongoing work to offset the future Keytruda patent expiry can all shape how durable Merck's cash generation may be and how far into the future those cash flows might stretch.
- If you'd rather focus on earnings, this one's for you. See why Merck's 113.1x P/E tells a different valuation story.
The issue now is whether Merck's recent share price level is adequately supported by the intrinsic value implied by its future cash flows.
If you are weighing Merck's oncology pipeline against patent risk and cash flow durability, a focused stock screen of other drugmakers and biotech players can be a useful second reference point through 31 resilient stocks with low risk scores.
Does Merck Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Merck’s expected free cash generation and discounts it back into today’s dollars. On this view, the business is treated as a stream of cash that equity holders can ultimately claim, not just a portfolio of oncology assets and patents.
Merck produced about $16.1b of free cash flow over the last twelve months, and the DCF framework assumes that this pool of cash is growing rather than shrinking, with analyst forecasts pointing to higher annual free cash flow by 2030. Those projections, combined with a 2 Stage Free Cash Flow to Equity setup, put Merck’s estimated intrinsic value substantially above the current share price of $145.45. Because the looming Keytruda patent expiry is so prominent in investor debates, that helps explain why the price can lag the value implied by these cash flow projections. Find out what Merck could be worth using our Discounted Cash Flow (DCF) estimate.
The Merck Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Merck valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price on the Community page. Each scenario links a specific set of potential catalysts and threats to a single estimate of fair value, so you can track over time which storyline seems closest to Merck's actual progress.
Merck’s community view splits between investors who see a deeper pipeline story and those who think the valuation already leans too hard on it.
Bull case: 7% undervalued
"Merck plans to bring over 20 new growth drivers to market in the coming years, and management now points to more than US$70b…"
Discover why this Narrative puts Merck at 7% undervalued.
Bear case: 28% overvalued
"Management’s plan to grow through the KEYTRUDA loss of exclusivity by relying on more than US$70b in non risk adjusted mid 2030s revenue from over 20 new human health products depends on many launches and label expansions still ahead…"
Explore why this Narrative puts Merck at 28% overvalued.
One more Merck check that sits outside the valuation model
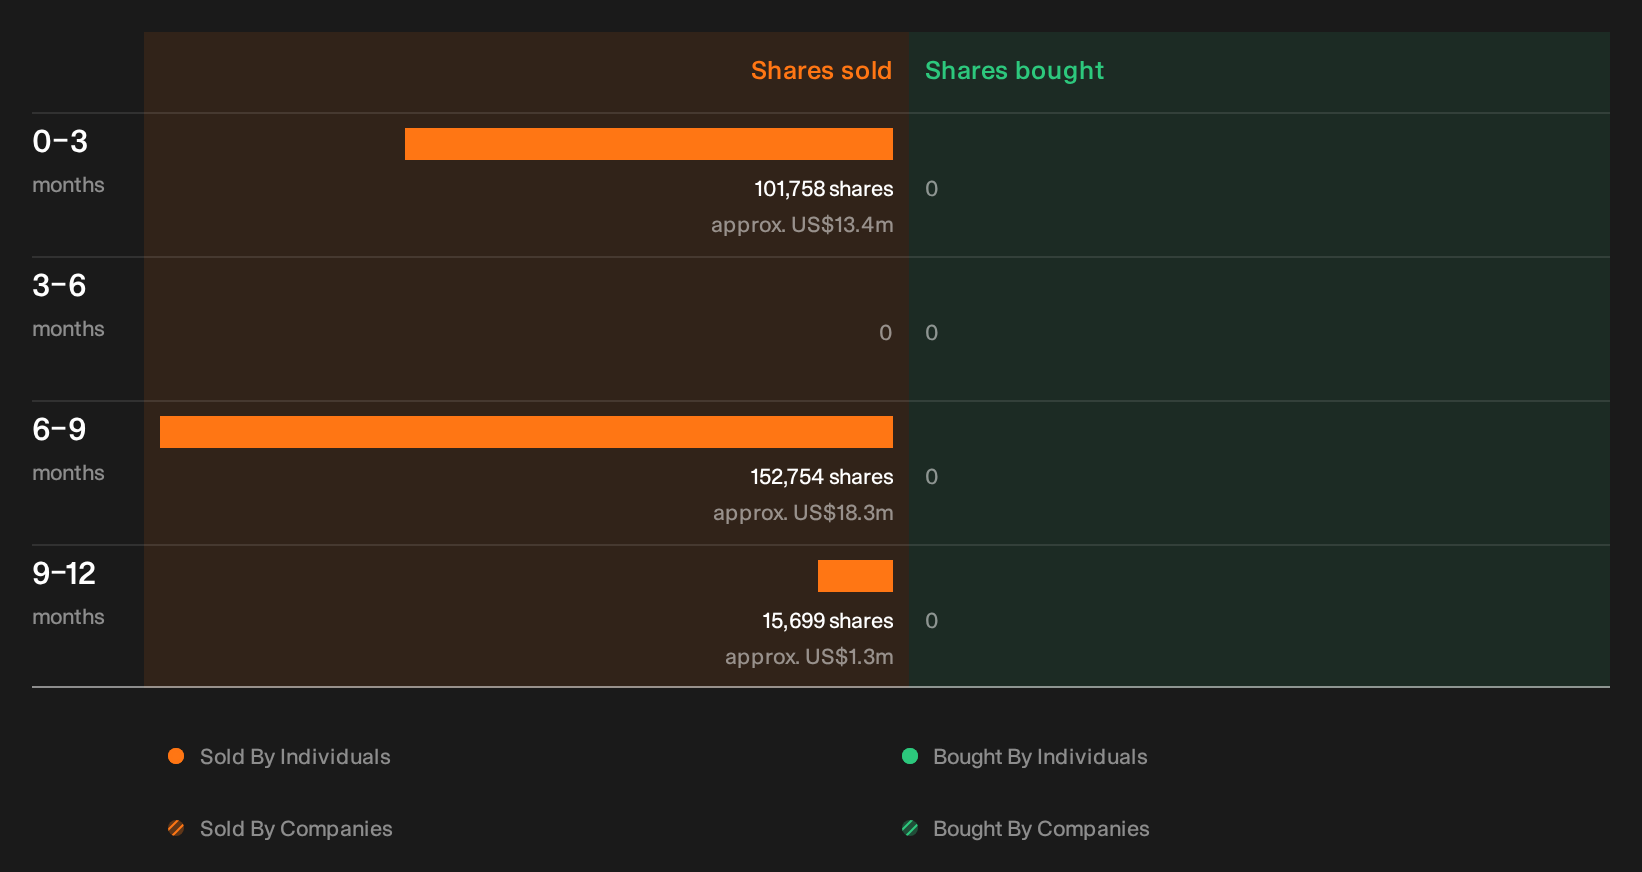
DCF math and pipeline debates are only part of the picture for Merck, because recent transactions by senior insiders can reveal a different kind of signal that our checks have already picked up. See the recent insider selling flagged for Merck.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com