
MassDOT Rail Upgrade Might Change The Case For Investing In CSX Stock (CSX)
- CSX announced the retirement of Chief Operating Officer Mike Cory and a leadership reshuffle, while the Massachusetts Department of Transportation agreed to fund siding and station upgrades in Pittsfield to support permanent seasonal Berkshire Flyer service and reduce freight passenger conflicts.
- The combination of a defined operating leadership handoff and state backed infrastructure investment highlights how CSX is tying executive structure to concrete service reliability and network fluidity projects, rather than treating governance and capital deployment as separate tracks.
- We will now examine how CSX's MassDOT infrastructure agreement could reshape its investment narrative around operations, capital priorities, and service.
Scan other rail and infrastructure focused operators that could move on similar service and payout stories with the hand picked 8 dividend fortresses fueling your next round of ideas.
CSX Investment Narrative Recap
To own CSX, you need to be comfortable with a freight railroad that is trying to push more volume and efficiency through a complex network while keeping service metrics and safety intact. The short term swing factor remains execution on operations as new intermodal corridors and industrial projects come on line. The recent leadership shift looks more evolutionary rather than disruptive, so the core operating thesis is largely unchanged.
The bigger near term risk is that crew availability, infrastructure constraints, or new regulatory pressure undo recent productivity gains. Public scrutiny around safety and staffing is already elevated. If network fluidity or reliability slip as traffic builds, that would test confidence in CSX delivering on its cost and service ambitions.
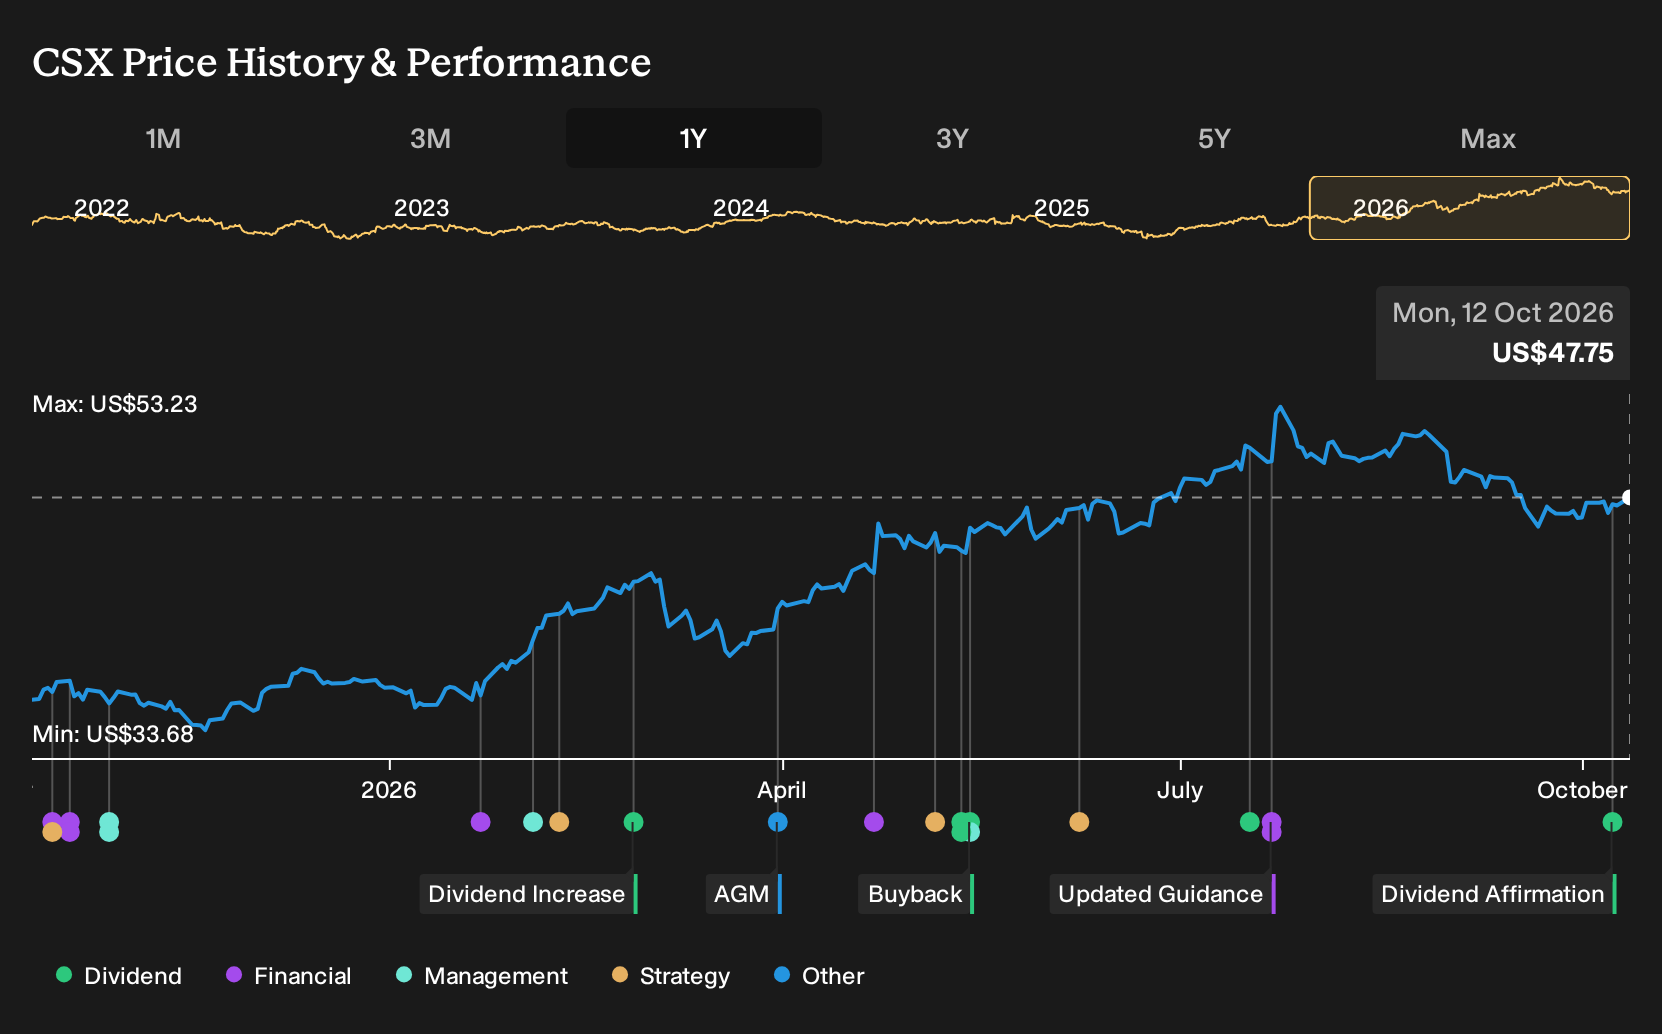
The most relevant fresh data point is the confirmed US$0.14 per share quarterly dividend declared on October 8, payable in December. A steady payout policy can matter for investors who care about cash returns while CSX spends on projects like the Howard Street Tunnel and corridor upgrades that underpin the current efficiency and intermodal volume story.
This dividend affirmation does not change the operational catalysts directly, but it does frame how management balances capital between shareholders and the network. For you, the question is whether CSX can keep funding yard modernization, safety work, and intermodal expansion while supporting this distribution, especially if service issues, higher debt costs, or new safety rules put pressure on free cash flow.
CSX's narrative projects US$16.9b revenue and US$4.5b earnings by 2029. This assumes 5.2% yearly revenue growth and a US$1.3b earnings increase from US$3.2b today.
Uncover why CSX's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic view leans heavily on CSX squeezing extra earnings from efficiency. The most bullish analysts were already penciling in revenue of about US$17.6b and earnings of roughly US$4.8b by 2029. Those forecasts predate the COO transition and MassDOT deal, so you may see their story shift as the new operating team settles in.
Explore 3 other CSX fair value estimates, including one that indicates potential upside of up to 11% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CSX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CSX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CSX's overall financial health at a glance.
Looking for more CSX style investment ideas?
If the CSX story has sharpened your thinking about railroads, service quality, and cash returns, you can broaden that same lens across other businesses using the Simply Wall St Screener. You can quickly filter for balance sheet strength, income potential, or mispriced opportunities that fit the kind of risk reward mix you prefer.
- If capital preservation sits high on your list, start with resilient companies by filtering for 31 resilient stocks with low risk scores. These aim to pair steadier balance sheets with lower risk scores.
- For investors who like getting paid while they wait, scan income ideas built around 8 dividend fortresses. These focus on higher yielding payouts backed by underlying fundamentals.
- Those hunting for potential mispricings can widen the opportunity set using 20 high quality undiscovered gems. This surfaces financially strong businesses receiving less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com