
Does FDA Approval Change The Bull Case For Asahi Kasei (TSE:3407)?
- Asahi Kasei Therapeutics received past US FDA approval for HOVILPRI 100 mg tablets to treat refractory mucocutaneous HSV lesions in immunocompromised adults, supported by a Phase 3 trial where the drug achieved higher complete lesion healing rates and fewer adverse reaction related discontinuations than Investigator's Choice therapies.
- The decision adds an oral, non nucleoside option for a hard to treat patient group and may strengthen Asahi Kasei's specialty pharmaceutical platform as it integrates AiCuris assets into a broader transplant and infectious disease focused portfolio.
- The next step is an assessment of how Asahi Kasei's investment narrative could shift as HOVILPRI's differentiated oral profile enters the US market.
Scan how Asahi Kasei’s move into complex infectious disease treatments compares with other potential breakout healthcare opportunities by reviewing the hand-picked 9 healthcare AI stocks now shaping treatment frontiers.
Asahi Kasei Investment Narrative Recap
To own Asahi Kasei, you need to believe the pivot toward specialty pharmaceuticals and advanced materials can gradually offset slower expected revenue growth of 3.7% a year and a forecast 6.0% margin profile. The HOVILPRI approval reinforces that healthcare is not just an add on, but it does not by itself remove the wide earnings forecast spread out to 2029.
In the near term, a key catalyst remains clear progress on integrating AiCuris and the broader specialty pharma platform toward the ¥300b net sales ambition. The main risk is that newer therapies, including HOVILPRI, scale more slowly than hoped while legacy materials absorb more capital, which could keep earnings closer to the lower analyst expectations.
The HOVILPRI approval is tightly linked to the AiCuris acquisition, so it speaks directly to whether Asahi Kasei can turn acquired virology science into tangible products. An oral, non nucleoside option for refractory HSV fits the plan to build a focused transplant and infectious disease portfolio rather than a broad primary care franchise.
Regarding catalysts, this sets a reference point for how management might bring other AiCuris derived candidates through the clinic and into the US market. Execution risk stays high, especially if commercial uptake is gradual or payers are cautious, but each successfully launched asset can help close the gap between today’s earnings profile and the longer term specialty pharma revenue goals.
Asahi Kasei's current analyst narrative points to revenues of ¥3,564.3b and earnings of ¥213.0b by 2029, based on forecast yearly top line growth of 4.1% and an earnings increase of about ¥20.2b from ¥192.8b today.
Uncover why Asahi Kasei's fair value indicates a 22% potential upside to its current price before that discount to expectations closes.
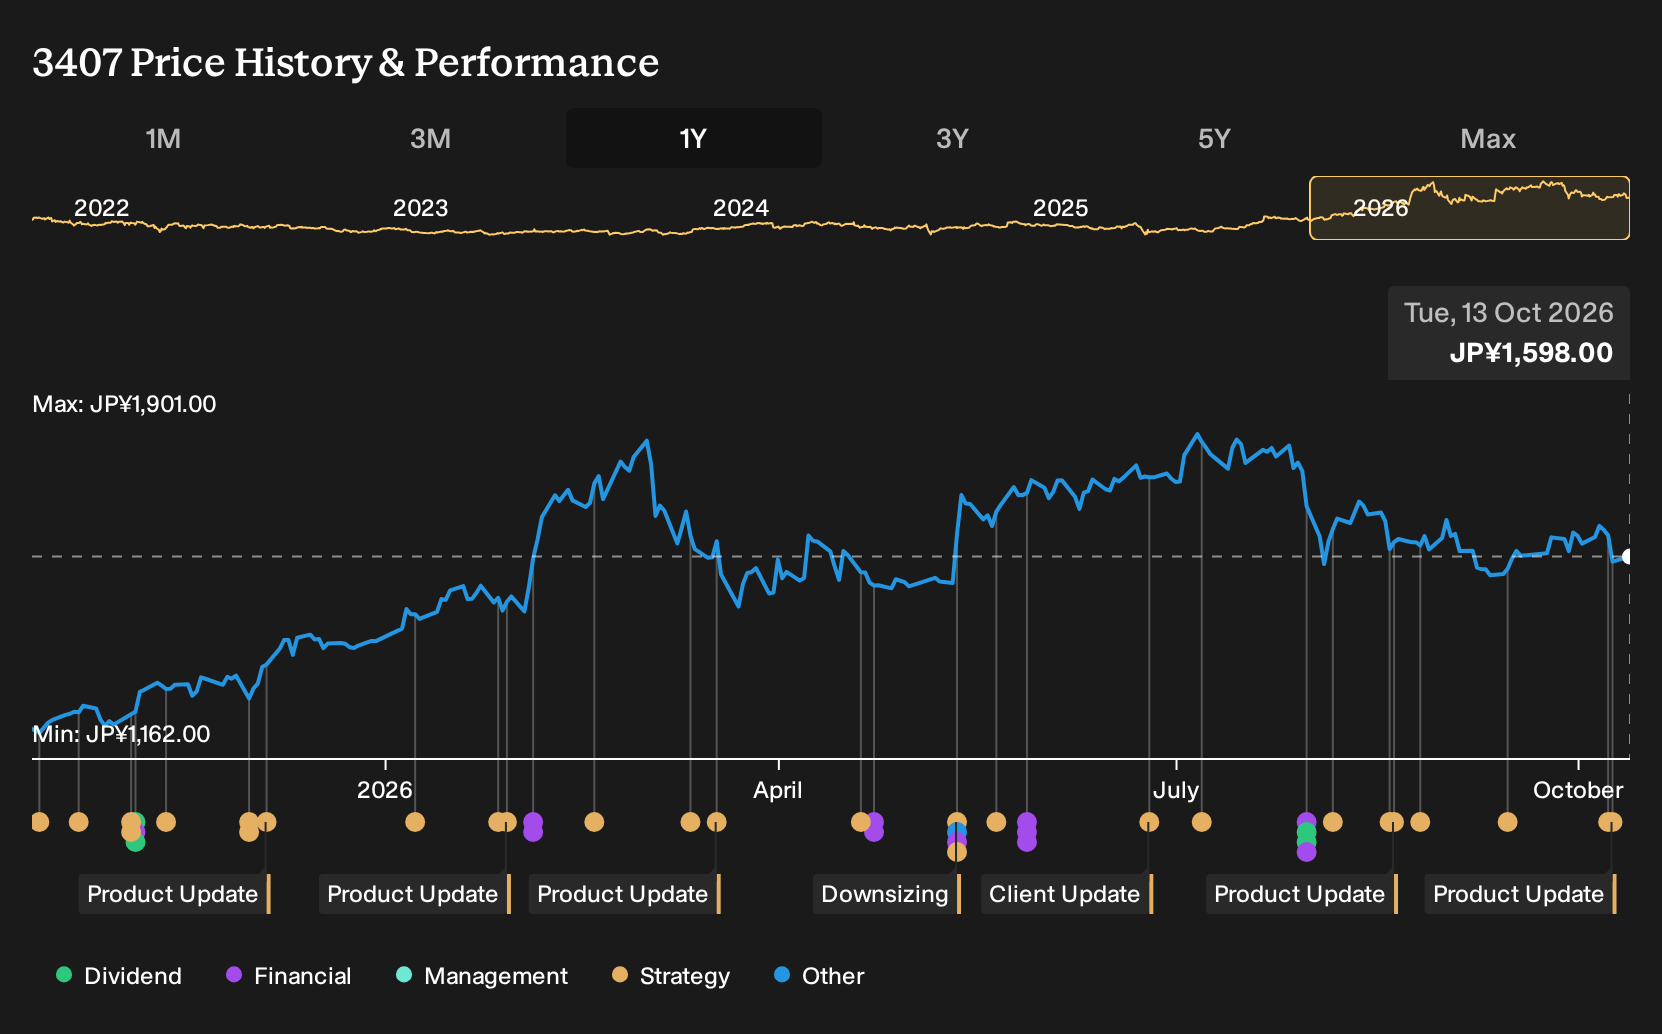
Exploring Other Perspectives
You are seeing one clear split. Consensus analysts expect Asahi Kasei to reach about ¥3,564.3b in revenue and ¥213.0b in earnings by 2029, while the most cautious group was working off roughly ¥3,490.7b and ¥184.0b. Those lower numbers reflect a view that healthcare execution risk is high, which the HOVILPRI approval may now challenge.
Explore 2 other Asahi Kasei fair value estimates, including one that suggests it could be worth just ¥1941!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Asahi Kasei research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Asahi Kasei. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Asahi Kasei's overall financial health at a glance.
Looking for more Asahi Kasei sized investment ideas?
If the Asahi Kasei story has sharpened your thinking about risk, balance sheets and upside potential, use that same lens across a wider watchlist with the Simply Wall St Screener.
- If you prefer resilience over drama and want businesses that might handle shocks more steadily, then start with a 23 resilient stocks with low risk scores that already meet tighter risk criteria.
- If durable finances matter most and you care about cash, debt and liquidity, focus on companies in the list of solid balance sheet and fundamentals (21 results) to pressure test your quality bar.
- If you are hunting for future leaders that are not widely followed yet, broaden your opportunity set with a 74 high quality undiscovered gems that combine strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com