
Did FDA Capacity Expansion Just Shift Alvotech (ALVO) Stock Narrative?
- Alvotech reported that the FDA approved a supplement to its BLA for AVT02, allowing SIMLANDI drug substance to be produced in a second Reykjavik suite. LOTTE Biologics announced a long term manufacturing deal to supply multiple Alvotech antibody biosimilars from its 40,000 liter Syracuse site.
- The combination of doubled in house SIMLANDI capacity and added U.S. contract manufacturing at LOTTE Biologics points directly to execution on supply security, quality control and the ability to support broader global biosimilar demand.
- We will examine how Alvotech's investment narrative develops as expanded SIMLANDI manufacturing capacity influences its operational and regulatory profile.
Alvotech Investment Narrative Recap
To own Alvotech, you need to believe in a focused biosimilar manufacturer that can turn its AVT02 and broader pipeline portfolio into steady commercial volume, not just milestone driven revenue. The key near term swing factor remains execution on launches and market share in highly competitive autoimmune categories, where pricing pressure can quickly test margin discipline.
The biggest risk still sits in regulatory and operational timing, since delays can disrupt those milestone flows and stress a balance sheet that already carries a high debt load and negative equity. The fresh capacity wins only matter if demand materializes and partners convert that supply into consistent orders.
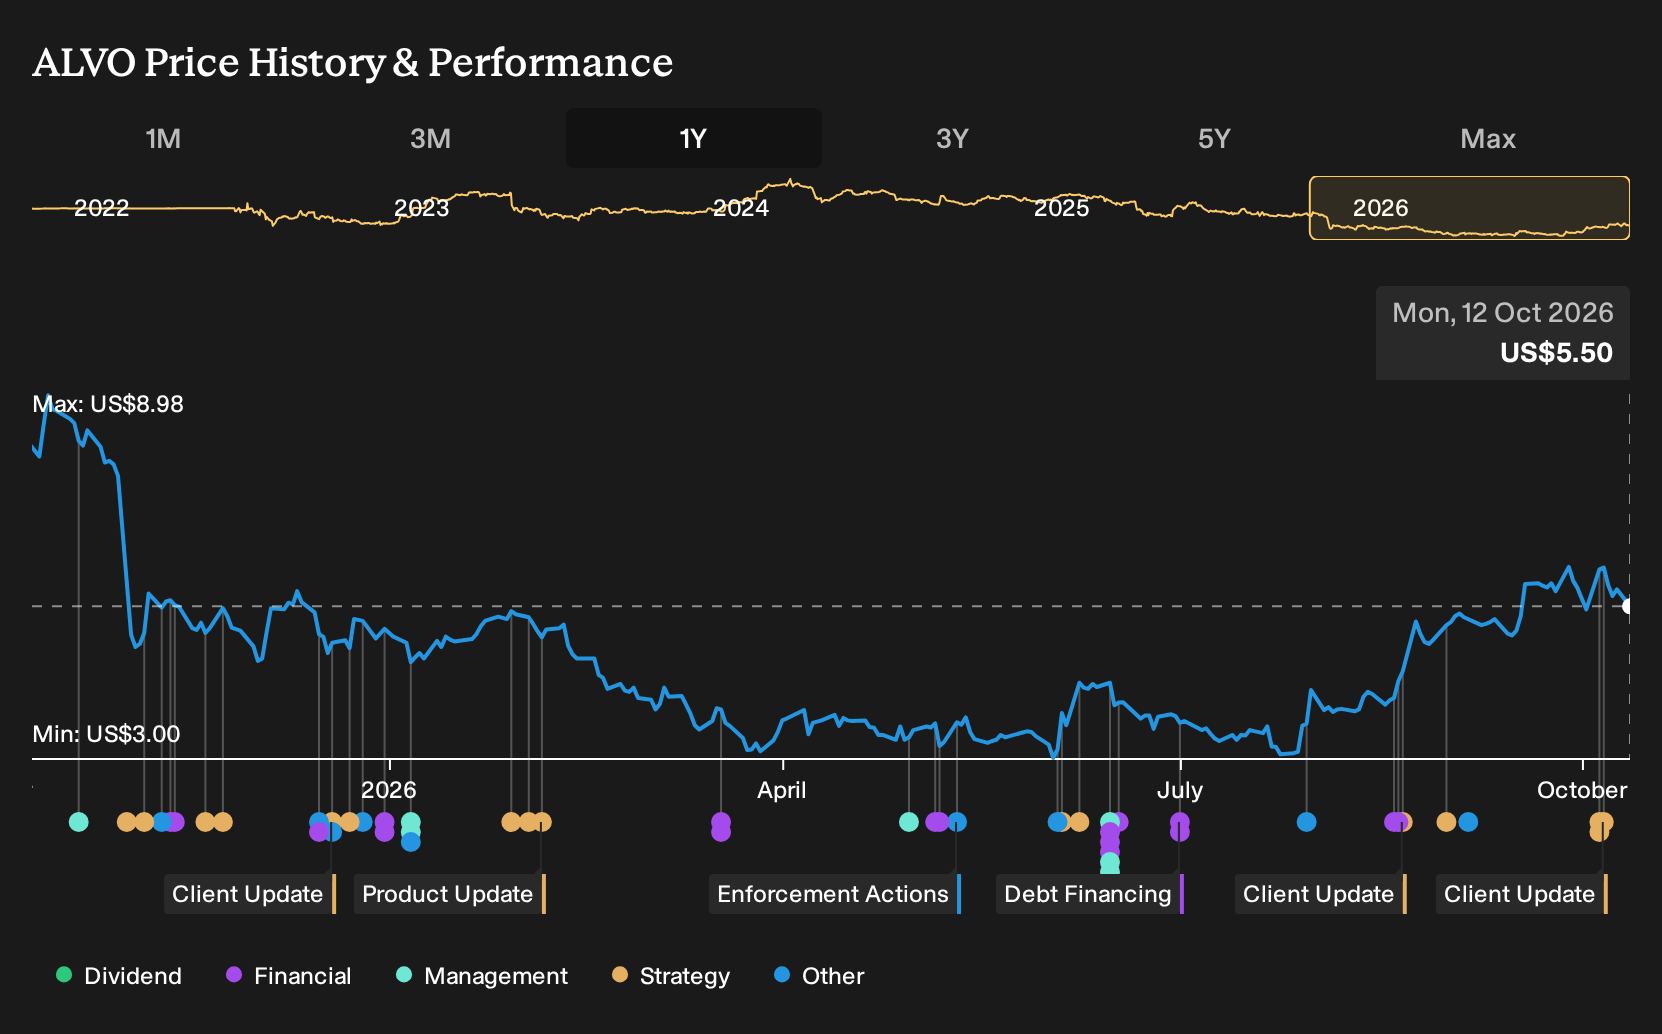
The FDA approval for SIMLANDI drug substance production in Alvotech’s DSM2 suite is probably the most operationally relevant update here. It confirms that earlier inspection issues at Reykjavik are resolved and gives the firm flexibility to manufacture AVT02 for both U.S. and European markets from two suites instead of one.
That extra room to produce matters for catalysts tied to AVT02 uptake and future biosimilar launches that share the same infrastructure, such as AVT03 and AVT05, which already use DSM2 for European commercial supply. It also partially mitigates regulatory risk, since Alvotech is no longer reliant on a single suite for U.S. SIMLANDI drug substance if one area faces scrutiny or downtime.
Alvotech's analyst narrative points to forecast revenue of US$976.3 million and earnings of US$223.1 million by 2029, built on an assumed 25.4% yearly revenue growth rate and a swing in earnings of about US$402.7 million from a loss of US$179.6 million today to that projected profit level.
Uncover why Alvotech's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Alvotech focuses on upside from operating leverage rather than just regulatory timing. The most optimistic analysts were already pencilling in revenue of about US$1.2b and earnings of US$360.7 million by 2029 before this FDA and LOTTE manufacturing news. That group presents a more upbeat story than consensus, so treat this as a reminder that reasonable minds can disagree and consider several scenarios for yourself as fresh information becomes available.
Explore 4 other Alvotech fair value estimates, including one that suggests as much as 370% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alvotech research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alvotech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alvotech's overall financial health at a glance.
Looking for more investment ideas beyond Alvotech?
If the Alvotech story has sharpened your view on risk, balance sheets, and future cash flows, it can help to benchmark that thinking across a wider watchlist. The Simply Wall St Screener lets you apply the same discipline to different corners of the market and pressure test where you want to take portfolio risk next.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that already clear tough quality filters.
- If you are hunting for potential mispricing, compare Alvotech with a set of 29 high quality undervalued stocks that combine solid fundamentals with discounted market prices.
- Those who want differentiated opportunities can scan 20 high quality undiscovered gems that pair strong business quality with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com