
Missed Samsung Electronics' 156% Run? The Bet Holders Made
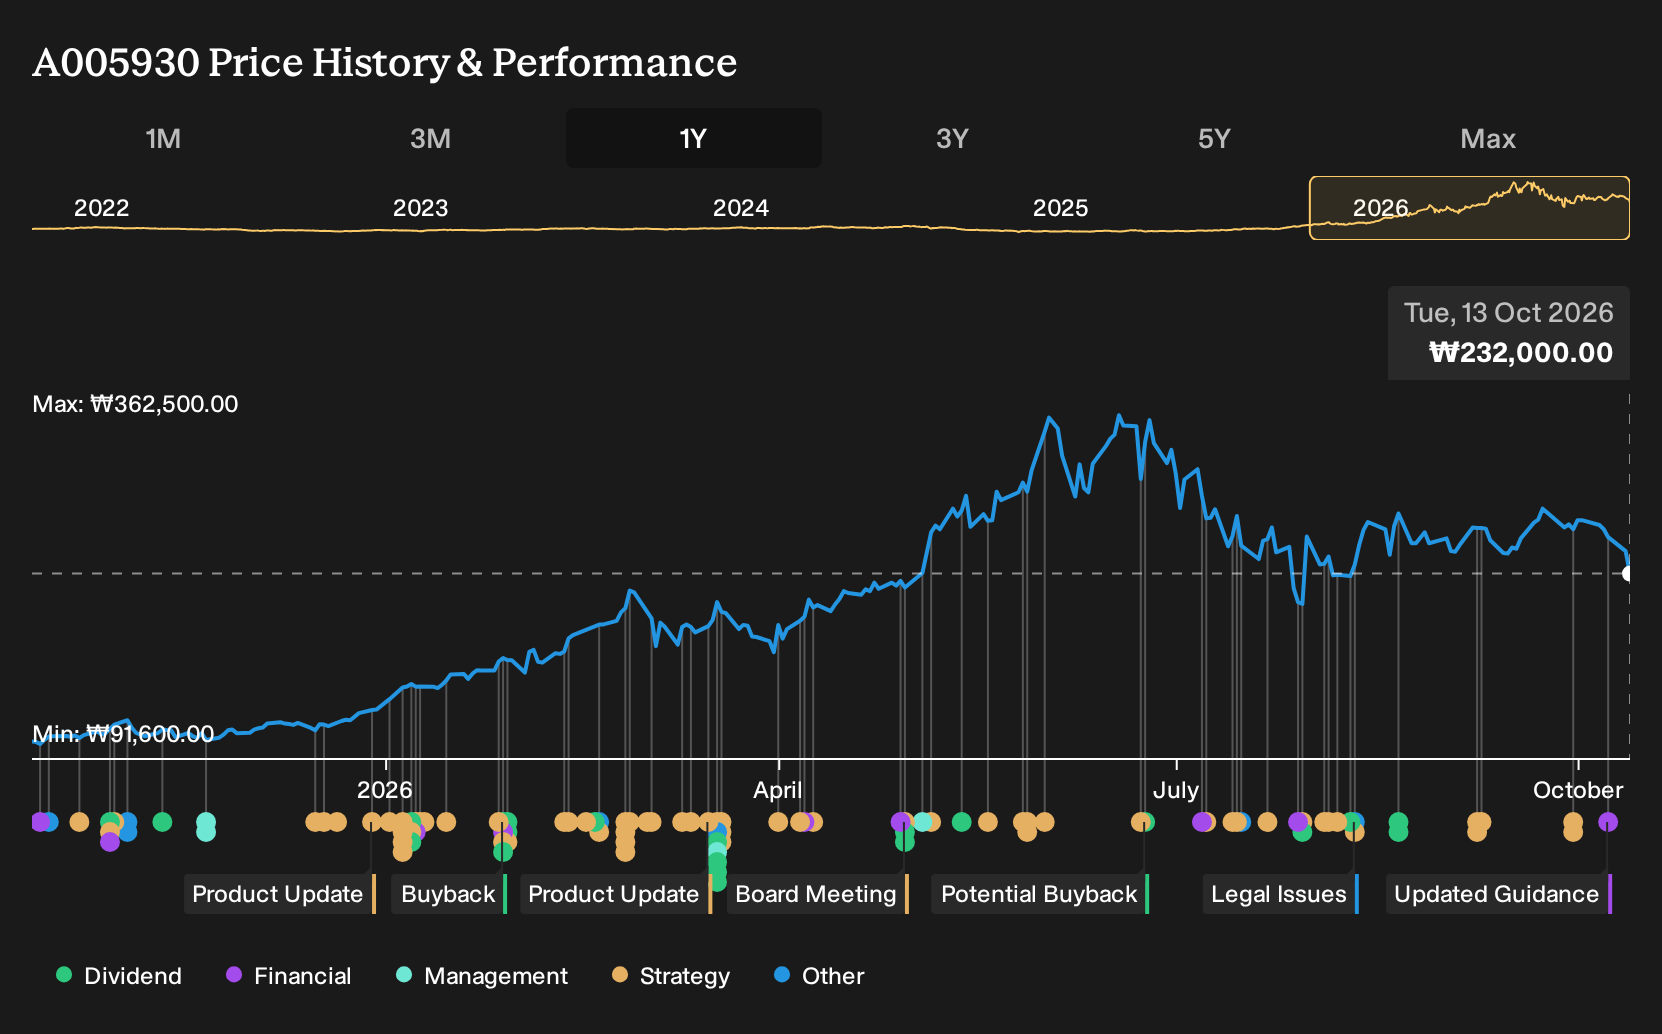
If you had looked at Samsung Electronics in October 2025, you would have seen bullish AI optimism sitting beside warnings about heavy chip cycles and geopolitical risk. For Samsung Electronics shareholders, the return over the past year was 155.7%, including dividends. That outcome now sits next to news of sharply higher net margins and record demand headlines. If you were weighing those mixed signals back then, what really justified owning the stock?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Samsung Electronics has already moved. See which of 184 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Arguing About On Samsung Electronics
The shares cost ₩93,200 at the start of the period, and anyone looking at Samsung Electronics then had to decide which future to back.
The bullish narrative put Fair Value at ₩100,000. It leaned on AI memory demand and early orders in server products, plus confidence that 2 nm production and deeper AI integration across devices would help margins and support revenue growth assumptions of 11.5% a year.
The more cautious view set Fair Value at ₩83,723. It still leaned on AI and memory demand, but flagged geopolitical risk, heavy investment needs, and an assumed revenue growth rate of 4.2% with profit margins only reaching 11.0% over three years.
What The Results Changed For The Samsung Electronics Argument
Samsung Electronics rolled out UFS 5.0 storage and AI-heavy wearables and tablets, which backed the bullish case that leaned on AI integration across devices. At the same time, Asian chip stocks faced pressure from concern about AI spending and Chinese competition, which echoed the cautious view on rivalry and cyclicality. Revenue, profit and net margin all rose, so the evidence leaned toward the optimistic case.
The key issue here was profitability under heavy AI investment. For another stock built on an AI thesis, check whether net margin and absolute profit move in the same direction as AI product announcements over several reporting periods.
What Samsung Electronics' Price Now Assumes
Samsung Electronics now trades at ₩232,000, with the selected Narrative putting Fair Value below that level. The argument leans on a memory driven story, where AI demand and higher DRAM and NAND pricing do much of the heavy lifting.
The key question for you is what must keep going right for that to hold. A buyer today needs to judge whether the current memory upcycle can persist without overinvestment creating excess supply.
"Memory chips are largely a commodity, so performance depends heavily on how well supply matches demand. The key is avoiding overinvestment that leads to excess supply, which can quickly push prices down."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Another Way To Play AI Devices
Samsung Electronics leans on high end hardware and embedded AI features. You could also look where that same buyer spends more time.
People who pay up for premium phones and wearables often build habits around media, payments and cloud tools that follow them everywhere.
One large ecosystem player focuses heavily on those services, tying apps, subscriptions and on device intelligence tightly together.
Its pitch is that AI centric devices become a personal hub, while recurring digital services turn that habit into a longer running business relationship.
If that model keeps gaining traction with high spending users, the hardware upgrade cycle is only one part of the story.
One Narrative has already put a figure on it. → Uncover the company trading 16% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com