
Did Workday Screening App Just Shift Everforth (EFOR) Investment Narrative?
- In late September 2026, DISA Global Solutions announced a Built on Workday pre employment screening app created with Everforth partner TopBloc, giving recruiters a native Workday Recruiting tool for background checks, drug testing and compliance.
- The launch spotlights Everforth’s role in Workday centric solutions, tying its consulting and ecosystem partnership focus directly to repeatable, workflow embedded software for large employers.
- We will now look at how Everforth’s investment narrative could be influenced by its role in this Workday native screening capability.
Scan how Everforth’s Workday centric approach compares with peers by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) that are also building repeatable software for large employers.
Everforth Investment Narrative Recap
To own Everforth, you need to believe its heavier consulting and platform mix, deep partner ties, and cost programs can turn modest 2.6% forecast annual revenue growth into meaningfully higher earnings, despite currently thin 2.1% margins and weaker recent profit trends. The central near term swing factor is execution on higher value consulting work and structural savings without further one off hits.
The biggest near term risk remains balance sheet flexibility, with debt not well covered by operating cash flow and earnings still rebuilding after a large one off loss. This new Workday centric win looks helpful for the operating story but not a game changer for those financial pressure points on its own.
The DISA Built on Workday Pre Employment Screening App matters because it shows Everforth’s TopBloc unit delivering repeatable, workflow embedded software around a major enterprise platform. That directly lines up with the broader catalyst of clients tying cloud and AI budgets to end to end modernization programs where Workday, Microsoft, Databricks and others sit at the center of multi year projects.
For you, the key question is scale and repeatability. If Everforth can turn this kind of Workday native deployment into a pattern across large employers, it supports the thesis of a richer consulting and platforms mix, potentially higher margins, and more resilient commercial bookings. If adoption stalls or similar ecosystem deals fail to build, the existing risks around modest revenue growth and leverage stay front and center.
Everforth Consensus Targets Behind The Workday Story
Everforth's narrative projects US$4.3b revenue and US$143.4m earnings by 2029. This rests on analysts assuming 2.4% yearly revenue growth and about a US$60.4m earnings increase from US$83.0m today.
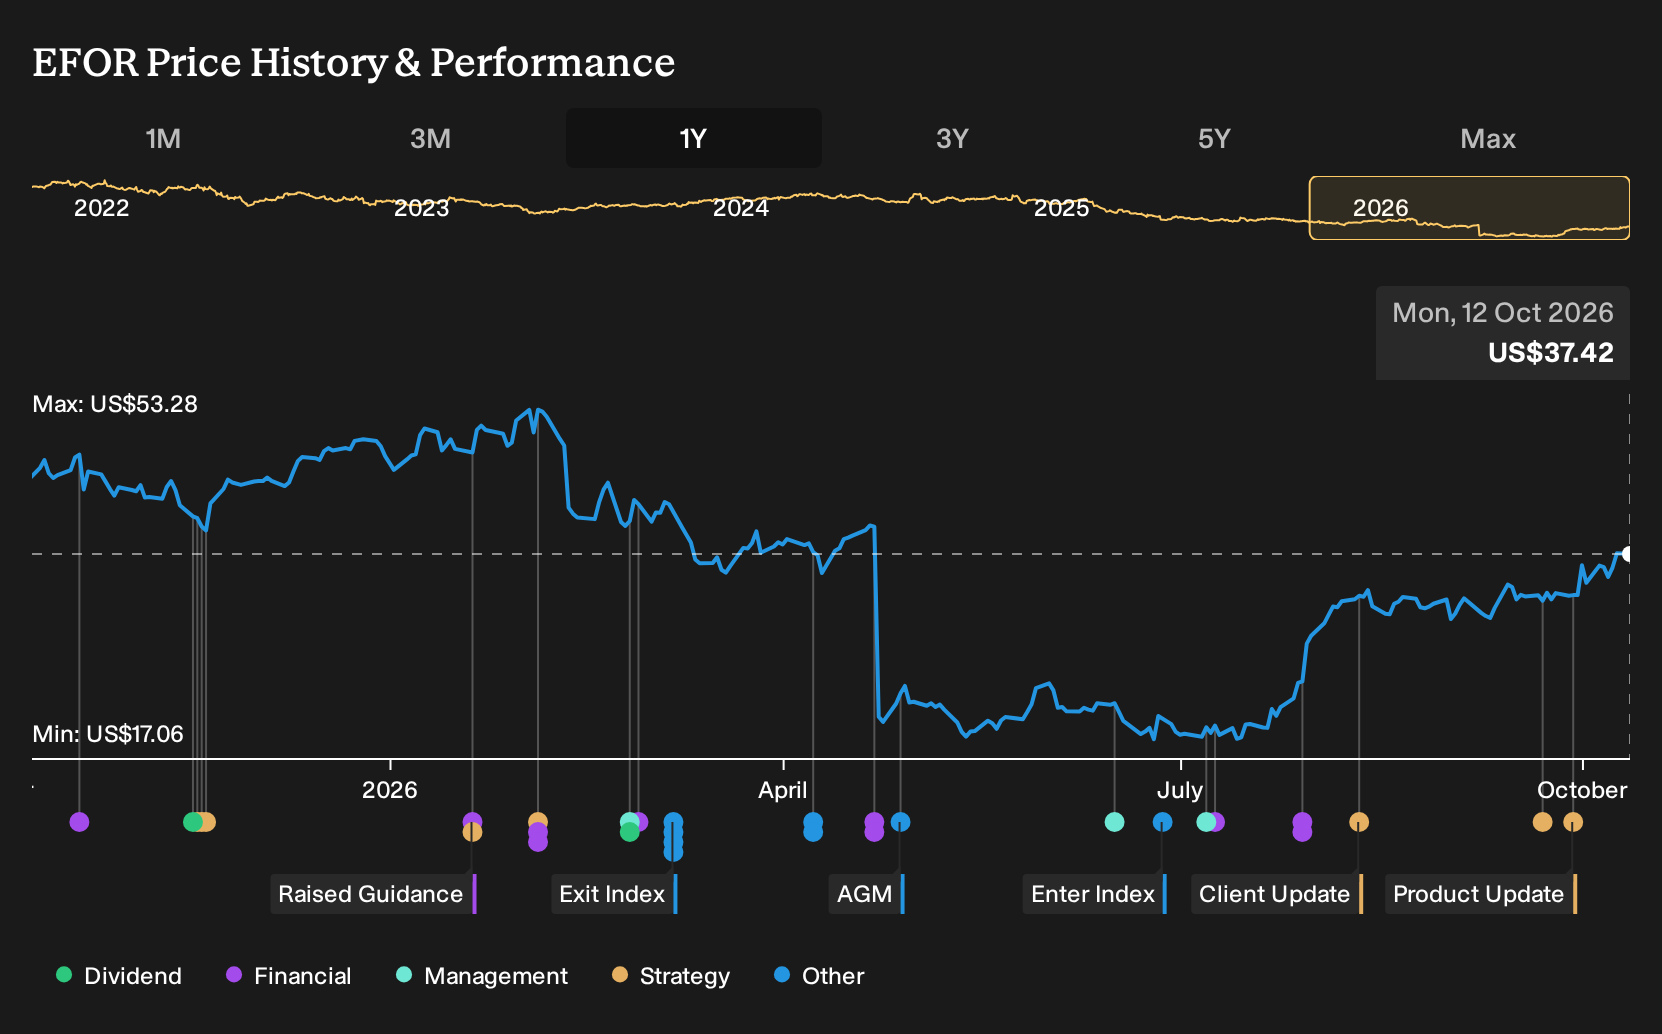
Uncover why Everforth's fair value indicates a 27% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Everforth as a margin expansion story, with revenue projections around US$4.4b and earnings near US$218.9m by 2029 before this Workday app existed. You can see how this Workday native win might strengthen that more upbeat view, or prompt fresh skepticism, so it is worth comparing several viewpoints yourself.
Explore another Everforth fair value estimate, including one that suggests up to 93% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Everforth research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everforth?
If the Everforth story has you rethinking how you spread risk and opportunity across your portfolio, it can help to line it up against a broader watchlist of potential candidates using the Simply Wall St Screener.
- For investors who want potential value combined with quality fundamentals, scan a curated set of 29 high quality undervalued stocks that might offer a more attractive balance between price and business strength.
- If capital preservation matters just as much as upside, filter for 31 resilient stocks with low risk scores that pair stronger balance sheets with milder risk profiles.
- When you want to get ahead of the crowd, look across 20 high quality undiscovered gems that match solid fundamentals with less widely followed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com