
VinFast Auto (VFS) Could Be 50% Below Fair Value Following 17% Delivery Growth
VinFast Auto (VFS) is back in focus after reporting preliminary September deliveries of 23,624 electric vehicles in Vietnam, a 17% month on month increase and 177,697 units year to date.
The fresh delivery update lands against a mixed trading backdrop. VinFast Auto’s share price has slipped over 30 days, with a 1 month share price return of a 4.98% decline at a last close of US$3.05. The 1 year total shareholder return is down 5.86%, and the 3 year total shareholder return has fallen 53.29%, signaling that long term holders have felt more pressure even as recent operational headlines and European product launches start to rebuild interest.
Scan how VinFast Auto compares with other EV players by reviewing a hand picked set of 92 AI infrastructure stocks shaping the hardware backbone for electrification and automated transport.
VinFast Auto’s delivery surge in Vietnam and fresh push into Europe sit awkwardly against a share price that has drifted lower. Is most of the rerating already behind the stock, or is the upside still ahead as investors reassess what they are willing to pay?
Most Popular Narrative: 50% Undervalued
VinFast Auto’s most followed valuation story pegs fair value at $6.05 a share, roughly double the recent $3.05 close. As a result, the gap between narrative and market pricing is wide and hard for investors to ignore.
Ongoing expansion and accelerated adoption of electric vehicles in key emerging markets, particularly Vietnam, Indonesia, and the Philippines supported by rising urbanization and a growing middle class are set to drive sustained volume growth and revenue expansion as VinFast continues broadening its product portfolio and increases market penetration.
See why 8 investors see VinFast Auto as 50% undervalued.
Result: Fair Value of $6.05 (UNDERVALUED)
Still, the bullish VinFast Auto narrative leans heavily on continued funding support and improving margins, while heavy cash burn and reliance on intragroup demand remain pressure points.
Find out about the key risks to this VinFast Auto narrative.
Another View: VinFast Auto Looks Expensive On Sales
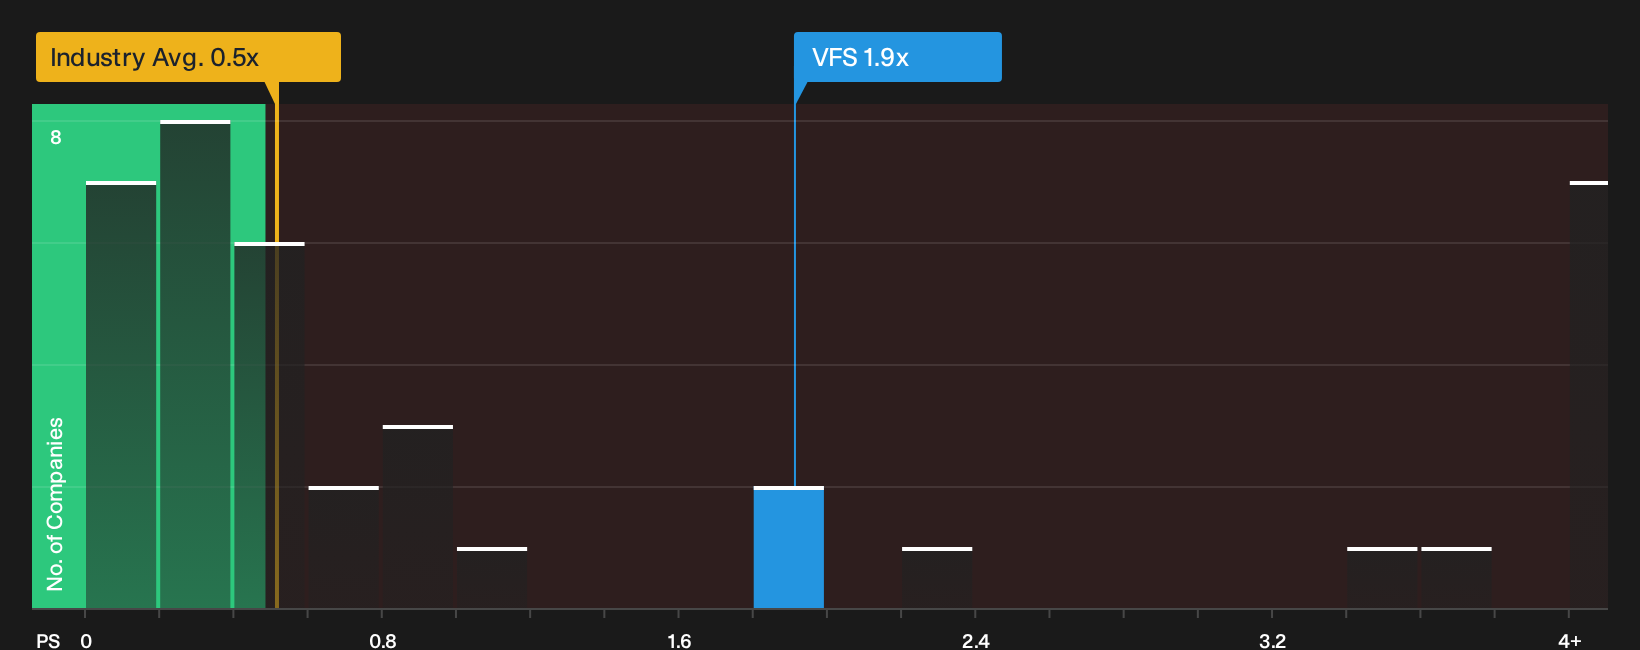
Zoom out from that $6.05 fair value and the picture shifts. On a P/S of 1.9x, VinFast Auto trades at almost 4x the US Auto industry average of 0.5x and above peer levels of 1.3x, while the fair ratio sits at just 0.1x. That kind of gap points to valuation risk if sentiment cools.
For a closer look at how the current pricing stacks up against sales and peer benchmarks, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed sentiment around VinFast Auto can cut both ways, so treat this as a prompt to review the data quickly and form your own stance based on the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond VinFast Auto?
If VinFast Auto has your attention, do not stop here. Broaden your watchlist with a few focused idea sets that target very different kinds of opportunities.
- Target potential mispricing by scanning companies that combine quality and attractive valuations through the 29 high quality undervalued stocks.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially robust businesses.
- Hunt for possible future leaders at an early stage by checking out 20 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com