
Nebius (NBIS) Stock Could Be Above Fair Value After Inferize Deal
Nebius Group has delivered a powerful long run for shareholders, yet the stock has recently come under pressure, which puts fresh attention on whether its current market value can be explained by its sales base. With the share price moving around fast and investor focus sharpened by new AI infrastructure deals, the key issue is how much revenue the business is being asked to support.
- Over the past 5 years Nebius Group has returned 168.3%, which puts a lot of accumulated optimism on the line when you ask how fully its sales already reflect that journey.
- The acquisition of Inferize and the emphasis on AI inference efficiency may support higher capacity utilization and potentially smoother revenue conversion, while the need for ongoing capital raises keeps attention on how much sales can fund over time.
- The analysts covering Nebius Group have run their own numbers. See what analysts think Nebius Group's shares could be worth.
The issue now is whether Nebius Group's current share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
To pressure test Nebius Group's recent AI-driven surge against other infrastructure plays, it helps to line it up next to 92 AI infrastructure stocks.
Has Nebius Group Run Too Far on Sales?
P/S is the cleaner yardstick for Nebius Group right now because investors are paying far more for its revenue than for a typical software stock’s earnings.
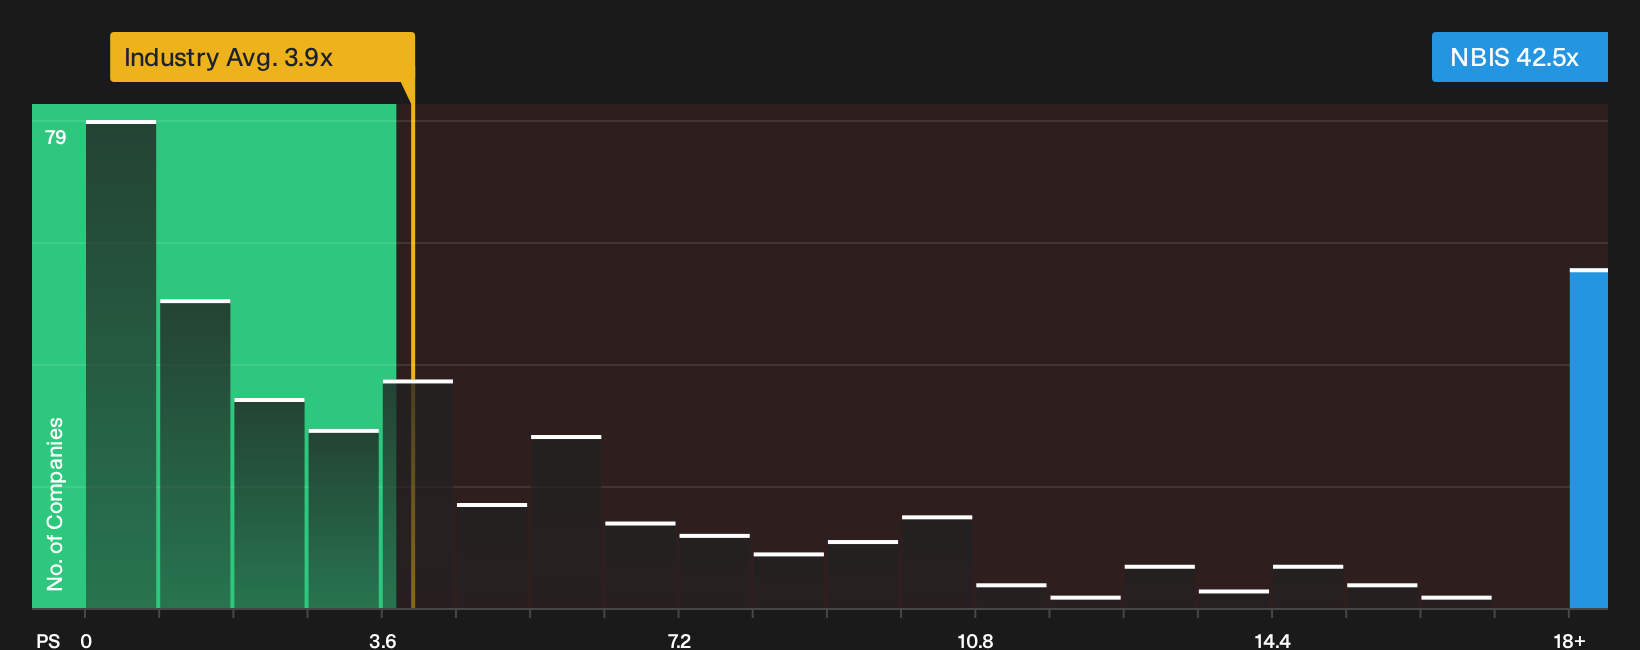
Nebius trades on a P/S ratio of 41.8x, which is far above the Software industry average of 3.9x and also well ahead of the 11.9x peer group level. On this lens the stock prices in a very rich claim on each dollar of current sales compared with both broad software peers and more direct AI infrastructure comparables.
The Fair Ratio model, which adjusts for Nebius Group’s growth profile, margins, size and risk, still suggests the present P/S multiple sits above the level implied by those fundamentals so the shares screen as overvalued on this measure. Despite the recent Inferize acquisition and the long term AI capacity contracts helping frame a strong commercial story, the valuation already assumes a lot of good news is supported by future revenue delivery. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group's valuation puzzle introduces the role of Simply Wall St Narratives, which map out the specific growth, margin and earnings paths that would need to occur for the stock to be worth meaningfully more or less than it is today on the market. Each narrative links its valuation to a clear view on how growth, profitability and risk could evolve over time, allowing you to revisit that logic as fresh information appears on the Community page.
Nebius Group now splits opinion between investors who see AI demand and funding support as underpriced and those who think capital intensity and margins still anchor the story.
Bull case: 27% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability…"
Discover why this Narrative puts Nebius Group at 27% undervalued.
Bear case: 90% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a massive multi-year plan to secure 1 gigawatt of power by 2026, will likely drive down free cash flow and pressure net margins for years…"
Explore why this Narrative puts Nebius Group at 90% overvalued.
An unresolved piece of the Nebius Group puzzle
Big capital plans and rich sales multiples are only part of the story for Nebius Group, because the people directing those choices and how they are rewarded can tilt the risk profile in ways the ratios alone never show. See who runs Nebius Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com