
Ithaca Energy (LSE:ITH) M And A Call Puts Fair Value Debate Back In Focus
Ithaca Energy M&A call puts capital returns in focus
The recent M&A call between Ithaca Energy (LSE:ITH) and Suncor Energy has sharpened attention on how Ithaca’s deal activity, dividend plans and cash generation tie into the current share price.
Ithaca Energy’s recent M&A call lands after a powerful run, with an 81.16% year to date share price return and a 161.93% three year total shareholder return, and the latest 2.44% one day and 7.29% seven day share price gains suggest momentum is still building as investors reassess cash returns and deal risk.
Scan Ithaca Energy’s surge in capital returns alongside a hand picked set of income ideas in our 2 dividend fortresses, which are built around dividend strength and payout resilience.After a run like this and fresh M&A noise around Ithaca Energy, the real tension now sits in the numbers. Does the current valuation still leave enough upside to justify new risk?
Most Popular Narrative: 4% Undervalued
The most followed narrative currently pegs Ithaca Energy’s fair value at £3.05, only slightly above the last close at £2.94. This puts the debate firmly on how much of the recent M&A story and dividend guidance is already baked into that price.
The analysts have a consensus price target of £3.05 for Ithaca Energy based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £3.59, and the most bearish reporting a price target of just £2.3.
See why 22 investors see Ithaca Energy as 4% undervalued.
Result: Fair Value of £3.05 (UNDERVALUED)
Still, if Ithaca Energy delivers stronger than expected production from projects like Rosebank and Cambo or executes accretive M&A, today’s cautious narrative could prove too conservative.
Find out about the key risks to this Ithaca Energy narrative.
Another View on Ithaca Energy’s Valuation
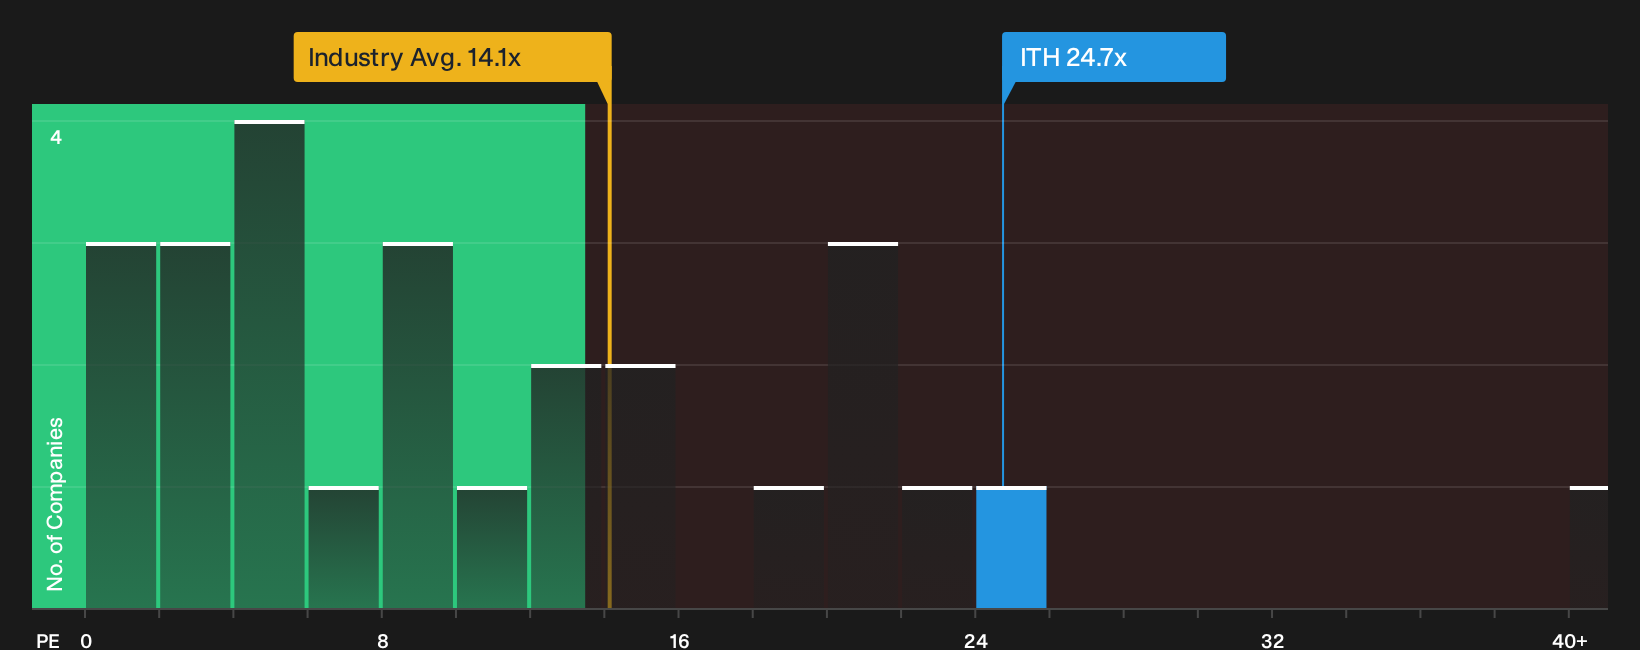
On simple earnings multiples, Ithaca Energy looks expensive. The shares trade on a P/E of 24.7x compared with 14.1x for the wider European oil and gas group and a fair ratio of 17.8x. That gap points to limited margin for error if sentiment cools.
For a closer look at what the current P/E implies about future outcomes, and how it compares with peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So is the mood around Ithaca Energy too optimistic or too cautious right now? Move fast, review the full risk and reward picture, and weigh those trade offs for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ithaca Energy?
If Ithaca Energy has sharpened your focus on valuation and risk, now is the moment to widen your net and pressure test your thinking across fresh opportunities.
- Target sturdier payouts by scanning a curated pool of income opportunities with the 2 dividend fortresses that highlight yield and balance sheet support.
- Hunt for mispriced potential by running through the 8 high quality undervalued stocks that filter for quality fundamentals at prices that might not match underlying strength.
- Prioritise resilience first by working through the 4 resilient stocks with low risk scores that tilt toward steadier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com